Substack

Showing posts with label Middle Class. Show all posts

Saturday, October 17, 2026

Weekend reading links

1. The labour market effects of AI is not clear.
Even at the entry level, graduate unemployment has been rising since 2015, pointing to factors beyond AI.


China’s total population peaked at 1.4 billion in 2021 and is now falling by three to four million people per year—roughly equivalent to losing one Los Angeles each year. By the 2040s, if China continues to follow East Asia’s descent to ultralow fertility rates, it will shed around one percent of its population annually—roughly ten million people, more than the population of New York City. At the same time, the proportion of China’s population aged 65 and older will surge, doubling from 15 percent today to around 30 percent in the 2040s, and then rising to well over 40 percent by the late twenty-first century. The size of that cohort in the United States, by contrast, is projected to rise far more gradually, from around 19 percent of the population today to just over 23 percent in 2060.

The essay by Carl Minzner  talks of how the centralisation, a paranoid state, and suppression of dissent is creating the conditions for discontent and social instability. Sample this. 

In 2023, Beijing created the Central Social Work Department and charged it with monitoring those suffering from any of the “four lacks” (no spouse or children, no job or stable income, no normal social interactions, or no financial assets, such as a house or car) or any of the “five losses” (failed investments, career or life setbacks, emotional imbalances, mental illness, or failed personal relationships). Beijing views such individuals as potential security threats capable of mass attacks, such as the November 2024 rampage in which a 62-year-old man, dissatisfied with the property settlement after his divorce, drove his car into a crowd and killed dozens.

3. Only 6.6% of Indians earn a middle class monthly salary of Rs 25,000. Even this is likely on the higher side, and I am not even talking about the low baseline. 

4. China and EU agree tacitly on an arrangement whereby EU will impose a quota ceiling on Chinese hybrid car imports without any retaliatory action by China. 
The agreement would more than halve projected exports over the next four years, reducing the number of hybrids shipped by China by “several millions”. On the current trajectory, Chinese exports to the EU would hit 800,000 this year. In 2027 alone, the deal would reduce imports by between 500,000 and 700,000 vehicles, cutting the EU’s expected trade deficit by between €10bn and €14bn, according to an EU official. The 2027 annual quota was expected to be initially about 350,000 vehicles, increasing by 6 per cent a year for the following three years, the official said. The EU’s trade deficit in goods with China hit €360bn in 2025 and has increased since. In the second quarter of 2026, it was €103bn, up from €93bn in the same period last year. Vehicles and machinery were the biggest contributors... The share of the EU market for plug-in hybrid electric vehicles controlled by Chinese imports rose to 25 per cent in the first half of this year and for other hybrid electric vehicles to 14 per cent, both up from 2 per cent in 2024.
Debt servicing payments alone are expected to account for 19.2 per cent of the central government’s general public budget this year, up from 12 per cent in 2014, according to a new study from the Conference Board. The problem is especially acute at the local government level, where debt interest payments have risen 16 per cent annually over the same period. Together, central and local government debt interest payments are projected to amount to Rmb1.4tn ($209bn) in 2026, up from about Rmb348bn in 2014... Public debt-to-GDP is set to hit 122 per cent by the end of 2026, up 48 percentage points from its pre-pandemic level, according to Morgan Stanley analysts... Economic growth slipped to 4.3 per cent in the second quarter, below the official full-year target range of 4.5 to 5 per cent, on the back of weakening retail sales and sharp falls in fixed-asset investment... While the central government runs a fiscal deficit of about 4 per cent, the augmented deficit, a wider measure of state spending, is running at about 10 per cent of GDP, according to Goldman Sachs... “Spending on debt interest payments rose 341 per cent” between 2013 and 2025, according to the Washington-based Center for Strategic and International Studies, “faster than any other major budget category”. The think-tank noted that about 14 per cent of US government spending went towards interest payments this year while Japan, one of the world’s most indebted governments, spent almost 26 per cent.

6. The remarkable stability of occupations.

Long-established ones are far more durable — more than 70 per cent of workers today are employed in occupations that existed in the late 19th century. Rather than eliminating these occupations, technology has transformed them.

7. Forward guidance (among other things) wins Nobel Prize precisely in the year the new Fed Chairman is taking steps to reverse it.

8. China clocks a 36.3% growth in dollar terms in its exports in September over the same month last year, the biggest increase since January-February 2021. Trade surplus for the first nine months was $938.1 bn, compared to $875 bn last year. 

This comes even as economic growth slows, reporting 4.3% in the second quarter, one of the lowest quarterly growth rates in decades and below the full year target band of 4.5-5%. 

9. While subsidies were a major contributor to Chinese companies becoming dominant in manufacturing, they have been far sighted enough to sharply increase their R&D spending and move up the value chain and become global manufacturing leaders across the value chain. 

10. Richard Waters puts the AI investment in perspective.
To take one recent estimate, from the Brookings Institution: Spending on the AI services produced by all those data centres would need to account for an astounding 9.2 per cent of US GDP by 2032 for their operators to make a decent economic return... The five biggest hyperscalers — Alphabet, Amazon, Meta, Microsoft and Oracle — have raised their capex budgets throughout the year and currently expect to spend $800bn, nearly twice as much as last year. That is set to eclipse their combined forecast cash flow of around $700bn... according to the Brookings report, it will take an extraordinary jump in AI demand to justify the construction boom. By 2032, customers would need to spend $3.7tn a year (the 9 per cent of US GDP). Tech research firm Gartner came up with a similar calculation this week, estimating that $8.5tn of AI revenue will be needed between now and 2030 to produce decent investment returns on all the new data centres. The actual AI revenue Gartner forecasts over that period: $3.6tn.

Saturday, August 2, 2025

Weekend reading links

1. K-shaped growth in the Indian car industry?

Hyundai Creta, a premium feature-laden mid-segment SUV with prices starting at Rs 11 lakh-plus, has emerged as the country’s top selling car in June 2025. With Maruti’s Ertiga, a Multi-Utility Vehicle, the two accounted for almost two-thirds of all cars sold in the month. What is also remarkable is that nearly one in three Creta buyers is a first-time car owner. Officials in Hyundai said the contribution of first-time buyers in Creta’s customer base has gone up sharply to 29 per cent in 2024 from just 12 per cent in 2020. The car market has had a mixed year in 2024-25. While it hit a new sales peak at 4.3 million, the growth was sluggish at just around 3 per cent, primarily due to the continuously declining sales of entry level cars... The entry-level car segment is in a bad shape, primarily due to two factors: higher price tag of Rs 4 lakh-plus due to better safety norms including six airbags, and sluggish income growth in the lower end of consumer base. The bigger problem is that an entry-level car costs nearly four times the prices of a scooter or motorcycle...

According to industry data, sales performance of entry-level cars priced below Rs 5 lakh – a crucial indicator of demand in the economy given that this segment largely attracts first-time buyers – is dire. This segment used to account for nearly a million units a decade ago – 9,34,538 to be precise in FY16. It has since declined to just 25,402 units in FY25. The Maruti Suzuki Alto, for instance, sold more than 18,700 units in June 2019, and was the best-selling then. In June 2025, the Alto and S-Presso combined sold a little over 6,000 units... The two-wheeler segment sales dropped 6.2 per cent to 46.74 lakh units in April-June 2025, pulled down by motorcycles and mopeds. When juxtaposed, suggests a dwindling of purchasing power at the lower and middle-class segments...

According to data collected by the NGO People Research on India’s Consumer Economy – which some carmakers refer to internally – car penetration in Indian households that have a yearly income of less than Rs 4 lakh reduced to 1.4 per cent in FY20, from 1.9 per cent in FY16. Car penetration in households that earn between Rs 4 lakh to Rs 7 lakh annually also reduced to 8.3 per cent from 12.1 per cent in the same time period. Families with incomes of less than Rs 4 lakh and between Rs 4 lakh and Rs 7 lakh are said to make up for around 80 per cent of all Indian households. Though FY20 was the latest data available with a carmaker, they said the trend has not changed in the subsequent years.

2. Cafes are another illustration of the lack of consumption depth in the Indian market.

Running a cafe in India is something that even the boldest players have struggled to perfect, even after decades. Mid-market physical coffee chains like Cafe Coffee Day have collapsed, premium brands like Starbucks are fighting an uphill battle, and artisanal chains like Blue Tokai are facing steady losses. The truth is nobody has cracked the profitability code. The challenges are easy to spot. India may be the world’s seventh-largest coffee producer, but its per capita coffee consumption stands at a minuscule 70g compared to the global average of 1.3kg. “The math simply doesn’t add up when you factor in rental costs, labour complexity, and consumer price sensitivity,” said Abhinav Mathur, CEO of Kaapi Machines, a firm that supplies and services high-quality coffee machines. Cafes cough up 15–20% of their sales as rent at prime locations. For instance, Starbucks reportedly pays Rs 25 lakh ($29,000) per month to operate in Mumbai’s prime spots. The company needs to sell over 500 cups a day just to break even on rent.
The unit economics of coffee making in India is brutal.
“Rent is what makes or breaks a cafe brand in India,” said Mathur. “For Starbucks, rent makes up about 15–20% of its revenue... Even Blue Tokai spends about 15% of its sales on rent, said Chitharanjan. This is “reasonable” for its business model, he said... The investment in equipment adds another layer of complexity to running a cafe. For instance, opening a 1,000-square-foot Blue Tokai outlet costs Rs 85 lakh–1 crore, said Chitharanjan. And espresso machines cost Rs 2.5–5 lakh, depending on whether it’s a semi-automatic or an automatic one... Moreover, Indian consumers have been conditioned by decades of affordable commodity coffee pricing. For instance, a traditional filter coffee in South India costs Rs 15–30, creating psychological barriers to premium pricing. “People find it culturally difficult to pay Rs 200 for coffee,” said Mathur.
As a result, every major chain in the country—from Cafe Coffee Day to Third Wave Coffee—is currently loss-making. For instance, Starbucks’ losses have gone up by more than 5X to Rs 136 crore in the two years to FY25. Similarly, Third Wave Coffee, a chain launched in 2016, posted losses of Rs 110 crore in FY24—almost double the previous year... Despite the industry’s growth, sustainable profitability remains elusive for most players. The successful brands have generally followed one of two strategies: premium positioning with high margins but limited scale (Blue Tokai, Third Wave)—still leading to losses, or ultra-low-cost operations with minimal infrastructure (delivery-only players like the now-struggling Zepto Cafe). 
Some comments on the article offer useful insights.
The psycographic-lifestyle-income gap between cafe coffee consumer and filter coffee consumer is very huge. So for any given locality (physical or qcomm) the market size has a unpenetratable celing. And that market that pays 200-400 for a coffee won’t be happy with just coffee – so the need for complex menus and costly ambiences. The tea shop culture is so broad based in India (which also offers filter coffee and instant coffee with snacks) – the cafe culture stands in isolation or should I say has painted itself in to a corner. So before entreprenuers study economics and business scaling, they should first study culture... These coffee chains expect American levels of coffee consumption when their prices are relatively 5-10x higher making it an extremely premium product. The average person in US spends between 0.1-0.2% of their monthly salary on a single cup of coffee (assuming $5 per coffee). Applying the same multiplier means a cup of coffee in india should not cost more than 50-100 rupees, far cry from the 250-400 being charged currently.

3. An assessment of the India-UK FTA here. 

4. As the IMF revises global (and US) growth rates upwards, Ruchir Sharma points to the problem with the models used by economists.

Many economists had assumed that, by lowering imports, tariffs would strengthen the dollar almost automatically, as an accounting identity. Instead, it suffered its worst fall over the first half of a year since the early 1970s. This unexpected turn is now attributed to the fact that the dollar started the year historically overvalued. Many foreigners were heavily exposed to dollar assets. Of late, they have been hedging those risks and investing more outside the US. Many countries are increasingly attractive places to park money, in part because tariff threats inspired them to push economic reform and cut trade deals with non-US partners. 

The bigger mystery is why the stagflationary impact of tariffs has yet to materialise in the aggregate data. Is the US really enjoying a free lunch, taking in $300bn a year in tariff revenues with none of the expected heartburn? By some estimates, foreign exporters are indeed absorbing 20 per cent of the costs — a much larger share than they did in response to tariffs in Trump’s first term. The remaining 80 per cent, however, is still getting paid in roughly equal shares by US corporations and consumers. The likely answer is that the negative economic effect of tariffs is being countered by other forces, including the mania for artificial intelligence and more government stimulus. Since January, estimates of what the big tech companies will spend this year on building out AI infrastructure have risen $60bn to $350bn. Smaller businesses are scrambling to catch the wave too, further boosting growth. And all this excitement is neutralising the fear that trade policy uncertainty would dampen animal spirits and freeze new capex. AI-driven bullishness is also lifting growth by keeping financial conditions loose, even with higher interest rates... Meanwhile, the promise of tax relief makes it easier for US corporations to absorb a larger than expected share of the tariff costs, rather than pass it all on to consumers. Trump’s “big, beautiful bill” is expected to save US businesses around $100bn this year and more than that in 2026, mainly in tax breaks.

5. Rama Bijapurkar makes an important point about the current Indian middle class. She writes that the older middle class was dominated by government jobs that offered decent salaries, job security, health care, pensions, etc. With government job recruitments slowing and formal large private sector jobs not compensating, the current middle class is far less secure. 

The majority will be in quasi-formal or quasi-informal small private company employment, small entrepreneurs with limited business scalability and ability to withstand environmental cycles, and self-employed gig workers with varying levels of skills and low levels of stability... They are exhausted from generating the energy needed to find meaningful work and navigate their way up the socio- economic ladder in the absence of facilitating structures. They are in search of white-collar respectability, stability, security, predictability, social mobility, recognition (which the old middle class had). Their holy grail, ironically, is a “government job”. Their deepest desire is a less exhausting life (lower aspiration levels, dreams that are “bonsai”), with little struggle and uncertainty. Is India’s famed aspirational middle class giving way to version next, the exhausted middle class? The stability and homogeneity we assume in the growing numbers of the middle class actually is a mass of heterogeneity and has inbuilt income and occupation volatility... Perhaps we should change our conceptual frame of a single middle class to a two tiered one – an economic development-driving “genuine” middle class that has the attributes discussed earlier; and a consuming capable class with purchasing power at the moment.

6. Art of the Deal in international trade diplomacy.

The president clearly has a winning formula for getting his way. First make shocking demands to stoke panic. Then pull back for time-limited negotiations. Having a mix of economically vulnerable, retaliation-shy, and pliable trade partners helps. Finally, strike an agreement below the initial threat level, and sell the result as a win-win.

7. Canada's prized export, maple syrup, 73% of its global output comes from there, is facing 35% Trump tariff. 

Over 45mn kilogrammes of Canadian maple syrup — enough to smother 3bn American pancakes — went across the border in 2024, amounting to almost 60 per cent of the country’s total demand... For years, syrup flowed freely across the border. But in 1909 US tariffs were imposed to protect American production. In 1972, when those tariffs were cut back to zero, the US Department of Agriculture released a research report which found that the maple tariff was “never very effective in protecting the domestic maple industry from foreign competition”. After this, Canada made its own efforts to protect the industry. In 1996, a maple syrup federation was created in Quebec — where 90 per cent of its syrup comes from. The cartel (known formally as the Quebec Maple Syrup Producers) sets a floor on global syrup prices and smooths out variable harvests. Once processed, Canadian maple syrup can sit in the federation’s enormous warehouses — which have 53 Olympic swimming pools’ worth of storage capacity — for years without degrading. The federation says that it any unsold inventory can be added to this strategic reserve. It also points out that it has made strides diversifying away from US buyers in recent years, reducing the proportion of production that goes there by roughly 20 percentage points over the last couple decades.

8. A snapshot of US imports and exports from India.

And why Trump thinks that India is the "tariff king".

9. Donald Trump on Jerome Powell in a graphic.
10. Good primer on Trump tariffs. This on industry-specific tariffs.
This is on the great walk back on China, whose tariffs are only slightly higher than India's and much lower than Brazil's.
11. The diminishing Palestinian state.
12. FT long read on how Eli Lilly's Mounjaro and Zepbound came from behind to overtake Novo Nordisk's Ozempic and Wegovy as the leading obesity drugs. 

13. Good graphic about the scale at which AI's consumption of computing power and electricity is growing.

14. Robin Harding points to two contrasting facts about the Japanese economy.
Number one: the yield on 30-year government bonds hit an all-time high of 3.21 per cent earlier this month after a series of weak auctions — a sign, perhaps, that markets are finally becoming concerned about the country’s enormous public debt. Number two: according to Morgan Stanley, Japan’s budget deficit was almost completely eliminated in the first quarter of this year, putting the public finances in their best position for almost three decades.

15.  Desalination of water is a rapidly growing industry. Global desalination industry is expected to exceed $20bn in 2027, from less than $15 bn in 2024. And annual growth in desalination capacity is 6-12%. Middle East and North Africa account for 70% of the global capacity.

16. Finally, the progression of Trump tariffs since April 2, 2025.

And their country-wise tariffs.

Saturday, May 3, 2025

Weekend reading links

1. Blackstone is Spain's biggest residential property landlord. 

Over the past decade, Blackstone has become Madrid’s largest private owner of residential real estate, and the second largest in all of Spain. Ms. Riquelme’s apartment is one of 13,000 that Blackstone currently owns in Madrid, and among 19,600 it owns nationwide. Across Spain, around 185,000 rental properties are now owned by large corporations, half of those by firms based in the United States, according to a review of property registries by the nonprofit Civio. Rental prices have increased 57 percent since 2015 and home prices 47 percent, according to PwC, in large part because the country has failed to build enough homes for its growing population, even as more than 4 million homes sit empty. After the pandemic pushed Spain’s unemployment rate up to 15 percent, evictions nationwide spiked. In Madrid, tenant groups estimate that 20,000 renters in the city currently face the threat of eviction.

Ms. Riquelme, a bookkeeper by trade, emigrated from Chile in 2000 and bought her apartment for 56,000 euros during the housing bubble, making mortgage payments to CaixaCatalunya, a now defunct bank. After she and her husband split, she could no longer keep up, and the bank eventually foreclosed. CaixaCatalunya sought €150,000 ($170,000) in fees and mortgage arrears, then sold her apartment at auction for just €40,000 ($45,000) to a subsidiary of Blackstone... Ms. Riquelme’s apartment was one of 400,000 private units across the country bought a decade ago by three American equity firms: Blackstone, Cerberus and Lone Star. Blackstone oversees at least 27 different domestic subsidiaries and investment funds in Spain that use a variety of models to buy both private and public housing. Some funds have focused on buying foreclosed residences, often converting entire buildings into short-term rentals. Others have scooped up public-housing units from cash-strapped city governments and then privatized them. Still more bought up homes as the government cleared its books of troubled assets after nationalizing several banks amid the Eurozone debt crisis...

For Blackstone, it was an expansion of a real estate plan that took root in the wake of the 2008 housing crash... In 2013, Madrid’s city government sold 5,000 public-housing units to Blackstone and to another American investment bank, Goldman Sachs. Blackstone bought 1,860 apartments in 18 complexes for €128.5 million ($146 million) — including hundreds of units in the PAU development in Carabanchel. That amounts to just €69,500 (about $78,000) per unit, on average. A court-mandated audit of the deal later revealed that the sales were made at well below market rates... These days, just 2 percent of Spanish homes available for rent are public housing, according to the Organization for Economic Cooperation and Development. In France it’s 14 percent; in the Netherlands it’s 34 percent.

2. The Chairman of Maruti Suzuki India Ltd (MSIL), the largest car maker in India, has said that car purchases in India are largely limited to the top 12% of households with an annual income of over Rs 12 lakh. MSIL reported a 4.3% year-on-year decline in net profit for Q4 FY 25. While overall passenger sales for 2024-25 grew by 2% to 4.3 million units, the sale of small cars declined by 9%. He said, 

“We have seen that in this current year, the sale of small cars (sedans and hatchbacks) has declined by about 9 per cent. So, if there is a 9 per cent decline in the car segment that is bought by 88 per cent of the people in this country, from where will you get the growth?” he added. Bhargava further noted that India has penetration of cars of just 34 of 1,000, “probably the lowest among any country around this area of the world”. “For a country that is growing, this PV sales growth rate of just 2-3 per cent a year is not going to increase the penetration of cars at all... especially because 2025-26... growth has been foreseen at 1-2 per cent.” The MSIL chairman expressed doubts on whether the major income tax relief, given by the Union government in the latest Budget, is going to boost small car sales in 2025-26.
“The cost of the car has gone up by an average of ₹80,000-90,000. How much cash will the income tax relief give? People are not going to put all the income tax savings aside and use it to buy a car. They have other priorities too. I mean, these are small households and they have many requirements. Their children have requirements. A car is not going to be the top requirement for these people,” he said. The small car segment has been declining over the past few years. In 2024-25, the Indian car industry sold 1.353 million sedans and hatchbacks, which was about 12.6 per cent lower year-on-year, according to Siam. Bhargava said it is a fallacy to think that the decline in the small car market and the growth of the SUV (sport utility vehicle) market is a result of people’s aspirations changing, and people wanting to buy big cars. “It's not true. What is happening is that people can’t afford small cars,” he added.

3. Is there a bond market "put" that's a boundary for President Trump's policies?
Nouriel Roubini, the economist, telling his clients that “traders [now] trump Trump”. Or, to put it another way, there now seems to be a bond market “put”, or a level of price swings that will force the White House to modify policy, at least verbally — probably around 4.5 per cent for 10-year yields.

4. The world of Trump in a graphic!

Adam Posen says
“China at present imports very few things from the US that it can’t get from others, including money. The US imports all kinds of things that we can’t get from anyone other than China at speed, or at affordable prices.”

Wonder why he does not ask where China will sell all its $300 bn odd goods that used to go to the US, and how those factories will remain open?

5. Robots are largely born in Asia. 

In June 1941, and in response to a proposal by the MIT engineer Vannevar Bush, Roosevelt established the Office of Scientific Research and Development. Bush was its head, reporting directly to the president. The results of its work — mass production of penicillin for battlefield wounded, proximity fuses that transformed anti-aircraft fire, and, not least, the Manhattan Project — made an unarguable case for the partnership between government and university-based research science... Largely forgotten now beyond histories of science, he was one of the 20th century’s most remarkable visionaries, not least for his conviction that peacetime federal governments had an obligation to fund basic scientific research, liberated from the demands of commercial profit...
Bush argued that since colleges were “the wellsprings of knowledge and understanding”, they should be parties to research contracts with the government that would provide the necessary stability of funding for sustained experimental work. This would guarantee the “free play of free intellects working on subjects of their own choice, in the manner dictated by their curiosity for exploration of the unknown”. The National Science Foundation, created by Congress and signed into law by President Harry S Truman in May 1950, owed much to Bush’s eloquence and vision.

7. The US Treasuries have not been a risk-free asset for several decades, as this graphic's volatility shows. 

This is a good long read on the US Treasury basis trades of hedge funds.  

8. Vietnam's problems in two graphics. China's share of its imports doubled to 32% between 2005-22. 
And in the same period, US share of its exports rose from 18% to 29.5%!
Vietnam's merchandise trade (imports plus exports) as a share of its GDP rose from 96% in 2000 to 158% in 2023!

But most economists agree that the decline in manufacturing jobs is mainly the result of rising productivity. New technologies have boosted output per worker, pushing down the relative price of manufactured goods. One study by Michael Hicks and Srikant Devaraj at Ball State University in Indiana estimated that 88% of the decline in manufacturing jobs in America between 2000 and 2010 can be attributed to productivity improvements. Trade accounted for only 13%.

Changing consumption patterns are also a factor. When incomes rise in poor countries, individuals tend to spend less on food and more on manufactured goods, a phenomenon known as Engel’s law. When incomes rise in rich countries, consumption shifts away from manufactured goods towards services. In 1950 goods accounted for around 60% of American consumption; today they represent just a third of spending with services accounting for two-thirds.

10. Some statistics on India's life and health insurance markets. 

Health and general insurance companies covered 572 million lives in FY24. The industry settled claims worth Rs 83,500 crore in FY24, up 17.7 per cent from FY23. It processed 26.8 million claims that year, up from 23.5 million the previous year, and 21.8 million in FY22. The stand-alone health insurance companies improved their claim ratio to 89 per cent in FY24, from 84 per cent in FY23. The industry had an agent network of 1.9 million and assets under management of Rs 4.75 trillion in FY24. There were 25 general insurance companies in FY24, including four public sector undertakings. The number of stand-alone health insurance companies was five. Overall, the non-life insurance penetration in India, which includes health insurance, is just 1 per cent of GDP. This includes health coverage by different government schemes. Globally, the US has the maximum non-life insurance penetration (9.3 per cent), followed by the Netherlands (7.2 per cent), Canada (4.7 per cent), Germany (3.4 per cent), and Australia (3.3 per cent). Insurance penetration is measured as the percentage of insurance premium to gross domestic product (GDP)... 

Medical inflation was 14 per cent in FY24, the highest in Asia... the growth rate in health insurance dropped in FY25 to 8.98 per cent from 20.25 per cent in the previous year, with the gross premium income of insurers at Rs 1.18 trillion against Rs 1.08 trillion in FY24... The stand-alone health insurance industry operated on around a 3.5 per cent profit margin in 2023-24 (FY24). For the overall general insurance industry, it’s slightly higher. The private general insurers enjoy a much higher margin; the public sector players much lower. The average margin for hospitals could be at least 30 per cent.
Some China-based firms hit hard by US tariffs are reaching out to Indian exporters to fill orders on their behalf and help them retain their American customers as they navigate a trade war causing seismic shocks in global commerce. At the Canton Fair that runs through May 5 in Guangzhou — the world’s biggest trade fair — several Indian firms were approached by Chinese companies to supply goods to their US customers... In return for the sales, the Indian firms would pay a commission to the Chinese businesses... Indian firms at the Canton Fair were instead approached to supply goods to US companies under the brands of the Chinese firms, or co-branded with the Indian firms... Most of the queries came in sectors like hand tools, electronics and home appliances... The commission paid to the Chinese firms would be negotiated between the buyers and suppliers.

12. India healthcare facts of the day.

India’s out-of-pocket expenditure (OOPE), as a percentage of total health expenditure (THE), declined from 62.6 per cent in 2014-15 to 48.2 per cent in 2018-19, the year when Ayushman Bharat was launched. Since then, it has dropped down further to 39.4 per cent in 2021-22. Such reduction in OOPE has gone hand-in-hand with increased public spending in healthcare from 29 per cent of THE in 2014-15 to 48 per cent in 2021-22.

Over half of those admitted in the Ayushman Bharat authorised hospitals for treatment under the scheme were above 45 years.

90% of the 36,118 empanelled hospitals have less than 50 beds. 

13. Good article that brings out the issues likely in the India-US FTA negotiations. Important point that the value add in India on an iPhone retailing for $1000 is less than $25, compared to $450 captured by the US. 

14. FT graphics on 100 days of Trump. 
Market reactions and electoral support will likely be the two restraining forces on Trump. His pause on reciprocal tariffs in reaction to the Treasury market convulsions is definitive evidence. The stock market performance in the first 100 days of Trump has been the worst in five decades!

15. World trade facts of the day
Between 1995 and 2023, world trade (goods and commercial services) registered strong growth, averaging 5.8 per cent per year, resulting in almost a fivefold increase... (it) outpaced growth in global gross domestic product (GDP), which increased by an average of 4.4 per cent per year over the same period. The global trade-to-GDP ratio showed a significant upward trend, rising from 20 per cent in 1995 to 31 per cent in 2022.

16. Finally, the collapse of the Spanish and Portuguese electricity grids is a stark reminder of the challenges with electricity grid management once intermittent renewables assume a high share of the energy mix.  

At 12.33pm local time on Monday, the frequency on Spain’s electricity grid suddenly dropped, from the 50 hertz level at which the grid’s operator tries to maintain it, to 49 hertz, according to Aurora Energy Research, a consultancy. A move bigger than 0.1 hertz forces many power stations to automatically switch off for safety reasons. Any loss of power in Spain has an immediate knock-on effect in Portugal, which relies heavily on its neighbour for electricity supplies... Frequency fluctuations are not uncommon, but grid operators normally overcome them by asking power generators to increase or decrease their output, or by using batteries. However, in this case, not enough additional generation capacity could be brought online fast enough...

Renewables are weather-dependent, but solar panels lack the big turbines that can help keep the system running if there is a power failure somewhere along the line — a process known as “inertia”. About a fifth of Spain’s annual electricity supply comes from solar, on average, but at lunchtime on Monday the proportion was far higher — at more than 55 per cent. Aurora said the lack of inertia “contributed to the instability”... Greater use of batteries, as well as cables that import and export power to other countries, can also help balance out intermittent supplies. Spain’s relatively poor connection with France has long been a source of complaint in Madrid.

In fact, it's reported that of the scheduled 26 GW of electricity supply on Monday, just 5 GW came from non-intermittent sources.

Friday, April 18, 2025

Weekend reading links

The basis trade focuses on the price difference between Treasury bonds and futures contracts tied to those same bonds. Sometimes the price of a bond futures contract rises above the underlying bond price because of heavy futures purchasing by pension funds, insurance companies and other institutional investors. These asset managers often prefer to buy bond futures instead of the bonds themselves because futures require less cash upfront. To take advantage of the price discrepancy, a hedge fund will sell Treasury futures and simultaneously buy the corresponding lower-price bonds. By buying cheaper bonds in one market and selling expensive ones in the other, traders can profit from the small price differences, whether bond prices go up or down. 

The profit from these price differences is so tiny — as little as a small fraction of a penny — that traders typically borrow a lot of cash to multiply their bets. What makes this strategy risky is the combination of hedge funds’ heavy borrowing to execute the trades — as much as $50 borrowed for every $1 of their own capital that they’re investing — and a heavy reliance on short-term borrowing in particular. US Treasury bonds are normally considered low-risk investments because they are backed by the full faith and credit of the US government. But a sudden disruption to financial markets could cause short-term borrowing costs to skyrocket. When that happens, hedge funds are forced to repay the loans and dump Treasuries to unwind the basis trade. That could cause Treasury markets to seize up, and the resulting higher bond yields could ripple through the financial markets, raising the cost of everything from corporate borrowing to home mortgages.

2. Three graphics that capture the challenges that the US will face in rapid decoupling from China. This shows the US dependency on imports from China.

This shows the high level of dependency on China for electronics.
Abrupt decoupling will be painful.

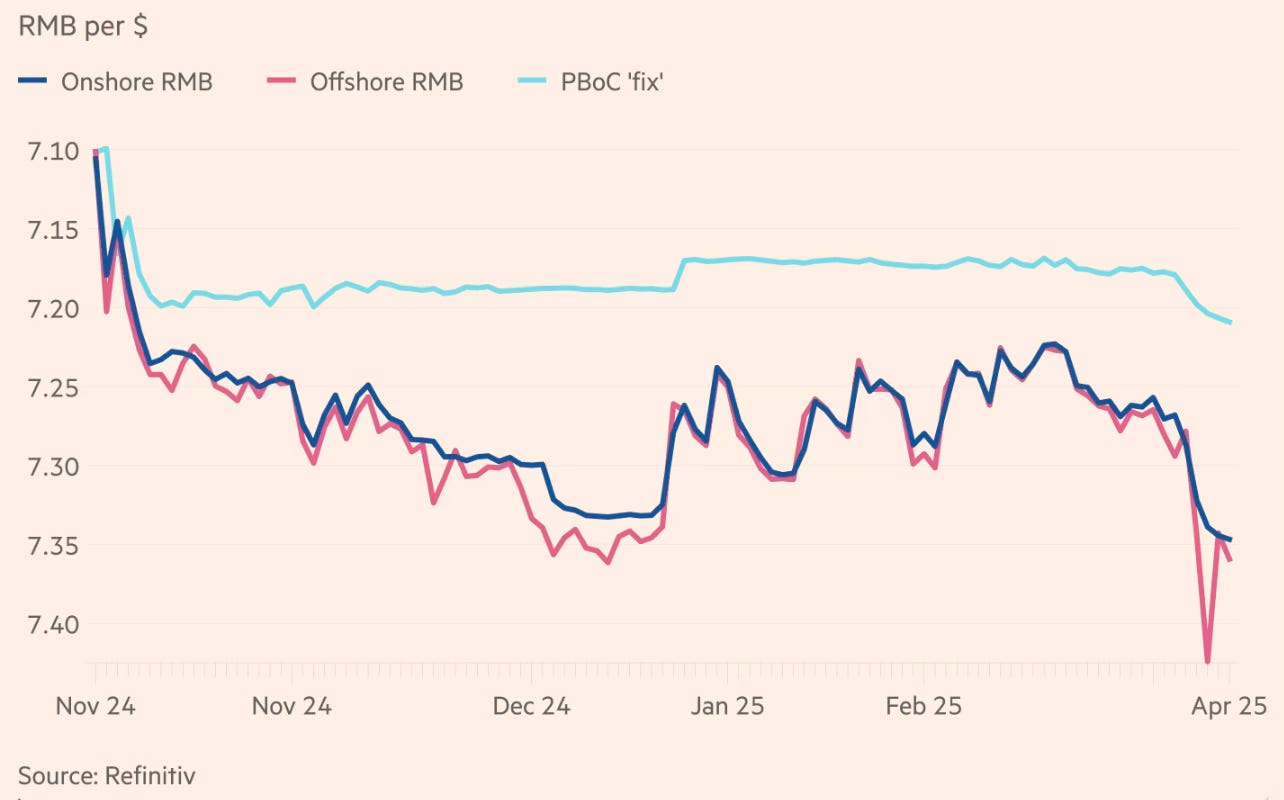
3. China has responded to the Trump tariffs with its tit-for-tat retaliatory tariffs. Apart from this, it has also opened the door on exchange rate response, allowing the renminbi to weaken against the dollar. The offshore renminbi has hit a 18-year low. The onshore renminbi is subjected to a band that restricts moves beyond 2% per day. 

4. Meanwhile, Stephen Miran has expanded on his proposal for an accord with trade partners where they agree to pay for the US security umbrella and access to the large US domestic market. He has outlined five options available with other countries for burden sharing. 

First, other countries can accept tariffs on their exports to the United States without retaliation, providing revenue to the U.S. Treasury to finance public goods provision. Critically, retaliation will exacerbate rather than improve the distribution of burdens and make it even more difficult for us to finance global public goods.

Second, they can stop unfair and harmful trading practices by opening their markets and buying more from America;

Third, they can boost defense spending and procurement from the U.S., buying more U.S.-made goods, and taking strain off our servicemembers and creating jobs here;

Fourth, they can invest in and install factories in America. They won’t face tariffs if they make their stuff in this country;

Fifth, they could simply write checks to Treasury that help us finance global public goods.

5. Michael Moritz makes some important points on the basis of China's manufacturing prowess.

Since the 1970s, China and countries in south-east Asia have perfected a formidable triple axle comprised of the command of raw materials, mastery of component manufacturing and packaging, and now — by dint of drive, creativity and a formidably well-educated cadre of scientists and engineers — an array of products that put the west to shame. Just look at the manufacturing knowhow of Foxconn and TSMC and the product line-up of companies such as Huawei, BYD and Xiaomi — the last of which is only 15 years old. They are enough to make Americans weep. And that’s before you calculate the size of their workforces or contemplate that about 450,000 cars were built in China in 1987 compared with 31mn in 2024.

6. Italian cheese facts of the day

The US imported €7.8bn worth of Italian cheese, olive oil, wines and other delicacies last year... parmesan cheese... is produced in regulated quantities in Italy’s Emilia-Romagna region. Producers there must adhere to 17-pages of strict rules that even dictate what cows can eat — and where their fodder is grown. The Parmigiano-Reggiano consortium allocates coveted cheese quotas to local dairies, polices the process and has to certify cheese as genuine and up to standard.

7. Important graphic on Indian middle class incomes.

8. India's manufacturing is a very big outlier in declining as the economy grows. 


9. Wall Street is also worried because the Trump trade wars may deal a fatal blow to the march of American financial institutions. 
For the past 15 years, the big US banks and money managers have been on the march... Goldman Sachs, JPMorgan, Morgan Stanley and Bank of America each captured at least 5 per cent of last year’s global investment banking fees. The top European bank, Barclays, pulled in just 3.3 per cent... In some quarters, BlackRock has recorded more inflows than the entire European asset management industry combined. Americans also dominate the custody market, holding four of the top five slots. All of them benefited from a vibrant US economy, deep capital markets, and the fundamental appeal of American equities and bonds to international buyers... 

But just when American finance was looking unstoppable, Trump pulled out the rug. His aggressive “liberation day” tariffs, followed by a partial 90-day pause, sent the markets into a tizzy. Other belligerent policies, including threats by his advisers to weaponise finance, are forcing overseas companies and governments to question their dependence on US financial institutions and their use of Treasuries as a standard risk-free asset. Foreign firms are reconsidering their US ties, looking for local service providers and making contingency plans to issue debt in home currencies rather than the now-less stable dollar. Governments are shedding their laissez-faire attitude to US dominance in technology and banking... The lack of European alternatives to Google, Microsoft and the like make it hard to reduce dependence on US technology, but financial services are a different story. European banks are not as big or as globally feared as the Wall Street beasts, but their top employees are experts at raising funds and closing mergers. Even before Trump set world markets on fire, Swiss lawmakers had raised concerns about the wisdom of using a US bank as custodian for SFr46bn in social security funds.
10. One more article on how the US is more dependent on China than the other way round, harping on the substitutability of US agricultural exports compared to the Chinese technology exports.

While the exposures may be so, there's so little discussion on the  job losses for the 10-20 million Chinese workers who are exposed to US-bound exports, whose re-routing will be extremely challenging in this hostile environment of protectionism globally. 

The one thing that the Chinese have a clear upper hand is in that the trade wars will most likely galvanise the country into becoming united despite the suffering to fight the US, a sentiment that's unlikely with the US.

11. The first quarter of 2025 economic data from China has some interesting insights. The headline growth of 5.4% has a good share of front-loaded exports to beat the Trump tariffs. This is reflected in the 12.4% rise in exports in Match. Disturbingly, industrial production and fixed investment rose sharply in March reflecting the continued expansion of manufacturing capacity, even as imports fell 4.3% for the the month. 

12. As we rail at China, it's an opportune moment for everyone to reflect on how they have been complicit in allowing China to become so dominant in manufacturing, none more so than the US.

China shook the world in 2010 when it imposed an embargo on exports of crucial rare earth metals to Japan... The embargo, prompted by a territorial dispute, lasted only seven weeks... When the embargo was over, China took forceful control of its mineral bounty... and consolidated the industry under state control... The mines were later nationalized and consolidated into a single state-run company, China Rare Earth Group... The world was put on notice, especially Japan and the United States, two of China’s biggest customers for rare earth metals used in everything from cars to smartphones to missiles. Governments from both countries drafted detailed plans for how to mitigate their dependence on China. Japan has largely followed through on its plans and today can source the minerals from Australia. Not the United States. Even after 15 years, the country is still almost entirely reliant on China for the processing of rare earth metals. As a result, American automakers, aerospace companies and defense contractors have been left vulnerable.

Angry about President Trump’s tariffs, China has suspended all exports of certain rare earths, as well as the even more valuable magnets made from them. These small yet powerful magnets — no bigger than a ring for a person’s finger, yet with 15 times the force of a conventional iron magnet — are an inexpensive and often overlooked component of electric motors. They are used in electric and gasoline-powered cars as well as robots, drones, offshore wind turbines, missiles, fighter jets and many other products... China now produces 90 percent of the world’s magnets. Further construction was underway at two of Ganzhou’s largest magnet factories last week...

China’s top leader, Xi Jinping, said in a speech in 2020 that it was important for China’s national security that the West’s supply chains remain dependent on his country. “We must build up our strengths and consolidate our international lead in industries where we have an advantage,” he said a few months after visiting Ganzhou’s most advanced magnet factory. He called for “intensifying the dependence of international industrial supply chains on China, forming a powerful capacity to counter and deter deliberate supply cutoffs by foreigners.”

More on rare earths and China's dominance

China dominates the mining and processing of rare earths, a collection of 17 elements that are essential to the auto, semiconductor, aerospace and defense industries. While abundant in the Earth’s crust, they are difficult to extract and separate, and the United States and other Western nations have largely left the work to China. For some critical “heavy” rare earths — named because they have higher atomic numbers on the periodic table — China is essentially the only country that can separate and process them. Rare earths have become so coveted because they help make the powerful magnets needed for new cars, missiles and drones. While “light” rare earths make up far more of those magnets, heavy rare earths are also needed to keep the magnets from weakening or being destroyed at high temperatures. Heavy rare earths have overwhelmingly come from mines in China and Myanmar, which has sold its output to its powerful neighbor, because those countries have natural clay deposits rich in the elements.

Japan has been alert to the dependence on China for critical minerals and has responded strategically. In response to export controls imposed by Beijing in 2010, Japanese companies and government agencies stockpiled these minerals and developed alternative sources, cutting their dependency on China from 90% to 58%. 

13. Talk of cutting the branch on which you are sitting, the case of Trump tariffs on Lesotho.

Lesotho is the largest African garments exporter to the US and a rare success story born out of Washington’s 25-year-old African Growth and Opportunity Act (Agoa), introduced under then-president Bill Clinton to offer tariff-free access to the world’s poorest continent. All that is now at stake... the US president has threatened to impose on Lesotho, one of the highest rates on any country. At $240mn of exports, Lesotho accounts for less than 0.02 per cent of the US’s trade deficit. Yet even without Trump’s higher “reciprocal” tariffs, which have now been paused for 90 days, executives and officials say the new blanket tariff rate of 10 per cent could still destroy an industry built on razor-thin margins and the US’s own decades-old trade policy. The duties “make a mockery of Agoa, which was intended to help developing economies grow”, said Nkopane Monyane, a businessman and former ambassador who for years ran a major garment factory... 

Faced with catastrophic economic consequences, Lesotho has been forced to join the queue of countries seeking to appease Trump with economic concessions... Lesotho this week granted Trump adviser Elon Musk’s Starlink a 10-year operating licence... foreign minister Lejone Mpotjoane also offered to greenlight the construction of a Marriott hotel and consider importing corn and wheat from the US. Lesotho is also considering accepting third country national deportees from the US and deploying soldiers to protect US companies in mineral-rich DR Congo...

In 2002, following Agoa’s implementation, more Asian investors saw an opportunity to use their knowhow and global garment connections to tap the pact’s benefits. Taiwanese multinational Nien Hsing, which also runs operations in Mexico and Vietnam, built its largest operation in Lesotho, where it makes some 600,000 units of clothing monthly for brands including Levi’s. A fifth of its exports go to neighbouring South Africa, while the rest is US-bound. The apparel sector is the southern African country’s biggest private sector employer, with 30,000 direct jobs and tens of thousands more people working indirectly, according to the country’s main business chamber. The reams of cotton being stretched, cut and sewn at Nien Hsing’s factory are a testament to the global nature of the business: cotton sourced from Egypt and West Africa is spun into denim, which then travels to South African ports before landing in the US.

14. Importance of the dollar, or the "burden of being the reserve currency" as per the Trump administration. 

Nowadays, the US only accounts for about a quarter of the global economy, but more than 57 per cent of the world’s official foreign currency reserves are in dollars, according to the IMF... There are many other pots of sovereign and quasi-sovereign money that are not captured by the IMF’s data on foreign exchange reserves, and whether you are a bank in Mongolia, a pension plan in Chile, a European insurance group or a Singaporean hedge fund, dollars are the ultimate reserve asset. The dollar is equally central in trade, with 54 per cent of all export invoices denominated in dollars, according to the Atlantic Council. In finance, its dominance is even more total. About 60 per cent of all international loans and deposits are denominated in dollars, and 70 per cent of international bond issuance. In foreign exchange, 88 per cent of all transactions involve the dollar. Even physical US bank notes are widely held abroad, thanks to the dollar’s broad acceptance. In fact, about half of the more than $2tn worth of US bank notes in issue are held by foreigners, according to the Federal Reserve. This enormous international demand for dollars translates into an embedded premium to US assets and means that the US borrows more cheaply than it would otherwise do — what France’s former president, Valéry Giscard d’Estaing, once famously referred to as America’s “exorbitant privilege”. It also gives the US the power to sabotage another country’s financial system through sanctions.

The effect of the Trump tariffs

Last week the DXY dollar index — which measures the strength of the currency against a basket of its biggest peers — fell 2.8 per cent. This was its seventh-worst week in the past three decades. It has kept dipping this week, extending its 2025 decline to 8.2 per cent... Most notably, the dollar has been particularly weak against other “haven” currencies that typically strengthen when markets are turbulent, such as the Swiss franc and the Japanese yen, and against gold. That the greenback is seemingly being excluded from this select club of currencies is a shocking development to many analysts and investors.

But there are no alternative to the dollar and it's still far from its lows. Despite the April declines, the DXY dollar index is 12% higher than it was its lows in 2020 and 40% over its lowest in early 2008. 

15. Alan Beatie points to the incentive distortions facing US car manufacturers. The US production of light-trucks, including poc

The EU import duty on standard cars such as hatchbacks and minivans is indeed 10 per cent versus the US’s 2.5 per cent. But the US production of light trucks, including pick-ups, has long sheltered behind a 25 per cent tariff wall. The duty is known as the “chicken tax” after Lyndon B Johnson imposed it in 1964 in retaliation for European levies on American poultry. Industry experts say the Big Three car companies in Detroit — Ford, General Motors and Chrysler (now part of the Stellantis group) — have accordingly increasingly focused their innovation on making pick-up trucks and used the same platforms and components to develop gas-guzzling large sport utility vehicles (SUVs). Felipe Munoz, senior analyst at the market intelligence company Jato Dynamics, told me that while pick-ups and heavy SUVs were only 17 per cent of US light vehicle sales, “it’s where the Big Three US manufacturers make most of their money in the American market”. The rest of the world, however, tends to have narrower roads and higher fuel taxes than the US. “The protection has made the US car manufacturers less competitive globally,” Munoz told me. Japanese companies make family cars popular around the world: Detroit does not... It’s not EU protectionism that hurts American carmakers abroad. The European Commission has long had an open offer to the US to cut all industrial goods tariffs including cars to nil, which the US has failed to take up.

16. OpenAI facts of the day

No other company has ever built a consumer internet empire so fast. It took Google 13 years to reach 1bn users, while Facebook reached the same milestone in eight. Thanks to the viral success of ChatGPT, OpenAI looks on track to get there in three... chief executive Sam Altman said last week that its audience had doubled in a matter of weeks and now comprises a tenth of the world’s population. This is mind-boggling — ChatGPT only passed 200mn weekly visitors last August. Rapid growth has left the company little time to address some of the most fundamental questions for any consumer internet company.

17. Semiconductor chip supply chain 

Those supply chains cross so many borders that “no one [country] is self sufficient — not even close,” Chris Miller, a Tufts professor, added, noting that while Japan dominates the wafer business (with a 56 per cent market share), the US has a 96 per cent share in electronic design automation software and Taiwan controls more than 95 per cent of advanced chipmaking. Meanwhile, China processes more than 90 per cent of many critical minerals and magnets needed to make digital goods.