Substack

Showing posts with label Regulation. Show all posts

Wednesday, October 21, 2026

A framework for deregulation in the Indian bureaucracy

I have blogged on the issue of deregulation as an organisational culture earlier. This post is an attempt to provide a framework for thinking about the bias within the Indian bureaucracy towards the prevention of inclusion errors and process abuse. 

Two features of India’s bureaucracy are of relevance. 

One, a welfare policy to support the needy and a promotional policy to incentivise something, comes filled with access barriers. Two, a regulatory policy to permit or regulate something comes tightly prescribed. 

In the former, there is a reflex within the bureaucracy to prioritise waste/leak/abuse avoidance over inclusion, whereas in the latter, there is a tendency to over-prescribe so as to limit abuse even if it inconveniences genuine applicants. This is the rational choice arising from the institutional incentives. 
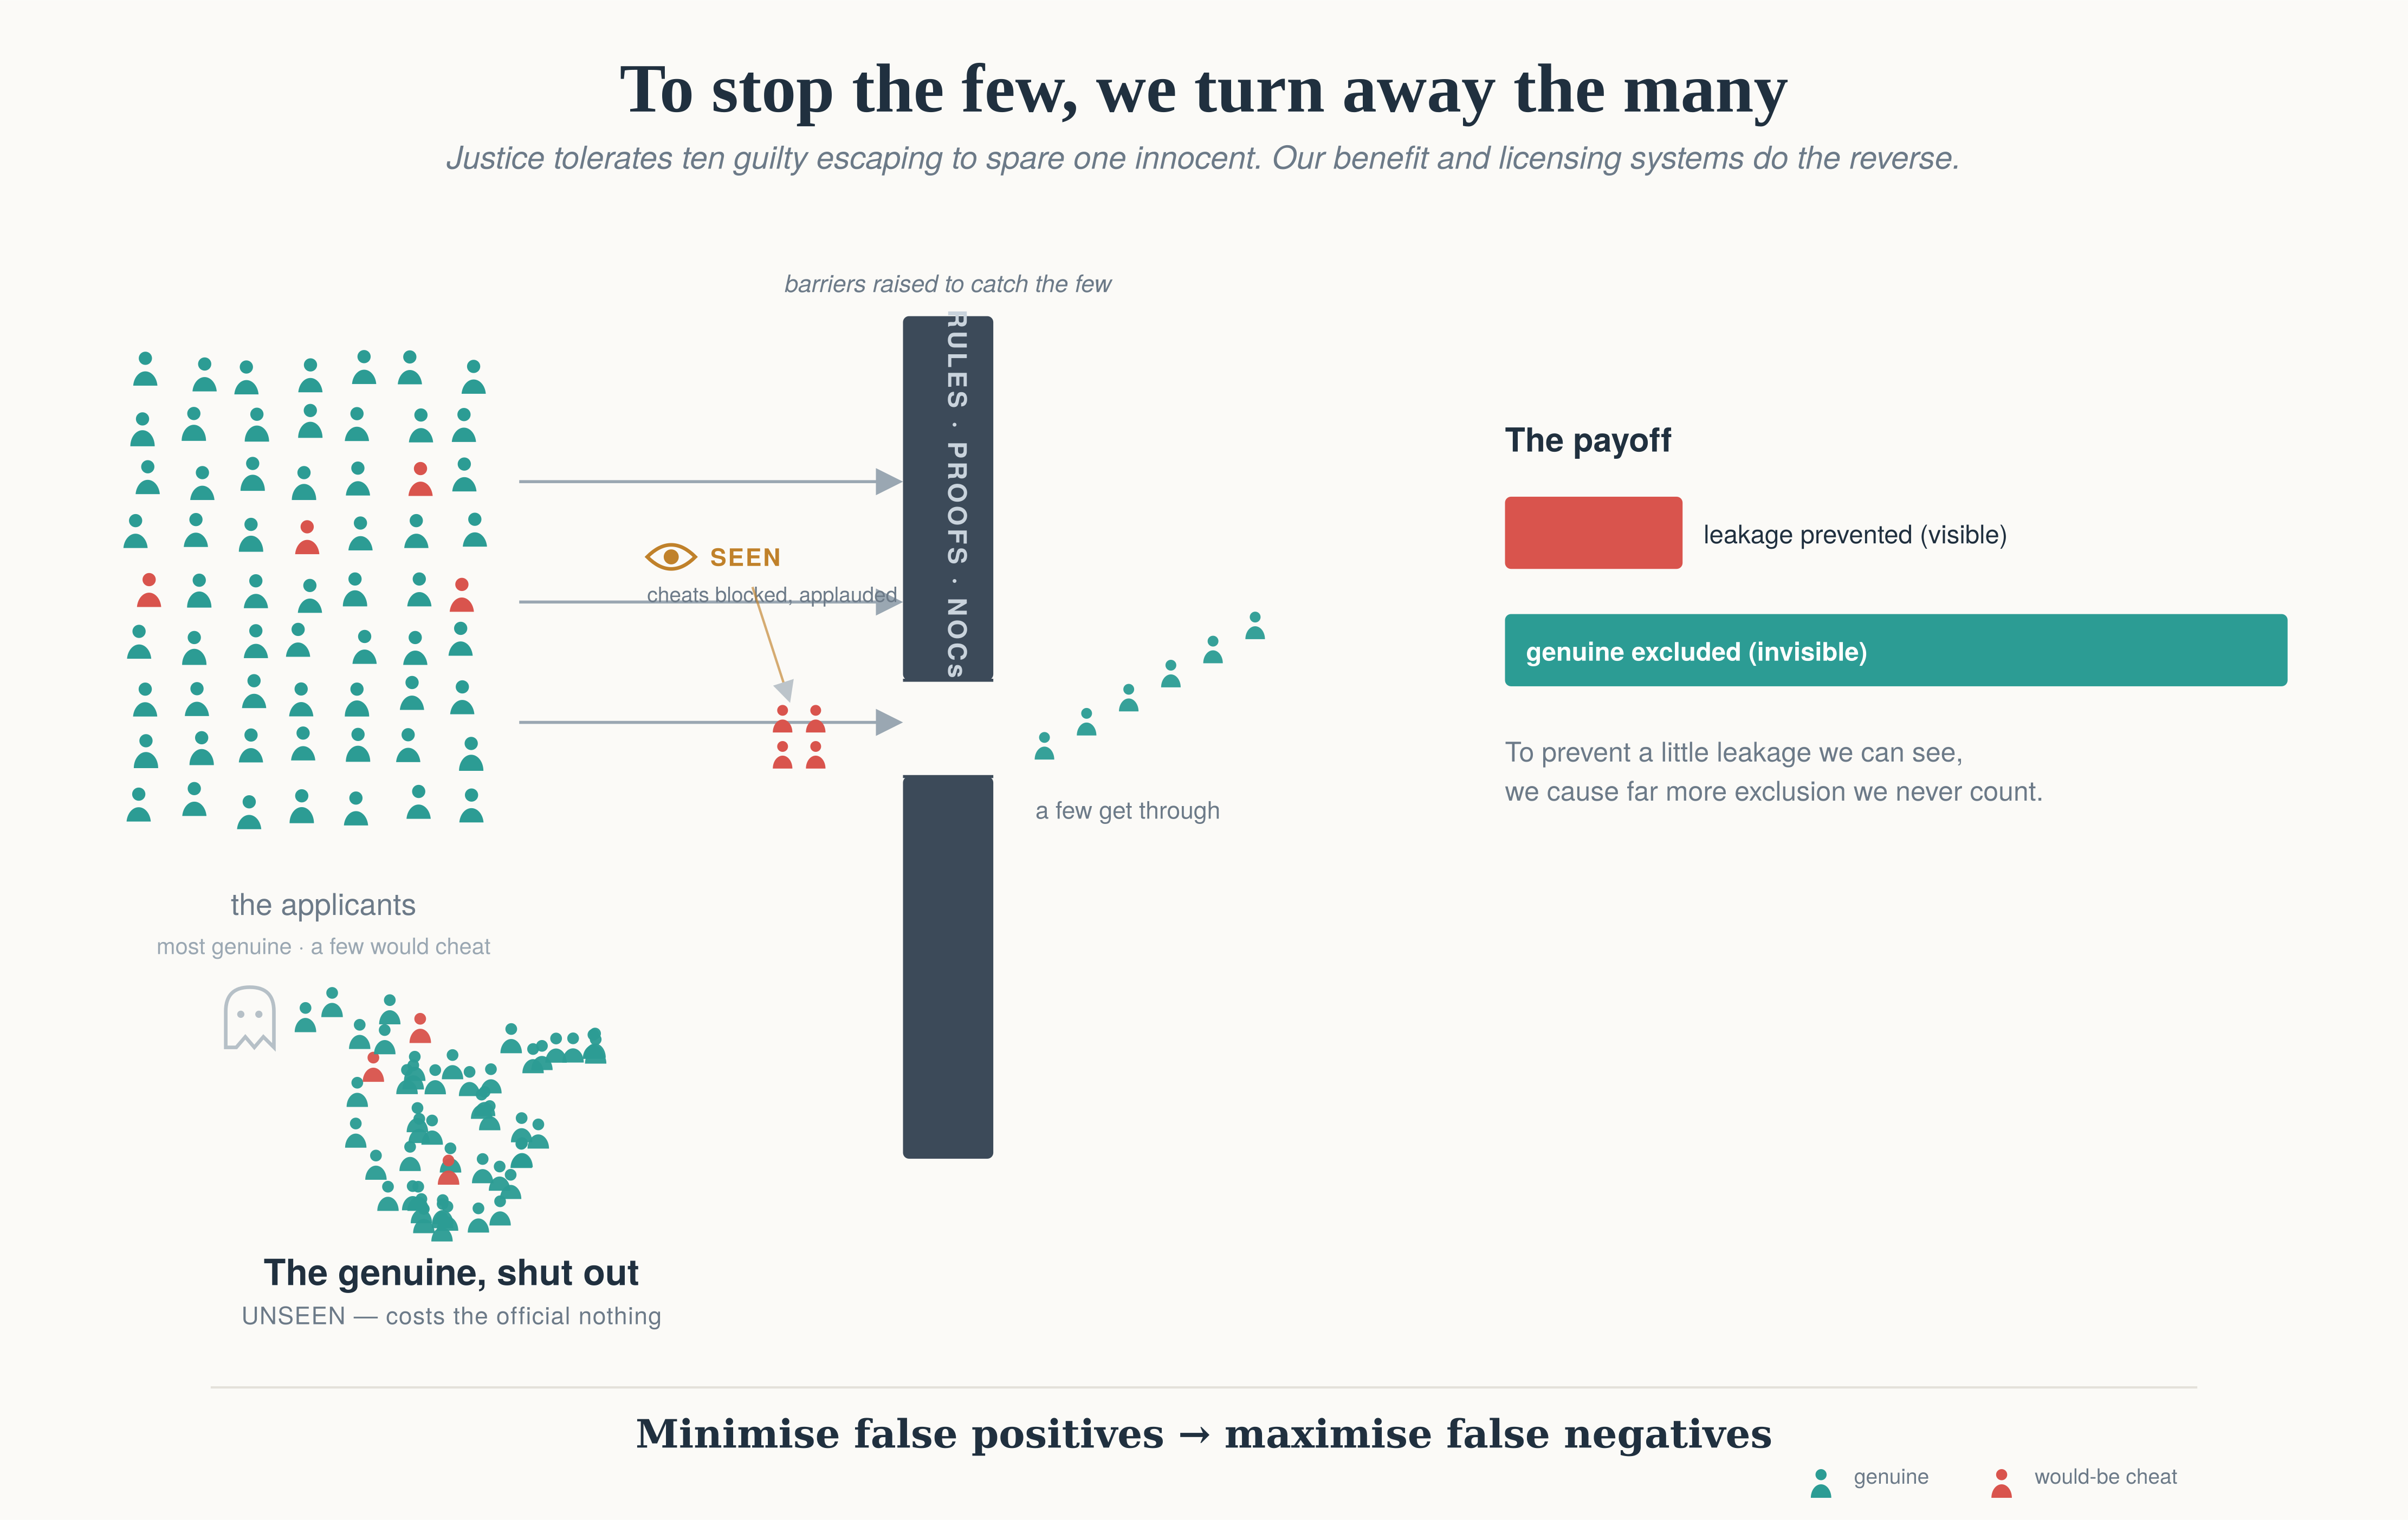
In both cases, the precautionary effort detracts from the realisation of the primary objective. The pursuit of the ineligible (the false positive or the Type I error) comes at the exclusion or harassment of the eligible (the false negative or the Type II error). 

All bureaucracies are prone to this precautionary bias. The clearest exemplar of this bureaucratic bias is cited in the oft-cited paper on regulatory economics concerning the invisible graveyard in the US FDA’s drug approvals process. The works of Sam Peltzman, Henry Miller, and Alex Tabarrok have shown that a drug regulator treats approving a harmful drug (visible deaths, Congressional hearings) as catastrophic and not approving a beneficial drug (invisible deaths among those who never got it) as costless, so it errs massively toward over-caution. Studies have estimated the ratio of Type II (delay) cost to Type I (bad-approval) cost in the thousands to one.

However, there are compelling reasons to argue that this bias is excessive in the Indian bureaucracy. 

Root cause reforms aimed at deregulation should target this bias and not be confined tojust one-off changes to existing regulations. I blogged here and here on this issue. 

There is an important contrast on this with the judiciary. There, the norm of the Blackstone ratio deliberately and explicitly instills that it is better to let ten guilty escape than allow one to suffer. The bureaucracy needs its equivalent norm. 

As a conceptual framework to understand it, there are perhaps three drivers within the Indian bureaucracy of this bias.

1. The false positive is salient when detected, whereas the false negative is always a silent counterfactual. Even the oversight mechanisms focus on detecting and pursuing the false positives, while invariably staying silent on the false negatives. In public debates, too, media stories play up the false positives while largely overlooking the false negatives. 

2. The bureaucrat gets personally hauled up in the case of a false positive that comes to light. Even if honest mistakes are safeguarded now, and they are finally exonerated, the public scrutiny and process harassment is a worse punishment.

3. The bureaucratic approvals process, especially the finance department concurrence (and also legal and personnel department concurrences), focuses far more on the false negative and mitigating them than on the efficiency and effectiveness of the achievement of its objectives. 

These three drivers must be seen against the backdrop of a system with a very high level of trust deficit between the government and the beneficiaries (in the case of welfare and promotional policies) and the regulated (in the case of regulatory policies). In the Douglass-North sense, there is a low-trust institutional equilibrium inherited from the colonial control-state, which has hardened into a shared prior (“the applicant is a cheat”) and a norm (“process compliance is safety”). 

There is also the historical inheritance of the colonial guardian bureaucracy built to maintain order and extract revenue, standing above and apart from the governed, and which elevates procedural purity over substantive correctness. At a social and political level, there is a stigmatisation of private benefit and a valorisation of public gain, which often views the two in binary zero-sum game terms. There is a widespread chalta hai (it’s alright) attitude that condones such delays, hassles, and exclusions, and does not provide credible enough channels to provide feedback and redress them. Finally, I am not sure whether ease of doing business and ease of living are yet the kind of electoral goods that generally force real, actual changes. 

In contrast, the development trajectories of today’s advanced countries and China involved deliberate trade-offs that erred on the side of inclusion and lowering transaction costs. The regulatory excess in the US (captured in the so-called “everything bagel liberalism”) and the precautionary principles in the EU are more modern trends that emerged well after these countries reached their developed country status. 

In contrast, the development trajectories of today’s advanced countries and China involve deliberate trade-offs that straddle a fine line between enabling and abuse. The regulatory excess in the US (captured in the discourse of everything bagel liberalism) and the precautionary principles in the EU are more modern trends that emerged well after these countries reached their developed country status. 

As an analytical framework, the public loss function is to minimise social welfare loss by minimising inclusion and exclusion errors and compliance costs. The social optimum is when the marginal reduction in leakages and abuse is equal to the marginal increase in inclusion or convenience. Since abuse is generally rare and genuine cases are the overwhelming majority, the social optimum requires tolerating some leakage. 

However, this public loss function comes up against the official’s private loss function. The aforesaid reasons amplify an accountability multiplier that forces his/her private loss function to minimise inclusions and abuse, even at the cost of exclusions and compliance costs. 

The asymmetricity or gap between the two loss functions is the distrust wedge, the gap between the procedural strictness that the society would choose and the strictness that the incentive structure would produce. 
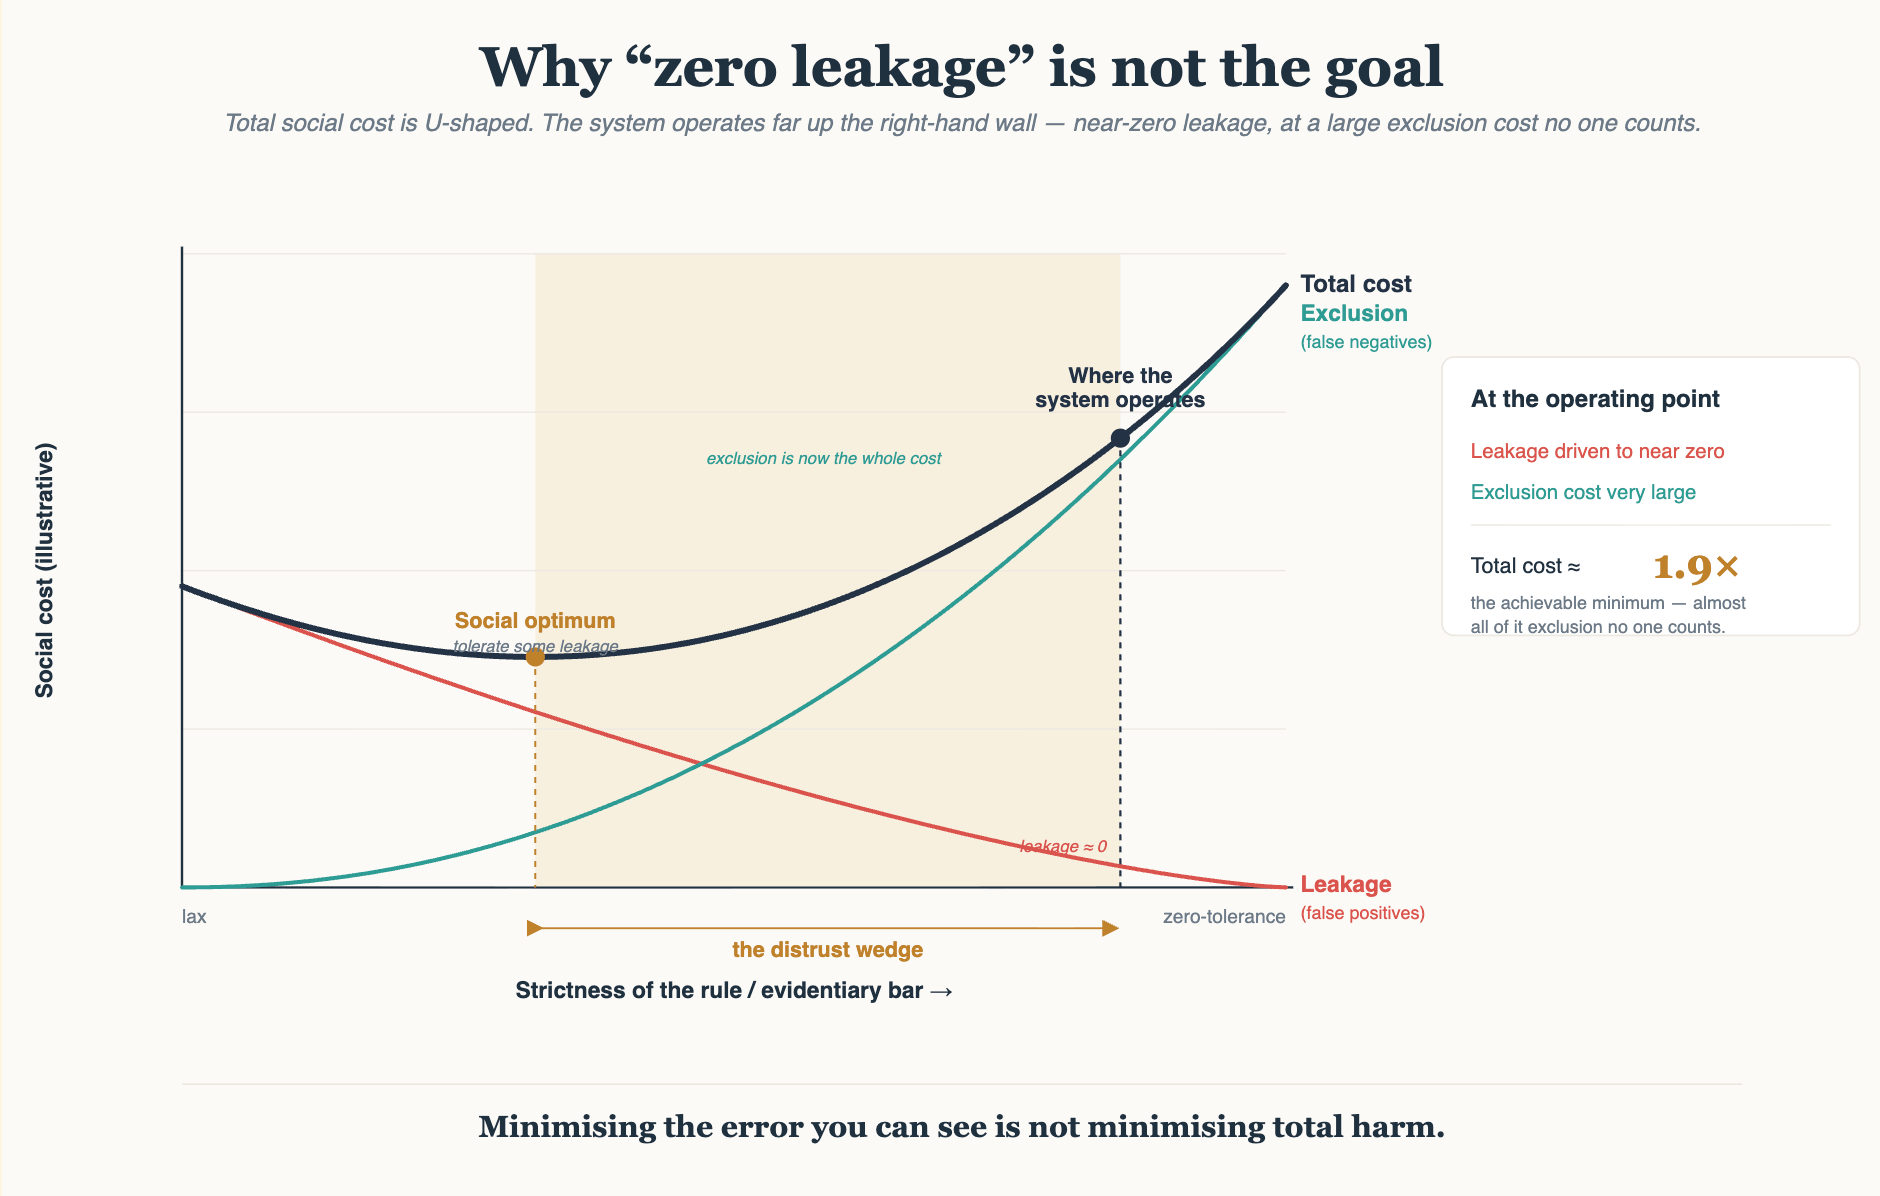
Any remedy to address the root cause of the problem should revolve around shrinking the wedge, either by lowering the accountability multiplier (stop over-punishing honest false positives), making exclusion and compliance costs visible and costly, or lowering the compliance costs. 

It is about internalising the implied shadow price of avoiding abuse or leakage. How many units of genuine exclusion or compliance cost is the system willing to incur to prevent one unit of abuse or leakage? This is the marginal trade-off that serious deregulation policy must target. There must be an institutional ownership (and bearing of the associated costs) of the cost of exclusion and harassment. 

So, in terms of possible solutions, here are a few suggestions.

Efforts to change deeply entrenched norms and behaviours are complex endeavours. They are collective social and political choices that get adopted by the bureaucracy as strong and salient organisational narratives. They are best and most effectively done when they are done directly to change beliefs, norms, and behaviours. 

The Indian state has generally struggled when it comes to instilling values to change collective behaviours. 

It does better with specific interventions. But there is a risk in reducing such efforts to technical measures. The Ease of Doing Business ranking is a salutary example of the form taking over the substance and subverting the objective. 

Nevertheless, the three-point conceptual framework articulated earlier can be the baseline for reforms. 

The single highest-value and genuine root-cause fix to the problem is to make exclusion visible and costly. It is useful to have an institution, ideally within the Department (even with all the flaws or conflicts of interest), or one like the NITI Aayog, entrusted with the task of capturing/quantifying and updating the exclusion and compliance costs (the false negatives). This would include the publication of exclusion/rejection/non-uptake rates and median clearance times for every benefit and licence, by geography and office, as standard MIS. To also provide perspective, these metrics can be posted against some desirable benchmarks. This may be done for a prioritised set of activities for certain departments. 

This may be an essential requirement to foster a culture that evaluates public services also in terms of their false negatives and compliance costs. 

The first step is to quantify and make the costs salient and institutionally aware. An apprenticeship, a scholarship, or a credit-linked subsidy scheme should be evaluated primarily on its uptake. A welfare benefit should also be evaluated on the cost of access and the extent of its exclusions. The compliance cost of sectoral regulatory regimes (environment, development control regulations, building byelaws, land, labour, cyber security, etc.) should be quantified, as also those for various kinds of registrations and licensing (shops, schools, restaurants, clinics, visas, land, etc.). 

This could be supplemented with an explicit articulation, for internal circulation, of an exclusion or compliance impact statement with every policy or regulation. This would provide policymakers and regulators the institutional freedom to account for convenience, access, and implementation flexibility, and avoid being exclusively hooked on loss prevention. 

Auditors and oversight entities must explicitly incorporate this dimension in their audits, assessments, and investigations that tend to focus only on the false positives. This would offer the combination of deliberative process protection, the vigilance-intake filter that separates the honest error from corruption, and the avoidance of the ex-ante (not hindsight) audit standard. 

Finally, the approval process should incorporate these principles across the gates. The financial, legal, and personnel concurrence/vetting should be circumscribed to ensure that the precautions and safeguards that are proposed don’t detract from the objectives. 

There is a high risk of these efforts spawning more bureaucracy. So it must be done thoughtfully and not in a checklist-filling manner, as was done in the case of EoDB rankings.

Further, given that most policies and regulations are administered digitally, a low-hanging fruit would be extensive adoption of data analytics. The digital trails of administrative and transactional data could be analysed to detect abuses and address them. The emergence of AI-enabled applications equips us with the tools to do this easily and effectively. The challenge in each activity should be to define the likely problems and analyse to identify signatures of abuse. 

To conclude, the stock of policies and rules with a precautionary bias is an output whose generator is the distrust wedge, or the asymmetric loss functions. The revision of rules one at a time merely empties the reservoir that the generator keeps replenishing. Therefore, the durable reform is to do a root cause analysis and recalibrate the generator with some of the aforesaid measures. This can shift the precautionary bias that is the current individual rational choice within the Indian bureaucracy. 

Saturday, October 10, 2026

Weekend reading links

1. Thanks to inflation global debt burdens have been declining, falling by 27 percentage points between early 2021 and end of 2023. 
2. Rent controls may do more harm than good, except in controlled apartments.
And Spain is a good illustration that immigration is adversely impacting the housing market.
3. Excellent article on ASML, 42-year old, Veldhoven-based, Dutch maker of the $400 million extreme ultraviolet (EUV) lithography machines. 
The size of a double-decker bus, the machine prints circuits on to silicon wafers by firing light generated from 60,000 droplets of molten tin per second at them, using mirrors, lasers and short-wave light in a kind of vacuum-sealed nano-photocopier... ASML’s supply chain is something else. Where a typical industrial product might have a few dozen suppliers, an ASML EUV has more than 100,000 parts provided by 200 principal suppliers and 2,000 companies overall... Rather than trying to make everything itself, ASML outsources to the best manufacturer of each component — Zeiss for optics, Trumpf for lasers, VDL for mechatronics.

4. BigTech AI borrowings have fragmented the US debt market into two parts - AI-borrowing and the rest - and there is a growing risk that the cost of capital for everyone will rise as AI borrowings rise.

The scale of the borrowing will have its impact in squeezing out the rest of the economy and raising cost of capital for everyone. And it is going global.
In June, Amazon sold C$14bn ($10bn) of debt, smashing the Canadian currency’s previous record of C$8.5bn set by Alphabet just a few weeks earlier... Last month Alphabet issued a record A$5.5bn ($3.9bn) bond in Australia, more than twice as large as the previous biggest. The group also holds the record for the largest Swiss franc bond issue, having raised SFr3.1bn ($3.7bn) there in February. Amazon’s SFr2.8bn offering in May is the second-largest... Alphabet sold £5.5bn worth of sterling bonds in February, part of a $31.5bn package that included a rare 100-year £1bn bond that some say rekindled interest in long-maturity sterling debt. Amazon also raised £4.25bn earlier this month, its first-ever sterling issue.
What complicates matters is that the surge in AI borrowings come precisely at a time when government borrowings are also rising and are competing with each other, putting pressure on bond yields. 

5. India equity market facts of the week.
Both the Nifty and the Sensex... have ended in the red for eight straight weeks, their longest losing streak in 25 years. In the first nine months of 2026, foreign portfolio investors (FPIs) have pulled out at least ₹3 trillion from Indian equities, surpassing all annual outflow records.

6. Excellent chronicle by MS Sahoo of the emergence of India's regulatory architecture since 1991.

7. African credit ratings fact of the week.

Of an estimated $4tn regional capital base, less than a quarter is covered by credit ratings, according to the African Union. At the end of 2025, it said, the continent had fewer than 4,000 ratings, compared with 823,000 in the EU and more than 2mn in the US.

8. John Mearsheimer describes the Iran war the "mother of all strategic blunders".

Iran is number one in my opinion, because 1) we went into that war based on the false claim that Iran was on the verge of acquiring a nuclear weapon; 2) we had a theory of victory — air power alone would produce regime change — that has never worked and was not going to work this time; 3) we had no contingency plan for dealing with the likelihood that Iran would close the Strait of Hormuz; 4) we failed to achieve any of our four principal objectives — regime change, ending Iran’s nuclear enrichment capability, ending Iran’s long-range missile capability, and ending Iran’s support for Hamas, Hezbollah, and the Houthis; 5) the Strait was closed, which has already done significant damage to the international economy and could do much more — remember President Trump worries about following in Herbert Hoover’s footsteps; 6) we seriously undermined our carefully crafted alliance structure in the Gulf; 7) virtually all of our bases in the region have either been badly damaged or destroyed, to the point where we have moved most of our military assets out of the Gulf region and will probably not be able to return; 8) we have run down our stocks of key weapons to the point where we have weakened our deterrent postures in East Asia, Europe, and even the Western Hemisphere; 9) we have done enormous damage to our reputation as a reliable and wise ally; 10) we have markedly improved Iran’s strategic position in the Gulf region; and 11) there does not appear to be much chance — perhaps no chance — that we will get a nuclear deal of any sort with Iran, which was once considered of the utmost importance. In fact, there is a reasonable chance Iran will acquire nuclear weapons. President Trump has certainly given Iranian leaders — and other leaders of non-nuclear states around the world — a powerful incentive to acquire a nuclear deterrent.

9. Martin Wolf points to why the Iran war did not disrupt the oil markets and world economy as much as expected, with real oil prices still only around the long-term average. 

Johannes Urpelainen of the Johns Hopkins School of Advanced International Studies notes that: “First, the energy transition has reduced the global economy’s dependence on oil. Second, supply chains have proven resilient and adaptive. Third, producers outside the Middle East have acted fast to produce more oil and natural gas. Finally, drawdowns of global oil inventories have filled the remaining gap.” Flexibility is notably true of the Gulf. As former diplomat Mohammed Elsoukkary writes: “by the end of September preliminary estimates placed regional crude exports at approximately 16.3 million barrels per day, compared with 19.5 million in February, including roughly 9.7 million moving through Hormuz.”
Interestingly, the world entered the War with record inventories, accumulated especially in 2025.
10. French bond yields are higher than Italy's.

Not only does it now cost France more to borrow than it does Italy and Greece; a rising number of big French companies enjoy lower market interest rates than does the French state. Of all the G7 nations, it has suffered most from the debt sell-off triggered by the Iran war... France’s debt has reached €3.5tn, at nearly 120 per cent of GDP, far above the Eurozone average. Servicing costs have climbed fast to become the state’s single biggest expenditure ahead of education or defence. In just a month the additional interest rate that France pays to borrow over ultra-safe German debt — a key barometer of investor concern — has surged by almost two-thirds to around 1.4 percentage points on 10-year debt, heading towards the heights charted during the Eurozone debt crisis... A series of ratings downgrades has helped push up the country’s borrowing costs, which passed Greece’s in late 2024 and Italy’s last year. Investors now label France the “new periphery”... Despite the government’s tax-raising powers, its borrowing costs now exceed those of big French multinationals such as LVMH, the luxury group, and Sanofi, the pharmaceutical company. According to Goldman Sachs, more than a quarter of investment-grade French companies had a lower yield on their bonds than comparable government debt as of the end of September...
Increasing taxes to deal with the rising cost of debt servicing could also be perilous. At 44 per cent of GDP, the tax burden is already among the world’s highest; the average in the OECD club of rich countries is 34 per cent. Almost a quarter of public spending is gobbled up by pensions. French retirees leave the workforce earlier and receive relatively generous benefits by OECD standards. Attempts to push back the retirement age trigger angry protests.

11. US Treasury bonds are now threatening to hit 6% for the first time since the turn of the millennium. 

Borrowing costs for companies with the lowest credit ratings hit their highest level since May 2020 this month at 17 per cent, driven by the rise in Treasury yields to multiyear highs and by investors demanding more compensation for lending to such businesses. The risk premium for companies rated triple C or lower has risen to 12 percentage points, the biggest since 2022. Analysts said companies with floating-rate loans, and those needing to refinance debt in the coming months, were most at risk from the government bond sell-off, which last week pushed the yield on the 10-year Treasury note to its highest since 2002... But a further rise in Treasury yields could lead to broader pain across credit markets, analysts say. When it comes time to refinance existing debt, higher rates risk jarring the many companies that took on debt when interest rates were at rock-bottom levels in the early 2020s. Moody’s estimated last year that a record $1.45tn of US investment-grade corporate debt would come due between 2026 and 2030. Rising rates will put pressure on businesses to increase profits at a similar pace to rising borrowing costs.

12.  S&P quarterly earnings growth to remain above 25% for more than three quarters in a row. 

13. Ethnic cleansing in West Bank and East Jerusalem now. 

Since 2018, Adani Group, its linked entities and consortiums have participated in bids to acquire 26** distressed companies through India’s bankruptcy process. It has won 16 of them, with one case ongoing, though the latest decision went in Adani’s favour. This is a 61.5 percent success rate – meaning it won nearly three out of every five bids. While 14 of these 16 acquisitions came through the Corporate Insolvency Resolution Process (CIRP) to revive distressed business, the other two came through liquidation aimed at winding up operations... Across the 16 Adani acquisitions where tribunal orders disclose both admitted claims and recovery, creditors were owed approximately Rs 1.31 lakh crore and recovered only about Rs 33,000 crore – just 25.4 percent of the total. The loss was estimated to be over 97,700 crore, making the haircut around 74.6 percent. That is slightly higher than the national average of 69.4 percent.

Monday, October 5, 2026

India’s affordable housing policy problem

This post will raise a conceptual point about the size of India’s affordable housing market and the targeting of policy measures aimed at them. 

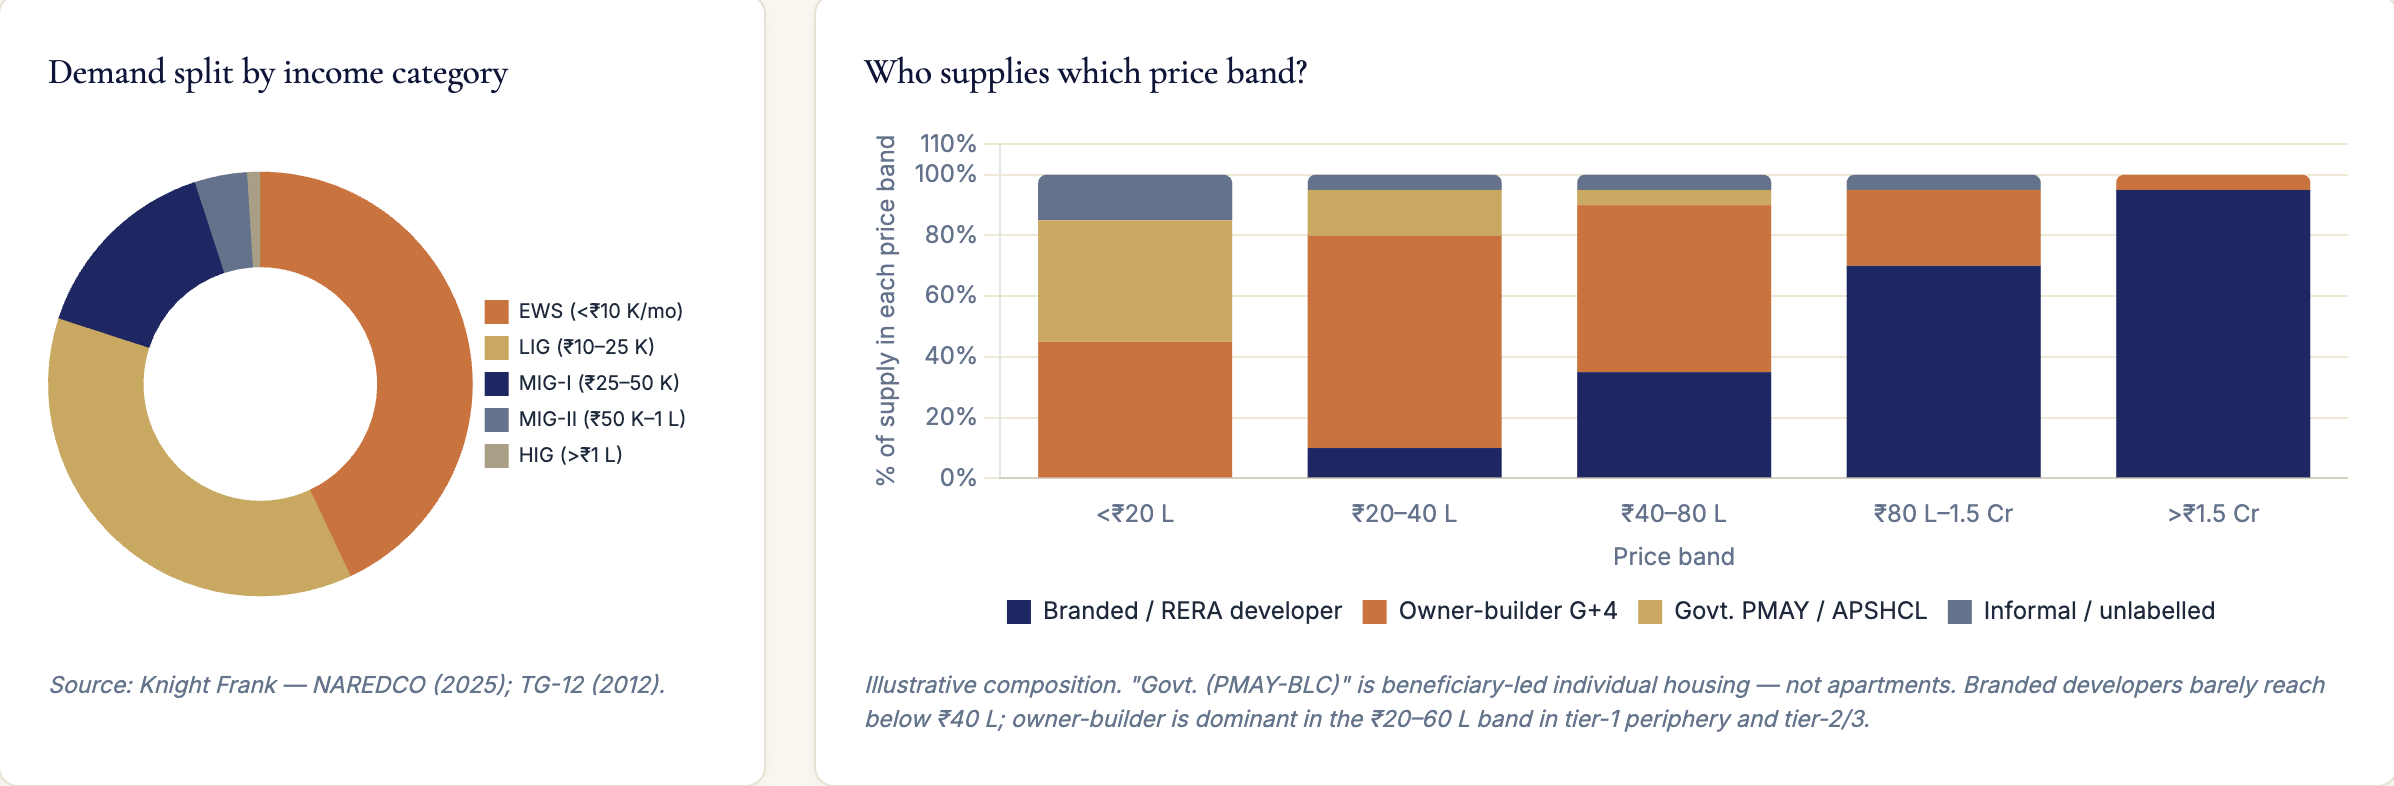
The vast majority of urban housing construction are apartment units that come not from the formal branded / organised developers in big plots with large numbers of units but from the informal small owner-builder segment in smaller plots with fewer units (typically 4-5 floors on about 500 sq yards). The vast majority of the latter belong to the affordable housing (AH) segment. However, state RERA rules, with their eligibility thresholds on the plot size and number of units, exclude the informal owner-builder segment. 

One implication is that the commonly reported numbers by real estate consultants are likely vastly overstating the deficit, which nevertheless is real and big, but also not reporting the quality, standards, and buyer protection problems that impacts affordable housing supply (by the latter). A bigger problem is that these owner-builder units are ineligible for all the policy benefits that the government provides on AH – GST, PMAY, PSL, etc. 

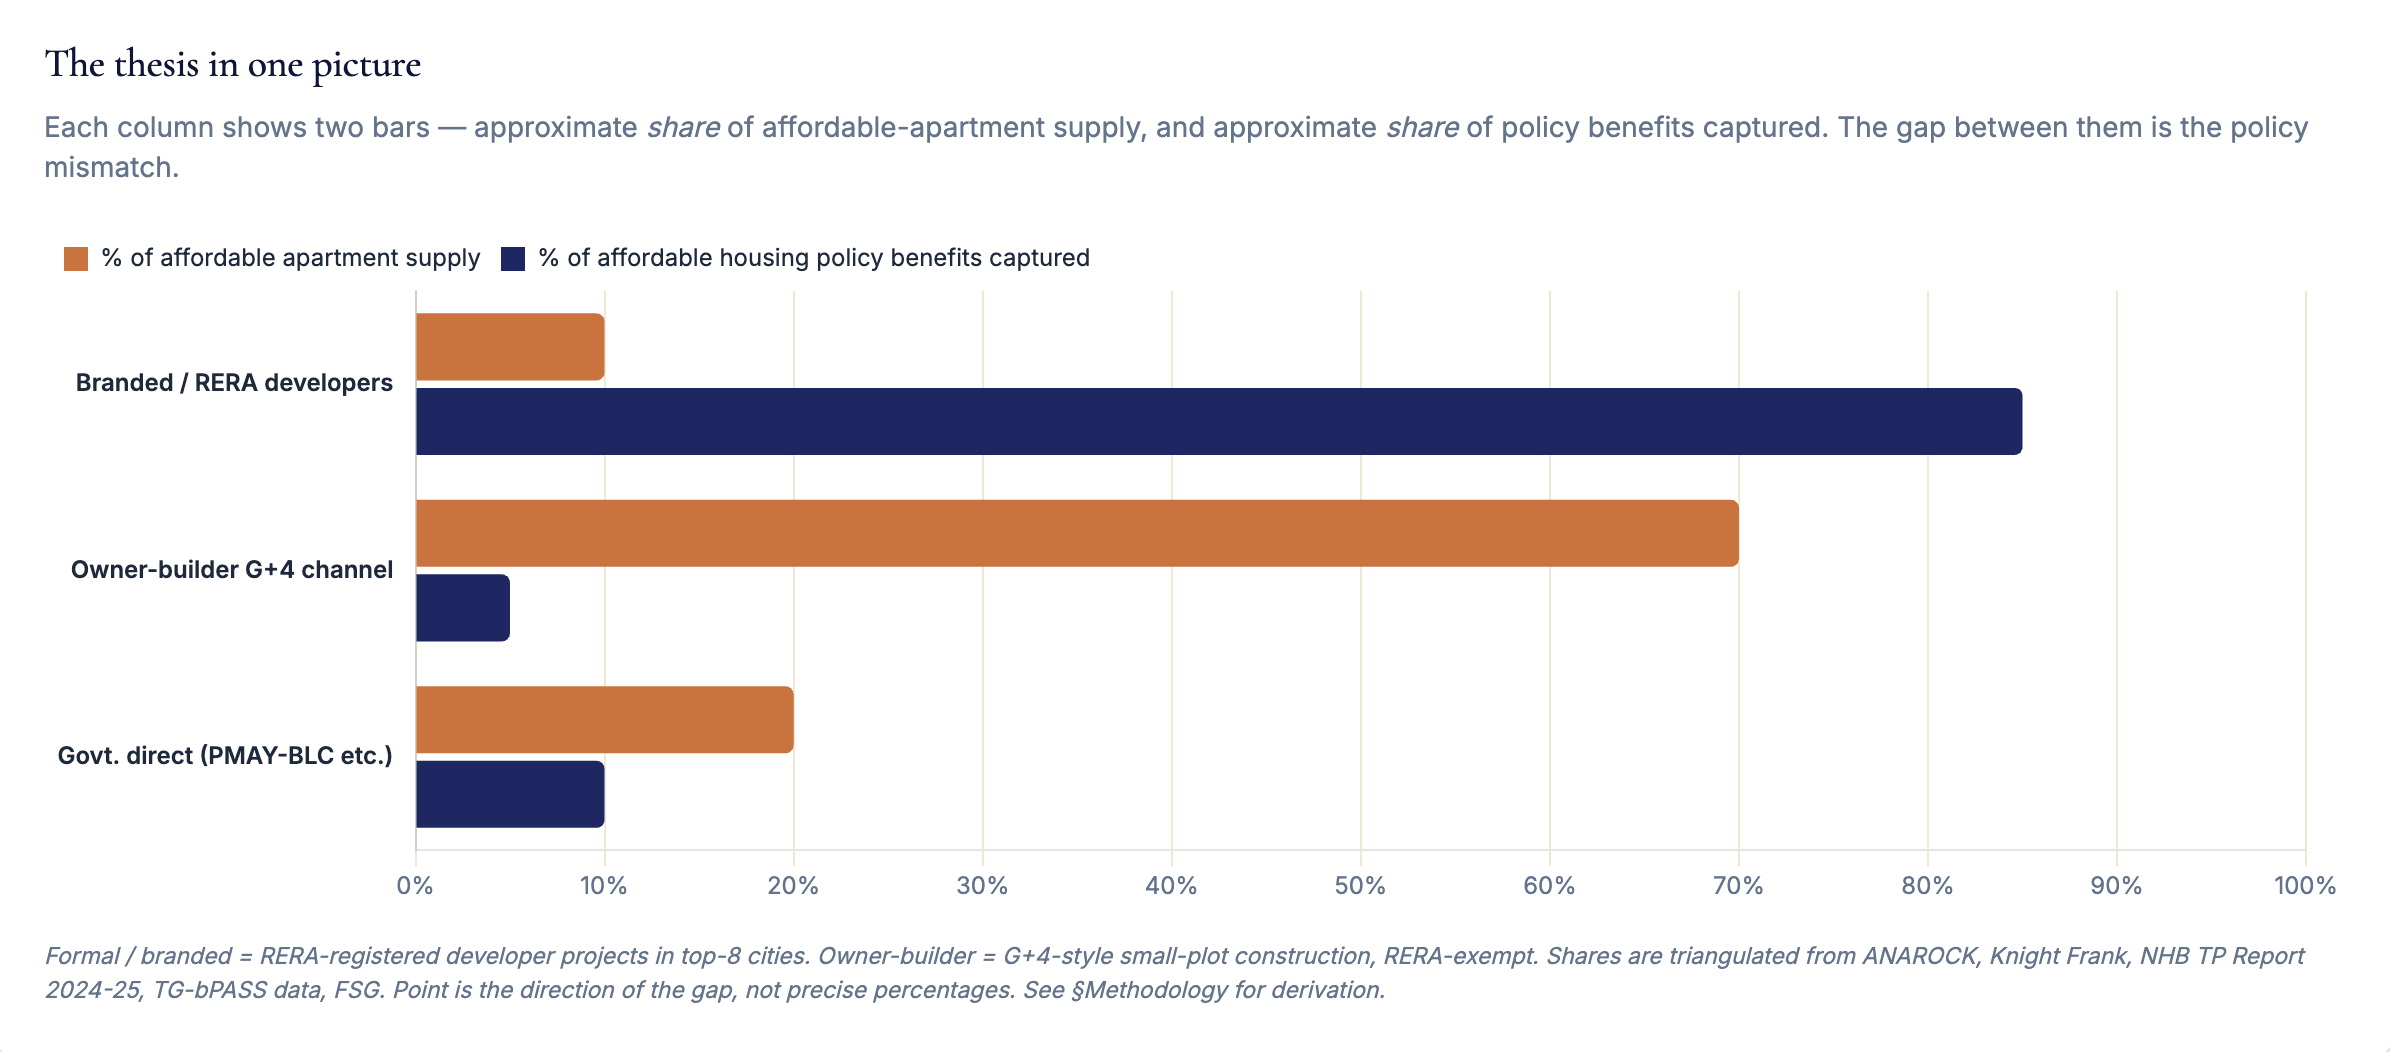
In other words, we have the perverse situation where all the policy benefits are cornered precisely by the formal / branded developers who hardly supply AH, whereas those informal owner-builders who supply almost all the AH are ineligible for these benefits. 

It is a challenge to get good data to assess the extent of the problem. 

The public debates on housing are anchored around the data supplied by real estate consultants. However, they are confined to the formal organized / branded developers in the top 7–8 cities, who develop RERA-registered gated-community projects with titled land and institutional finance. They contribute the vast majority of the units visible in the Credit Linked Subsidy Scheme (CLSS), 1% GST, 80-IBA, and Priority Sector Lending (PSL) developer construction finance. 

In contrast, it is a challenge to get good data on the builder-owner units. Three states — Telangana, Andhra Pradesh and Delhi — have built self-certification approval systems calibrated to exactly the owner-builder G+4 band. The approval volumes in those systems are the hardest evidence we have to assess the magnitude of supply of such units. The Telangana government’s TG-bPASS database informs that for the period from November 2020 to December 2023, the average number of owner-builder permits every year in Telangana urban for sub-500 sqm plots is about 35,000. 

Three independent estimations - extrapolation from the TG-bPASS, residual from housing stock accounting, and finance-implied - all point to about 0.6-1 million such units being constructed each year nation-wide. 

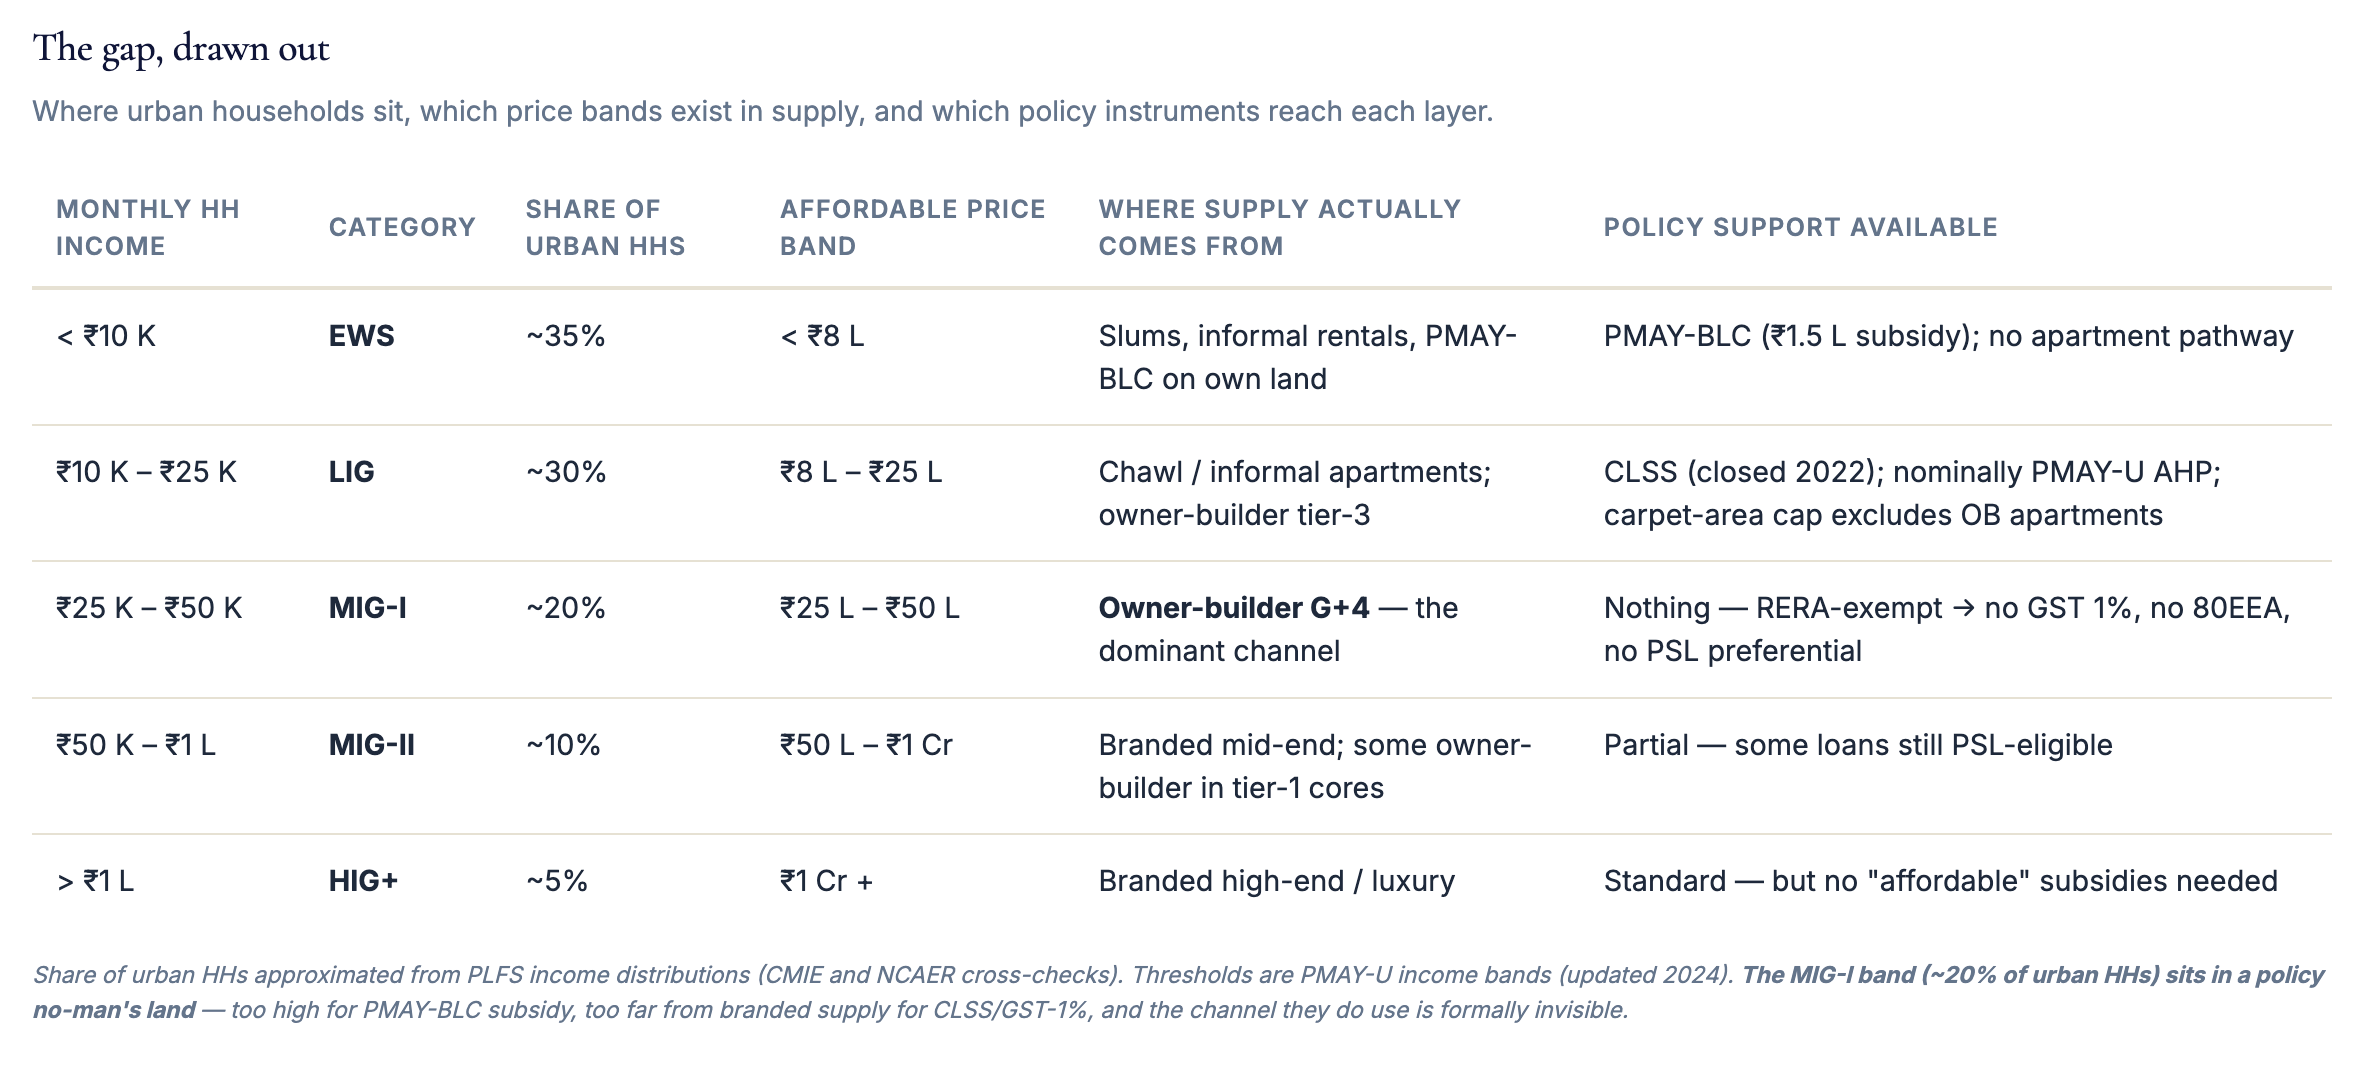
Based on the above, the graphic below captures a snapshot of the demand-supply landscape for housing. About four-fifths of urban housing demand is EWS and LIG. The formal / branded sector targets MIG and above. The owner-builder channel is the only channel at scale that reaches the middle of the LIG band and upper EWS.

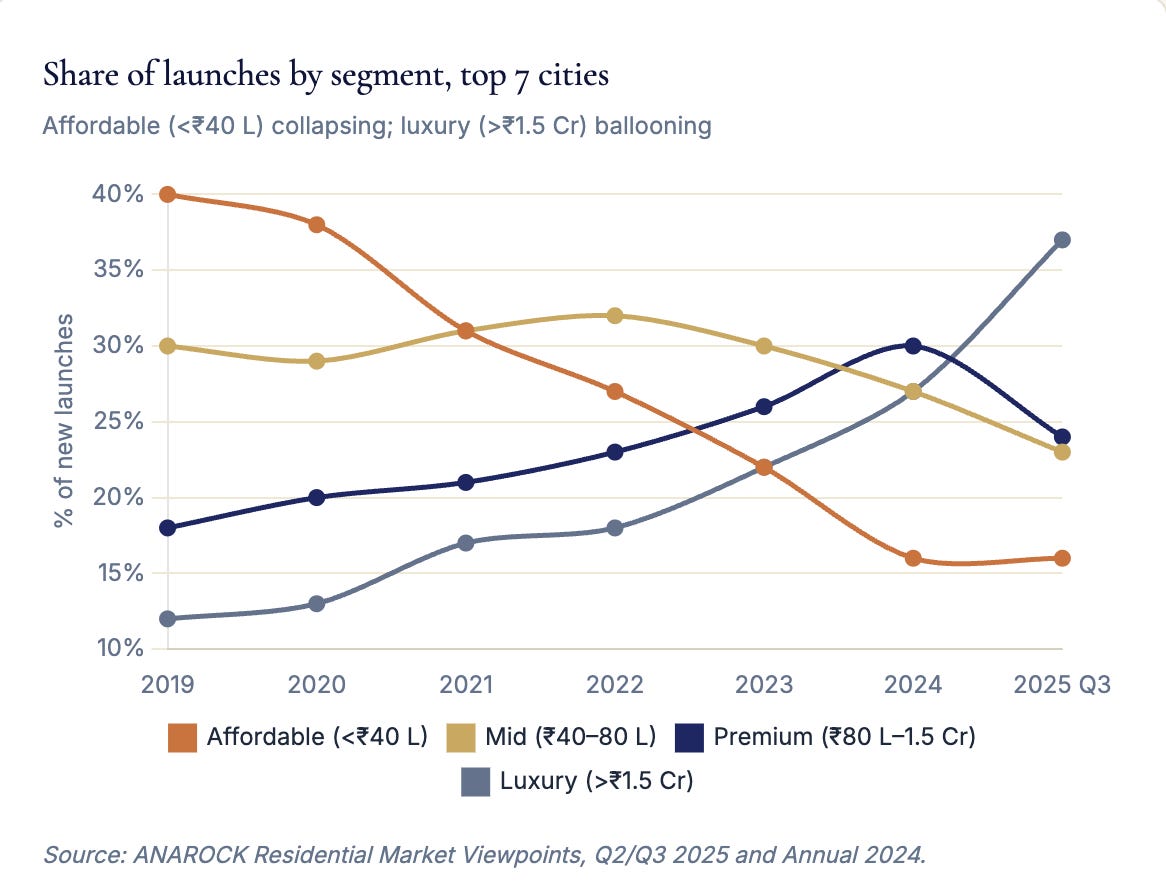
Let us first look at the AH market served by organised / branded developers, who build large numbers of units in each project in big land plots. Their share of housing launches that are AH (<₹40 L) was down from ~40% of the pipeline of the top 7 builders in 2019 to about 16% in Q3 2025. Note that the share of even mid-level housing has been declining. In stark contrast, luxury housing has been climbing steeply. Difficult to miss the K-shape. It can be safely argued that organised developers are quietly exiting the AH segment, and this is the big problem. 

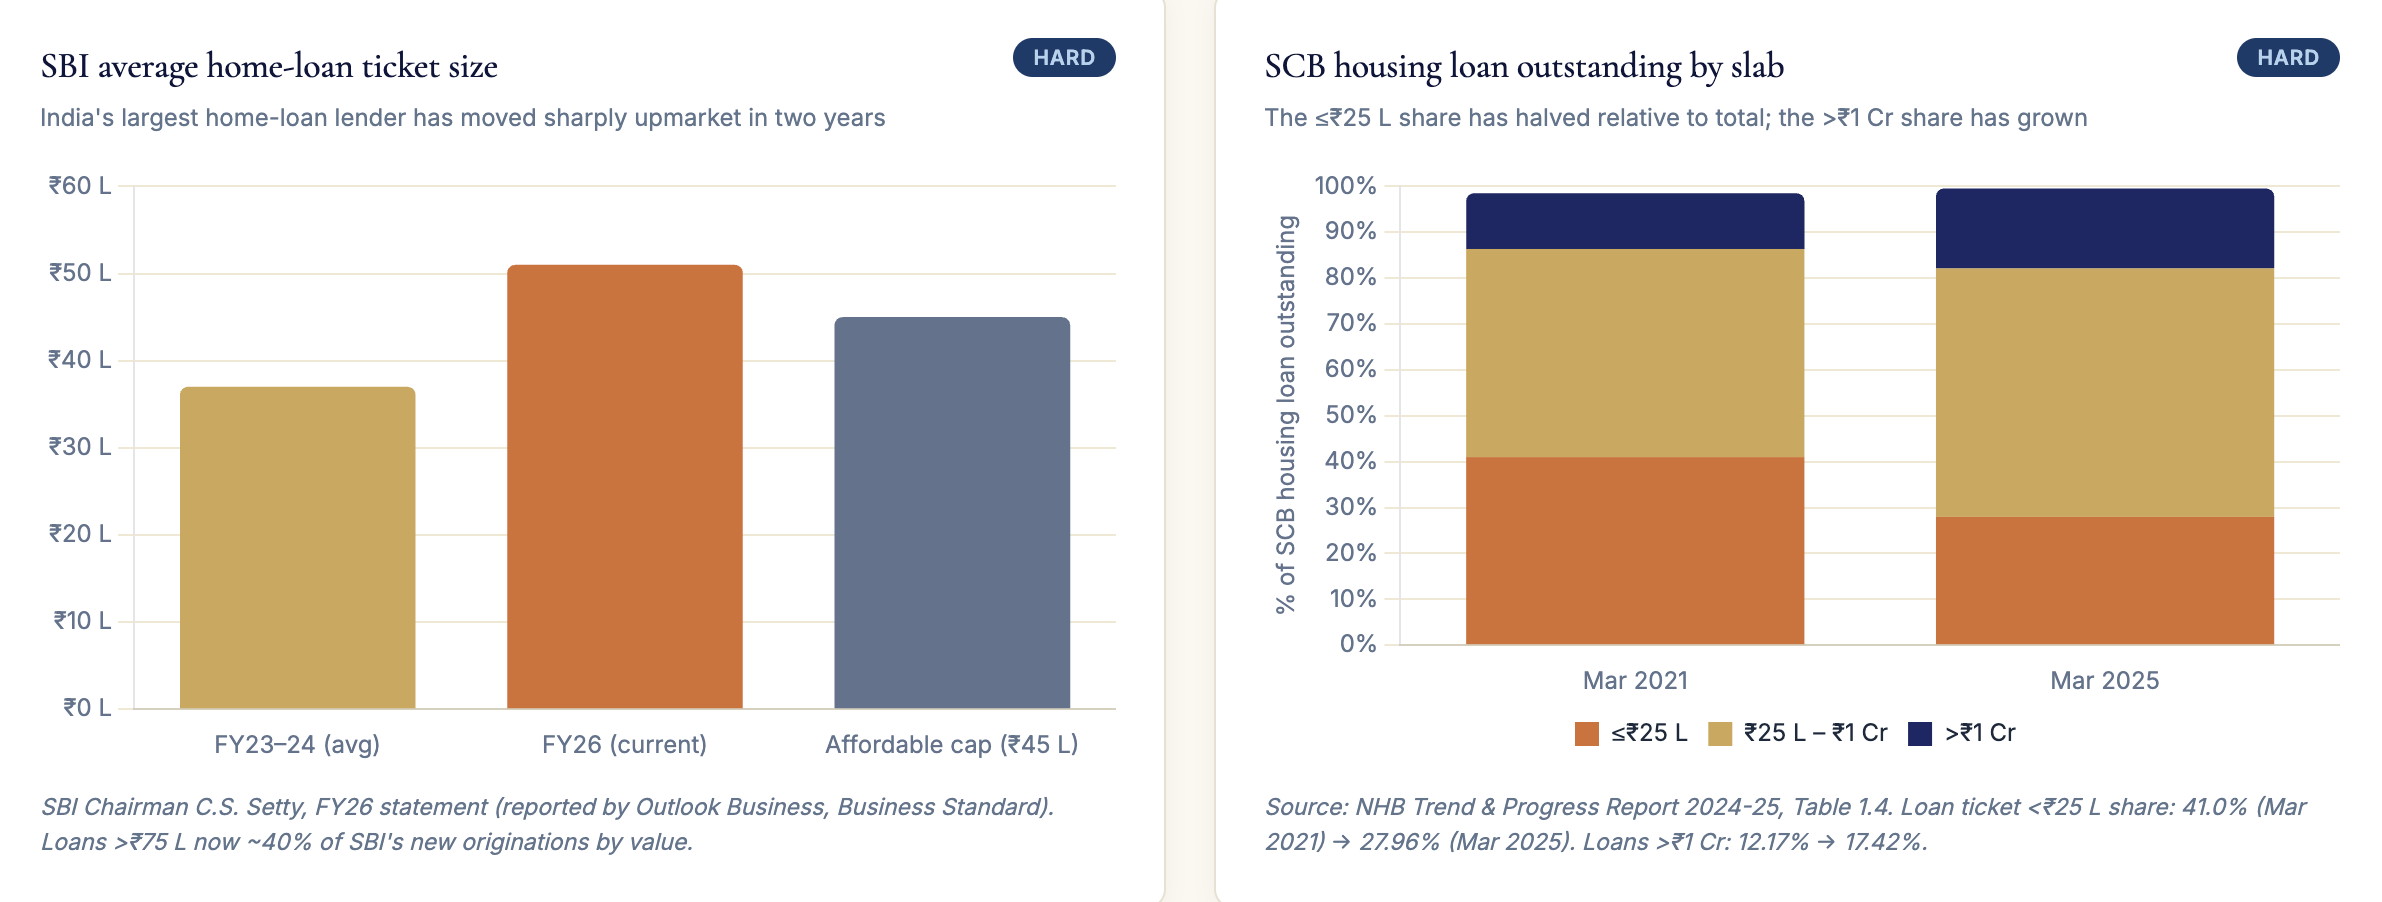
This is validated by the loans data from scheduled commercial banks, which are also drifting upmarket. Below ₹25 lakh, the SCB loan book share has fallen from 41% (Mar 2021) to 28% (Mar 2025). 

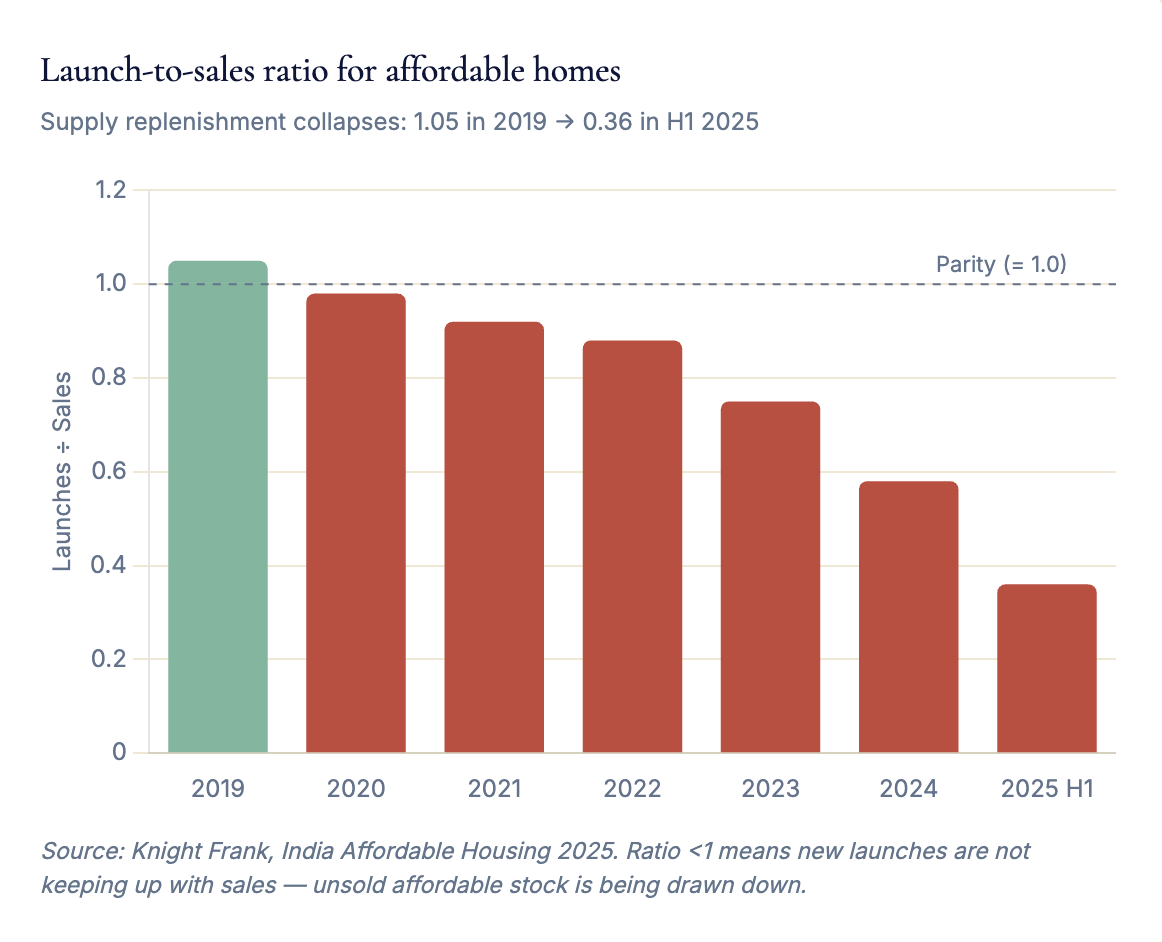
New AH launches too echo this trend. The developers have been drawing down the accumulated inventory, instead of starting new projects. 

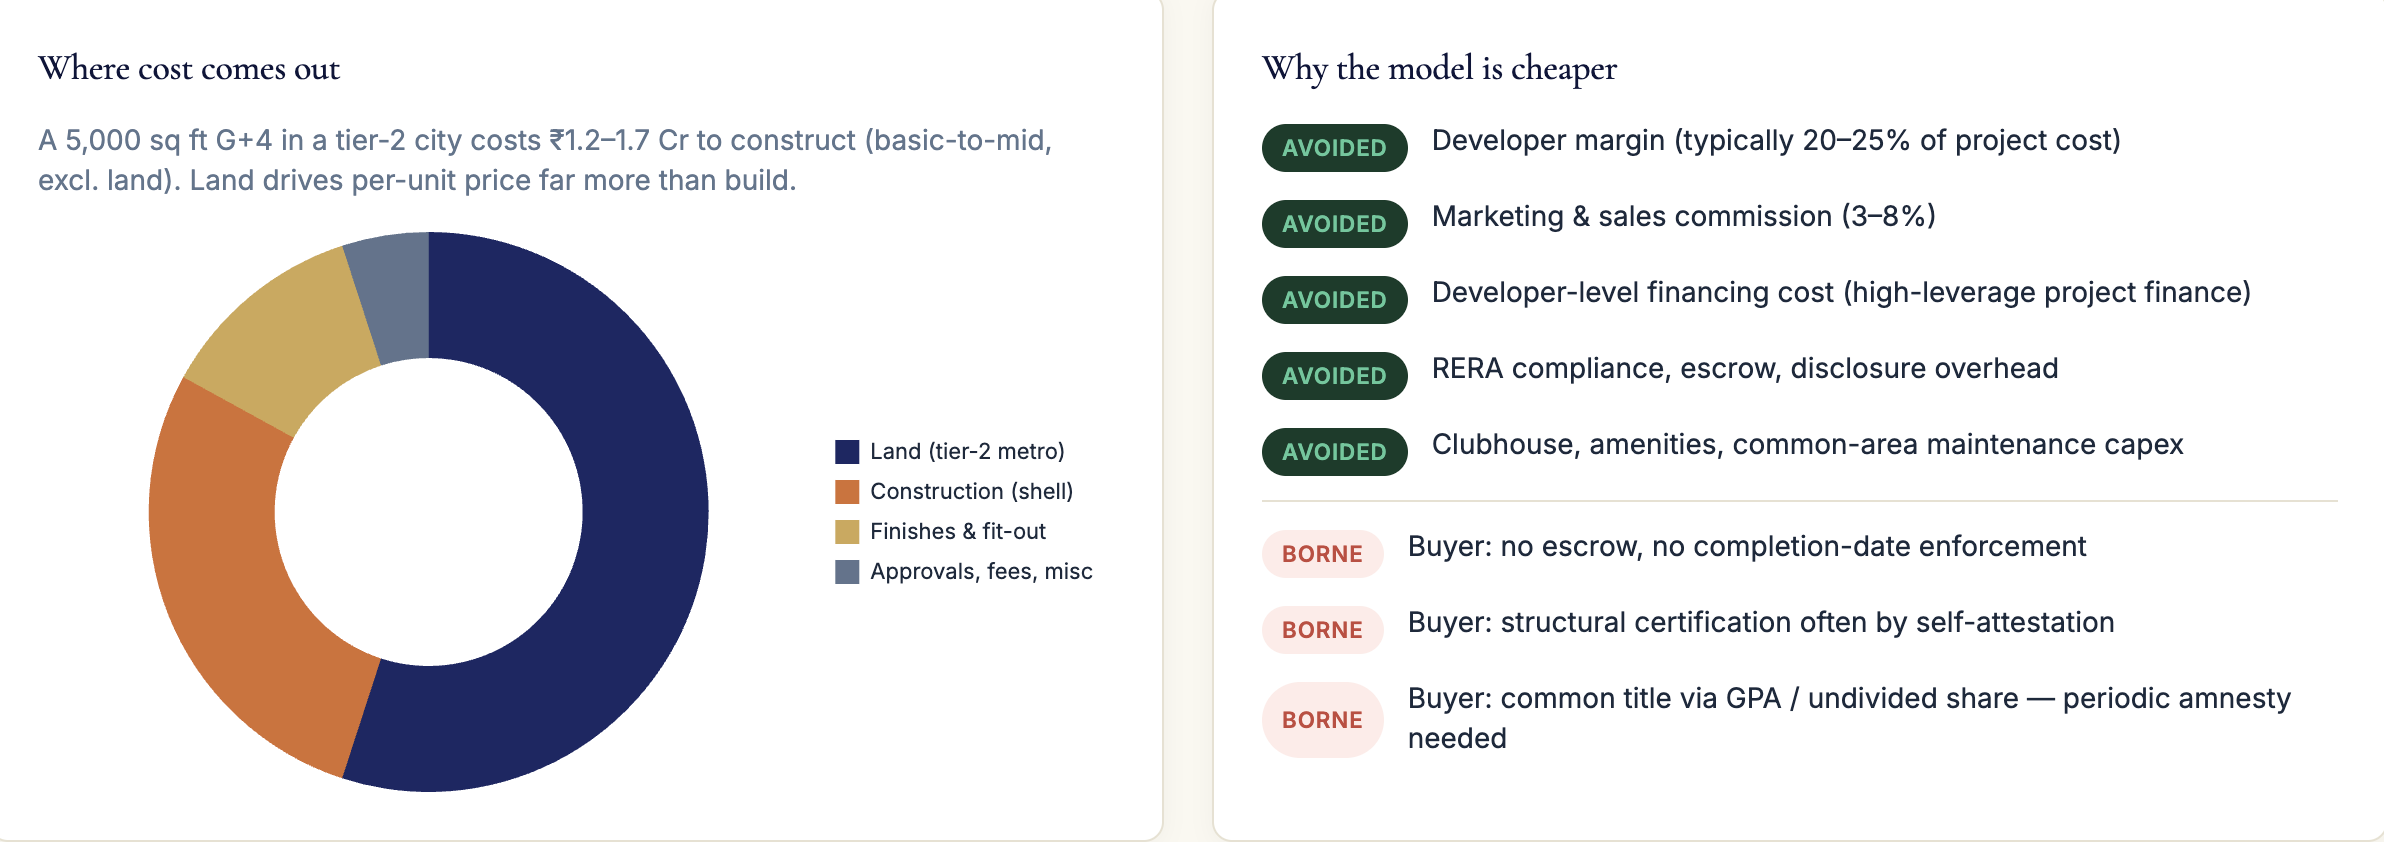
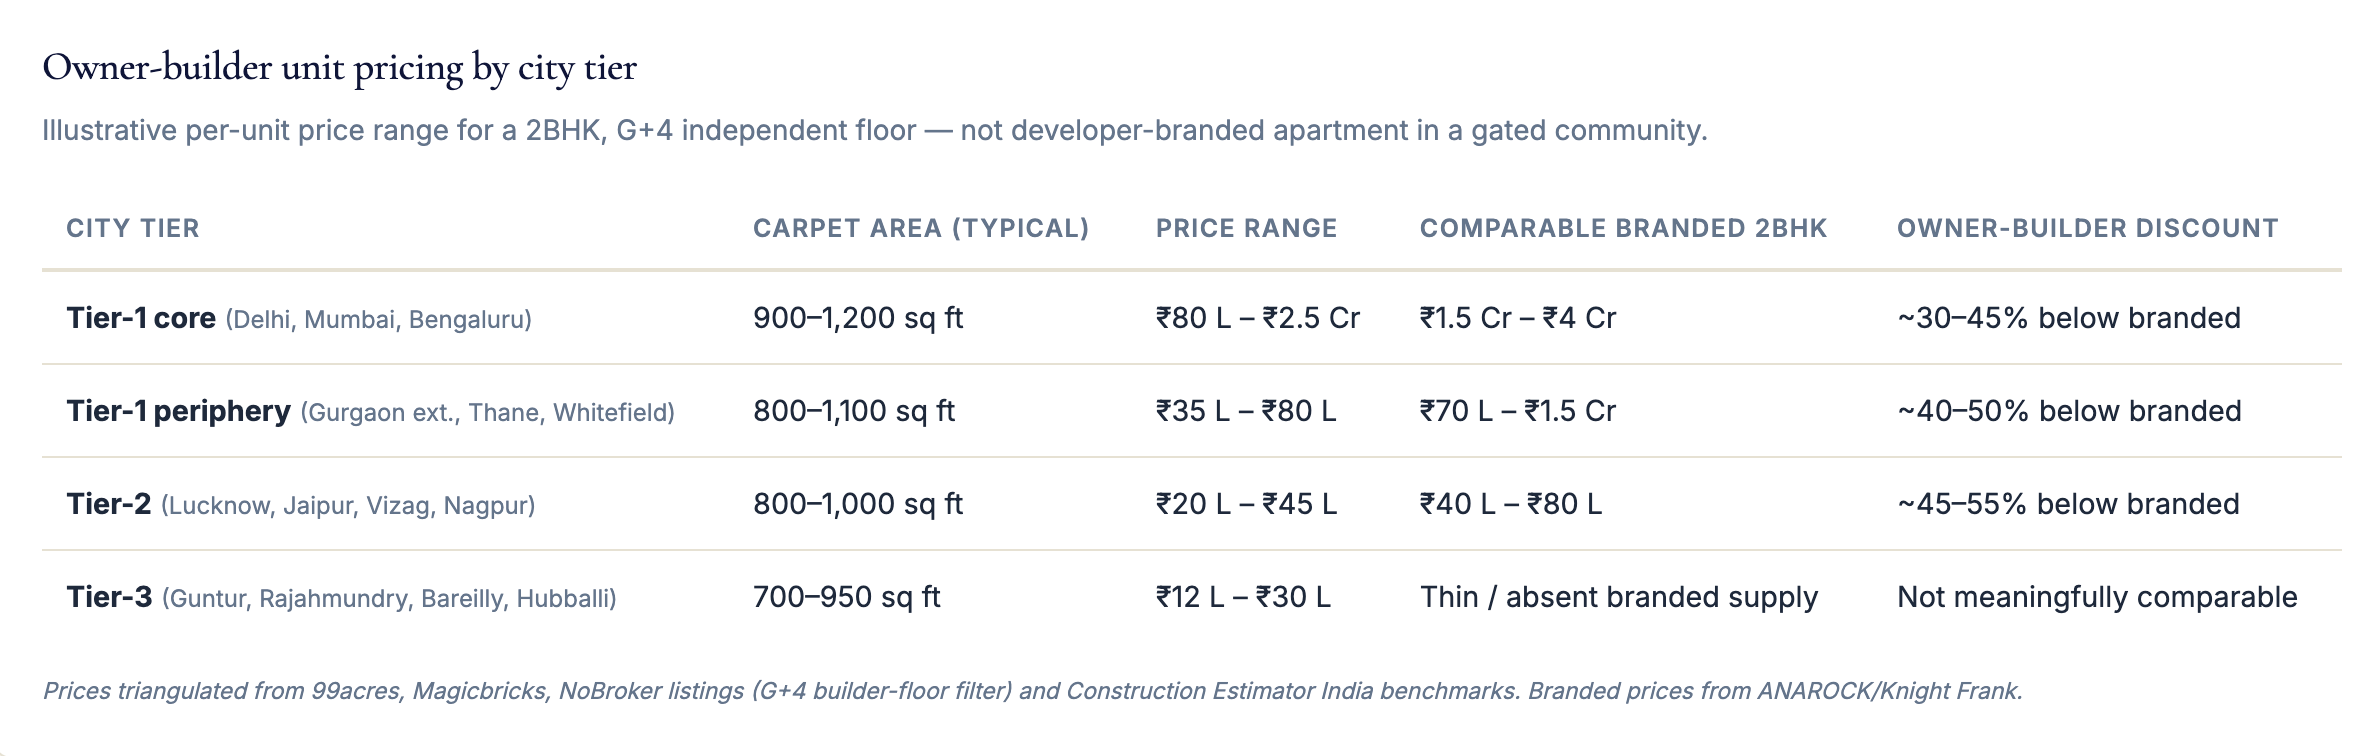
The unit economics of a owner-builder house makes them much cheaper. These are mostly individual plot-owners partnering with a small local contractor to build typically G+4 on 300–500 sq yd (~250–420 m²) in tier-1 periphery and tier-2/3 towns, with 4-8 units and statutorily exempt from registration under the Real Estate Regulatory Act (RERA). They are sold directly, often before launch, and have minimal advertising, and is transacted in a large share of cash and with personal loans. 

While pricing and area ranges vary by city tier, the owner-builder model is remarkably consistent, consisting mainly of 800–1,100 sq ft carpet, independent floor on a residential plot. And the favourable unit economics allows it to come at a steep discount on the branded unit of same size. 

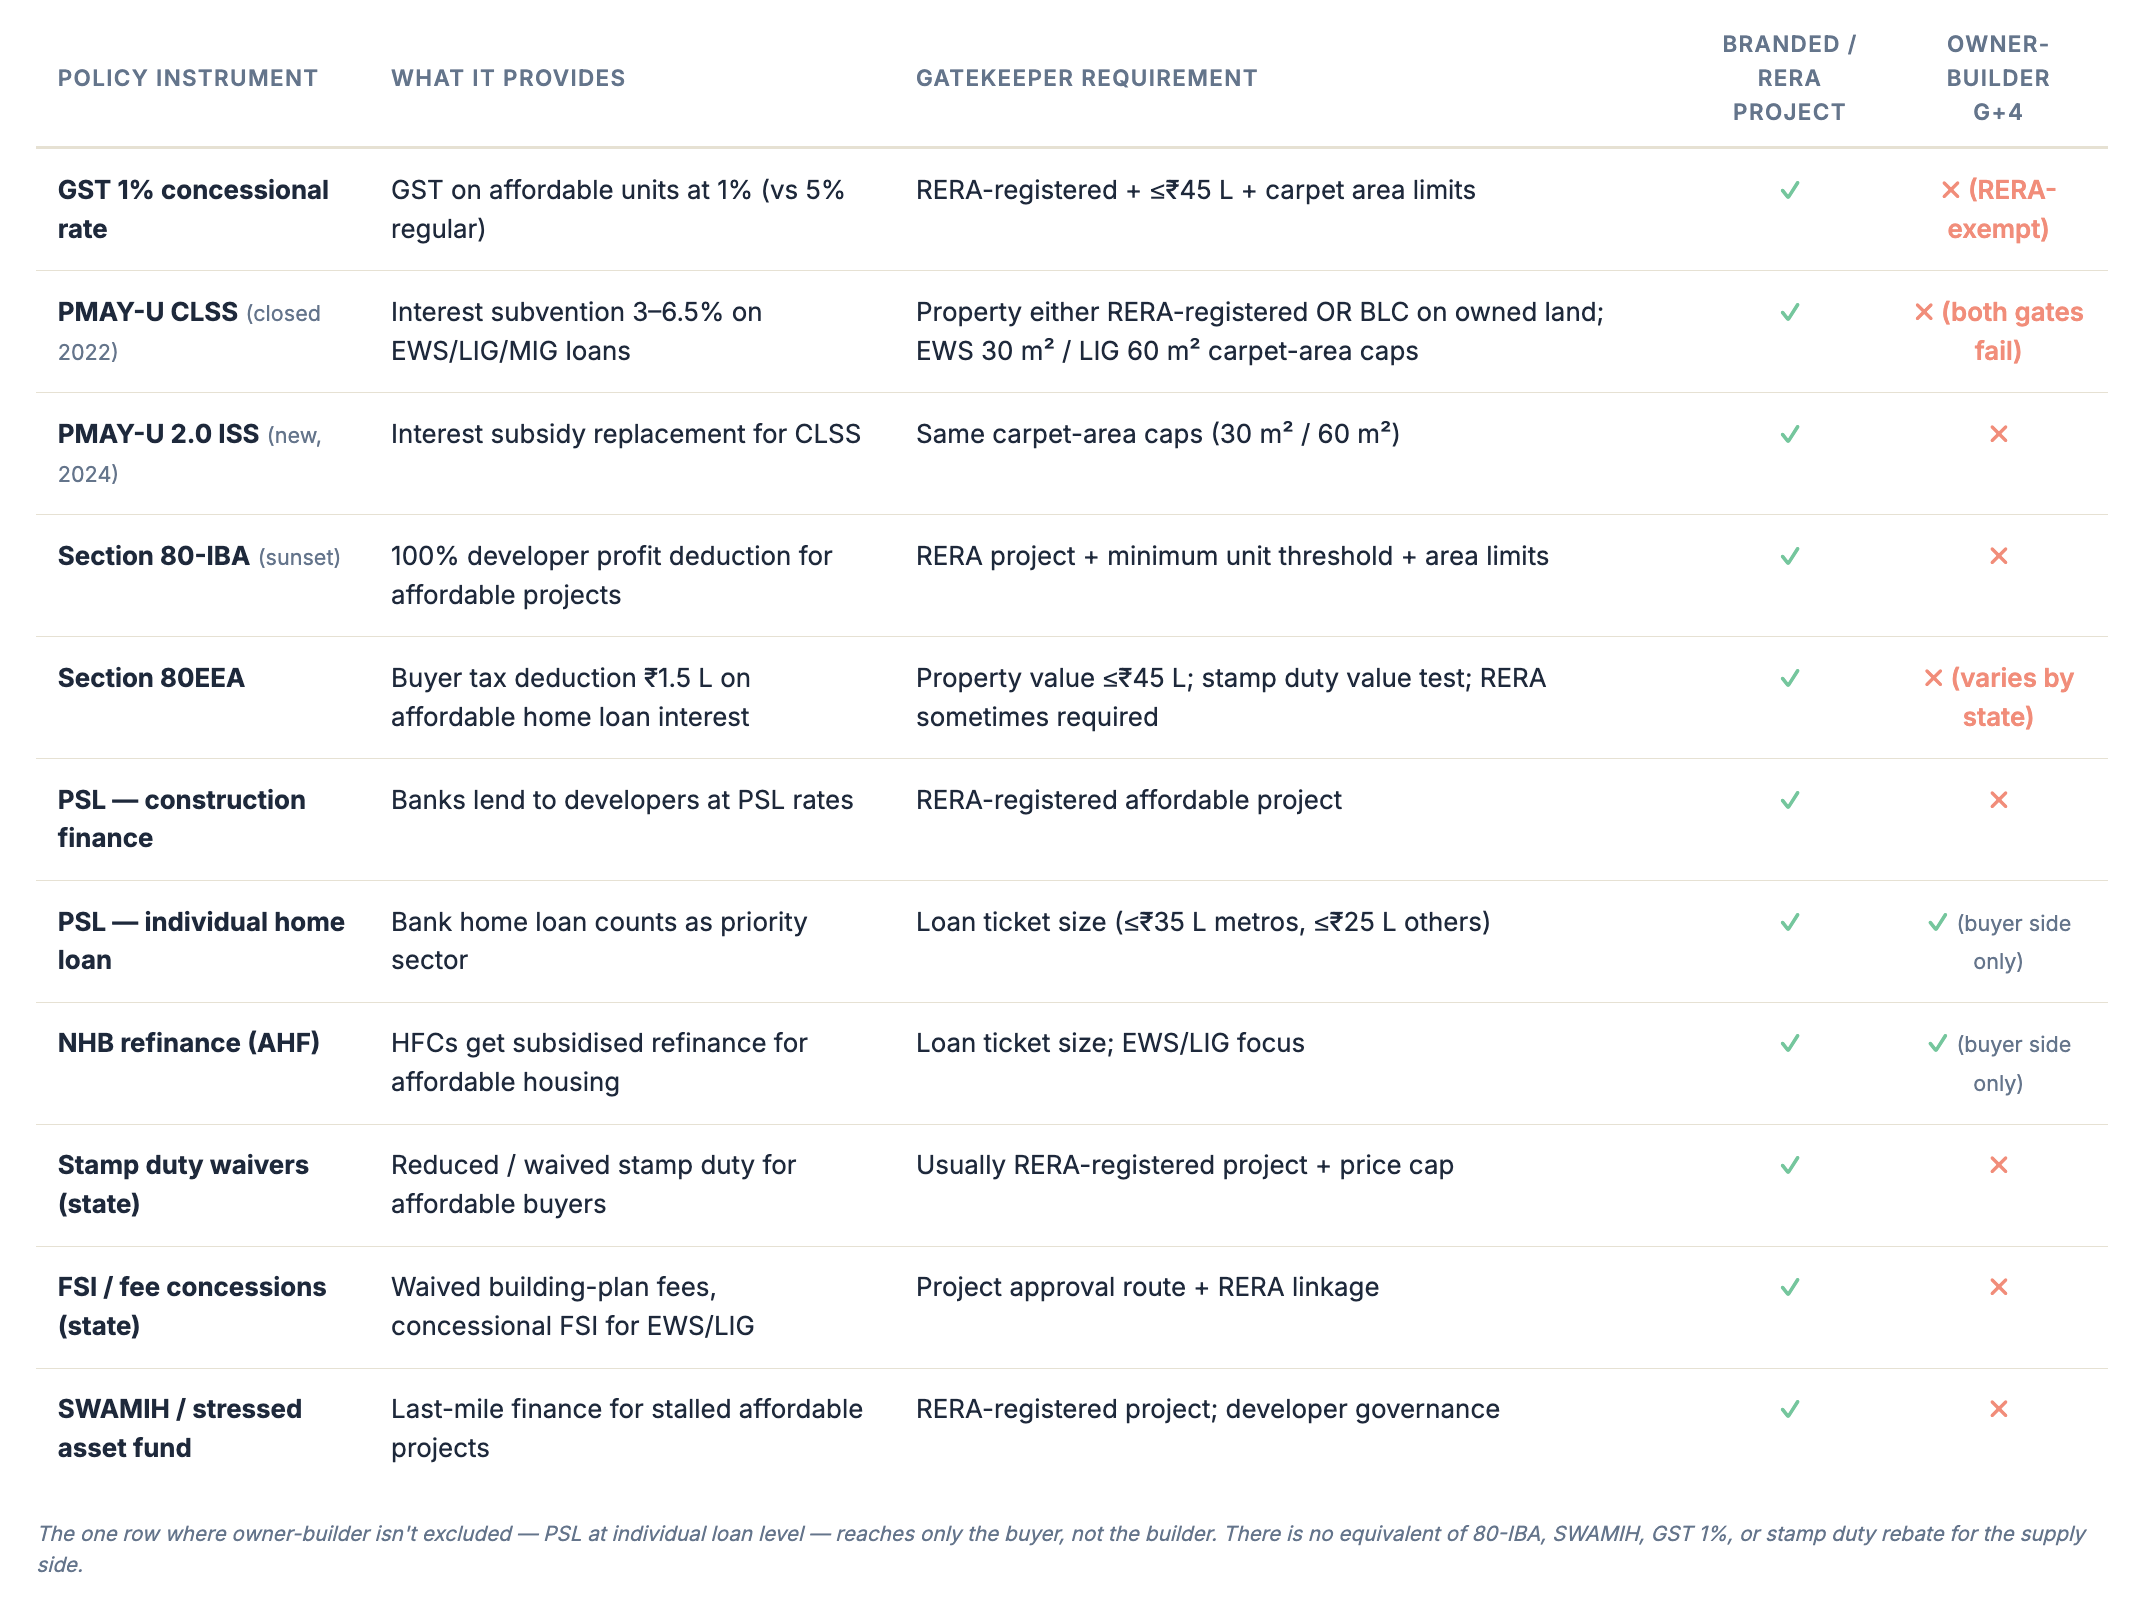
Now let’s look at the policy benefits available for AH. Interestingly, all policy benfits are gated through RERA registration. 

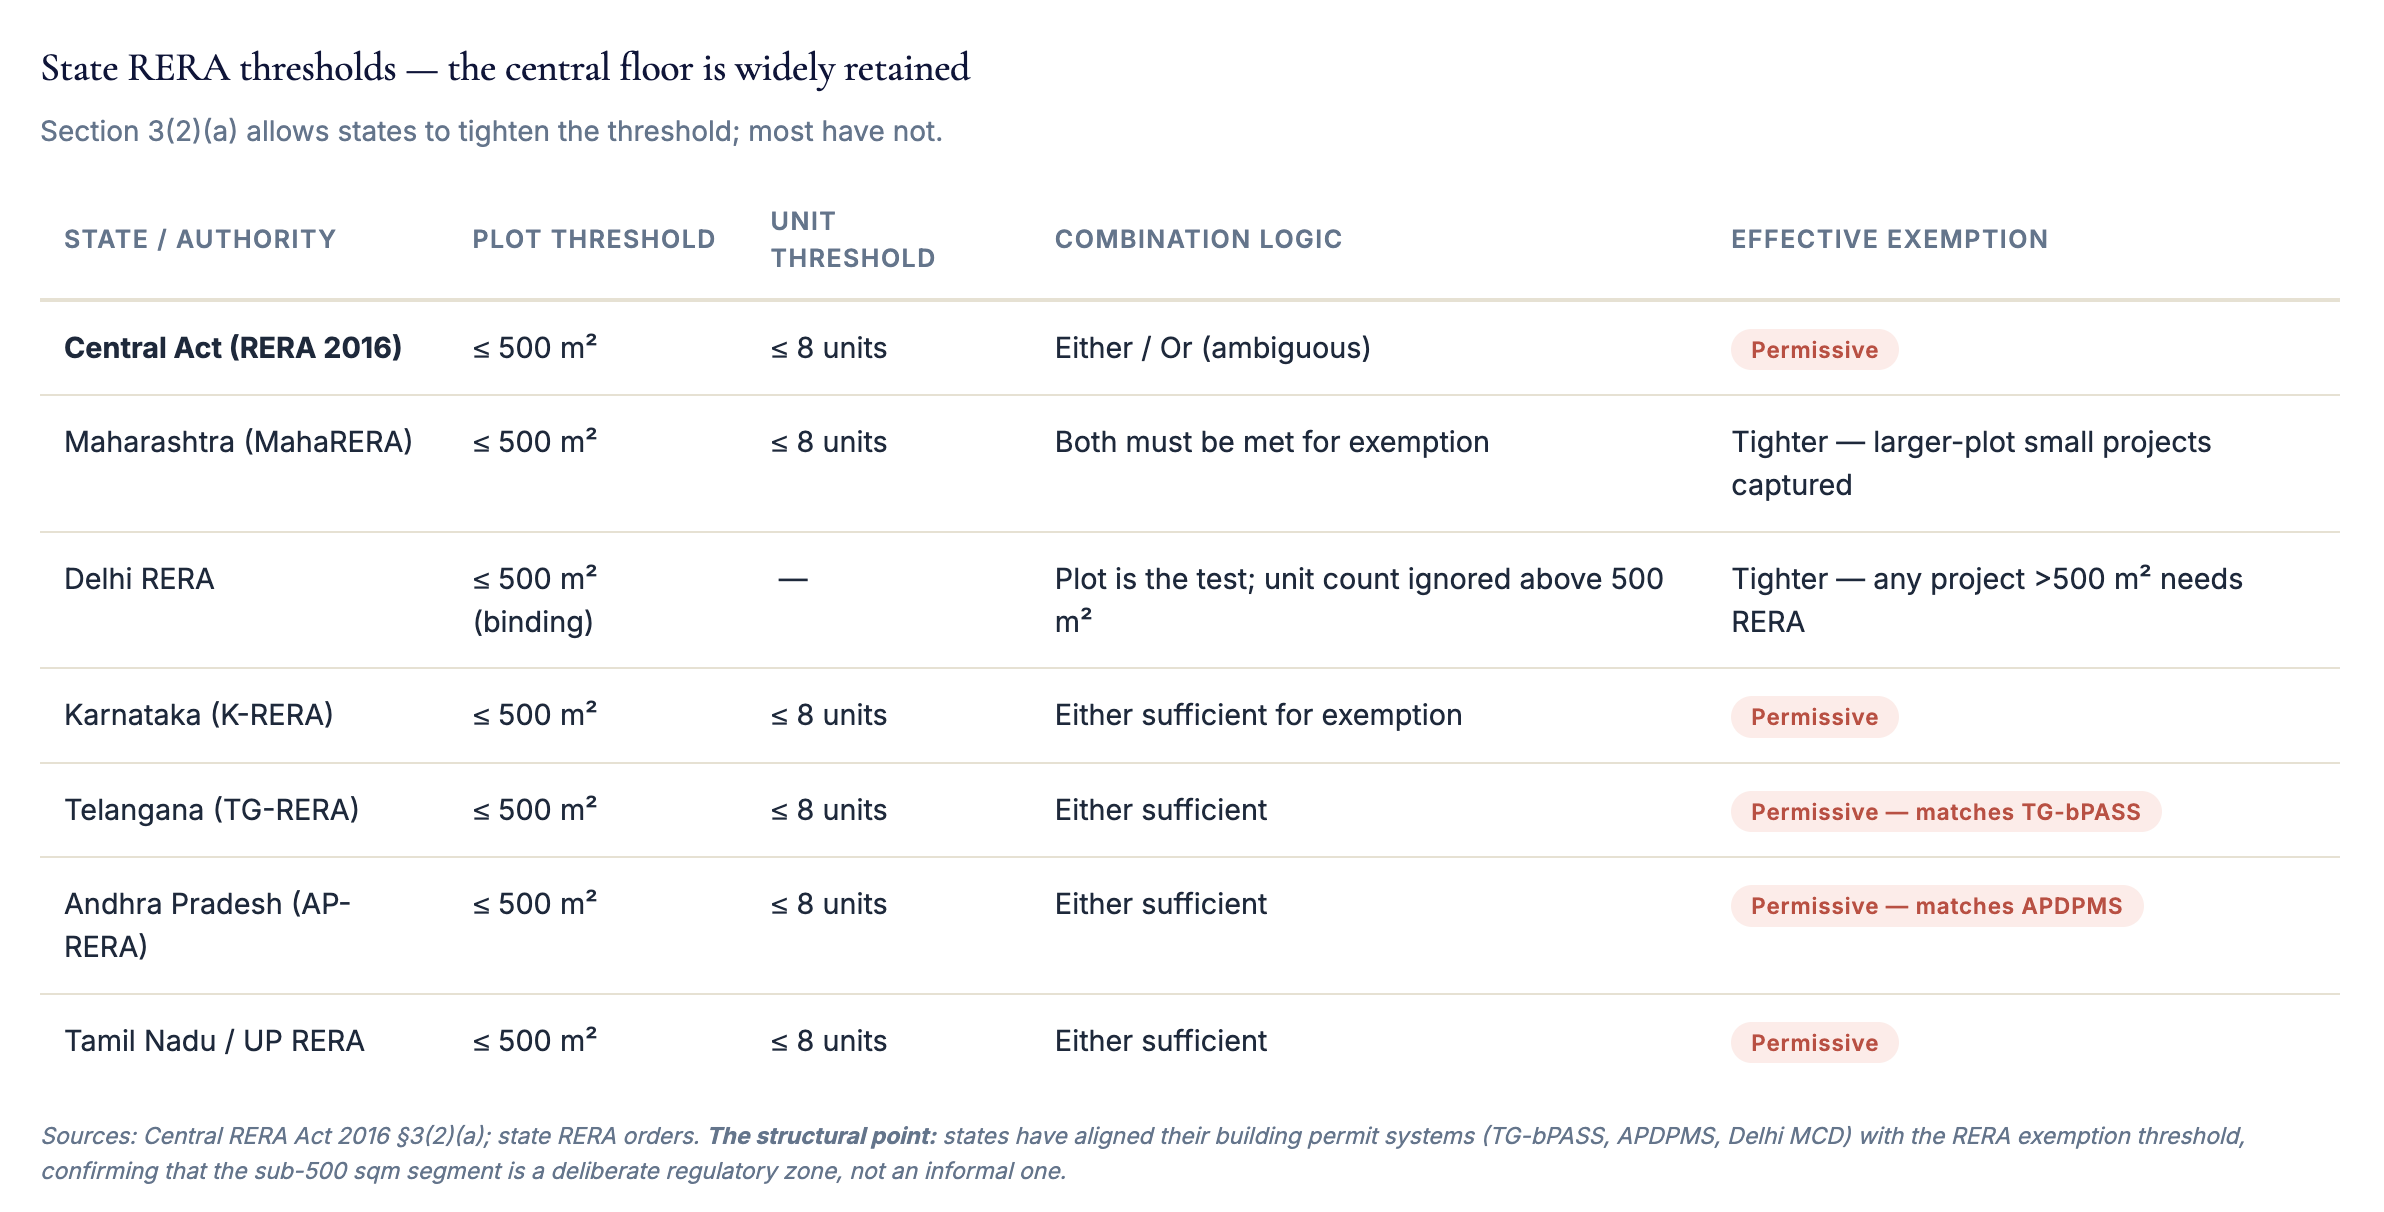
Under Section 3(2)(a) of the RERA Act, projects on land of 500 sqm or less, or with 8 or fewer apartments, do not require registration. Most states have adopted the central threshold. The G+4 structure on 500 sqyards sits almost exactly at the exemption line. 

The table below summarises the housing category-wise policy support provided.

The next table points to which among the different policy support measures are accessible to owner-builder projects. As mentioned, every single policy instrument designed for affordable housing uses RERA registration (directly or via tied eligibility conditions) as the gatekeeper, which ends up statutorily excluding the owner-builder segment. This is in keeping with the broader policy focus to formalise the informal. 

All this produces a perverse outcome. The branded / organised developer segment, which produces at most ~70,000 affordable units a year in the top 7 cities, captures the full stack of fiscal and regulatory benefits designed for "affordable housing", whereas the owner-builder segment, which likely produces 8–14× that volume of genuinely affordable apartments, captures effectively none of them! The graphic below tells a tale. 

Putting everything together, it becomes clear that while the owner-builder G+4-on-500-sq-yard model probably supplies the majority of India’s urban affordable apartments, it sits outside RERA by statutory design, and therefore outside almost every fiscal and policy benefit the state offers for AH. Instead, all the benefits accrue to the formal / branded sector, which barely builds any affordable at all. Classic mis-targeting of scarce public policy resources. 

The big takeaway is that India has a serious affordable-housing policy problem, and less an affordable-housing supply problem. The channel that supplies most of the affordable apartment stock is not the one the policy architecture is currently designed to reach.

So what on the way forward? Four responses come to mind. 

On the measurement side, since the published AH supply numbers systematically overstate the shortage by excluding the owner-builder channel, it may be useful to build a supply tracker that captures RERA-exempt stock using municipal building-permit data (TG-bPASS, APDPMS, Delhi MCD, etc.), AHFC self-construction disbursals, and listing-site scraping. The state-level building permit systems should be standardised along the TG-bPASS model. 

On the regulatory side, instead of lowering RERA thresholds wholesale, thereby raising costs, it may be prudent to have a lighter-touch “RERA-lite” tier for sub-500 sqm / sub-8-unit projects, with structural safety certification, simple possession-timeline disclosures, and a public register.

On the fiscal side, AH fiscal benefits (GST 1%, 80EEA, stamp duty waivers) should be decoupled from from RERA registration, and eligibility should instead be based on unit characteristics (carpet area and price, differentiated across tier cities). It may also be appropriate to create a specific PSL category for owner-builder project finance (small plot, G+4), channeled through Affordable Housing Finance Companies (AHFCs) and Small Finance Banks (SFBs) with structural certification as the gate.

Finally, on the policy architecture, it may be useful to shift the policy frame from the excessive push to formalise the informal. I have blogged here and here about how forced formalisation adds layers of costs and can end up creating more perversions than good. 

AH is a teachable example of how a well-intentioned formalise the informal policy focus has ended up creating distortions without serving the purpose. Instead, here the policy focus should be to serve the channel that actually serves the demand, the owner-builder model.

Friday, September 11, 2026

Deregulation - chainsaw Vs the wood-splitting maul

I have been thinking about deregulation. I find myself recalibrating priors. 

There are perhaps two kinds of it we see globally. At one end is the loud, politically driven chainsaw approach of the likes of DOGE and Argentina’s Javier Milei. At the other end is the cautious tinkering at the margins (à la using the wood-splitting maul) that is the feature of deregulation efforts driven by bureaucracies. 

The latter can only get you so far, and there is a need to strike the right balance, or sometimes even verge towards the chainsaw. 

Before we dive deep, the FT has an excellent long read on Javier Milei’s extraordinary deregulation efforts in Argentina, which is now focused on freeing up the oil and gas and mining sectors to make them the engines of Argentina’s economic growth. 

More specifically, he is intent on exposing the corporatist economic structure of Argentina, centred around Buenos Aires, and established by the populist policies of Juan Perón to a sharp burst of foreign competition.

First, on the nature of deregulation.

In April, Congress passed a law that could provide a major impetus to the mining sector by reducing what the government says were excessive restrictions on projects near the country’s many glaciers... Martín Pérez de Solay, head of the mining conglomerate Glencore in Argentina, says the country has seven mining projects under way that are “world-class” and believes the country could bring on new annual supply of 1.5mn-2mn tonnes of copper over the next decade — about a third of the output of neighbouring Chile, which is the world’s largest producer. The boom in oil and gas is already under way. The US government estimates that Argentina has the second-largest reserves of shale gas in the world, most of it in the Vaca Muerta formation in the Neuquén Basin in the south of the country. Investment is accelerating sharply, partly as a result of a new legal framework introduced in 2024 that provides tax breaks and other incentives. Wood Mackenzie, the energy consultancy, estimates that the pipeline of new projects now exceeds $100bn. “Argentina is on the cusp of a shale revolution,” it says, comparing the atmosphere to west Texas in the early 2010s, at the start of the US shale boom. 

Exports in mining, energy and agriculture have already increased to record levels under Milei, beginning to ease the dollar shortage that has underpinned Argentina’s chronic economic instability. Federico Sturzenegger, the minister for deregulation and one of the architects of the plan to liberalise the economy, says that the cumulative impact of recent investments will allow Argentina to triple its exports in the next five to six years... Sturzenegger says that access to cheap energy from shale oil and gas will lead to a new “industrial boom”, which could include sectors such as fertilisers and petrochemicals.

And it could have profound long-term consequences, including shifting the geographical centre of the country’s economy.

The sectors Milei champions are in some cases more than 1,000 miles away — mining in the far north, or oil and gas production to the south in Patagonia. The government talks about millions of workers moving out from Buenos Aires to outlying provinces in the coming decades... Buenos Aires, where almost 40 per cent of Argentine voters live... In the long run, he estimates that about 4mn people will leave the Buenos Aires area over the next 30 years — with 2mn decamping to the oil and gas region in Patagonia and another 2mn heading for the mining region in the north. “In the second half of the 20th century, there was a big migration from the interior to Greater Buenos Aires at a time when Argentina was one of the most closed economies in the world,” he says. “This process is exactly the opposite; it opens up the economy and generates competitiveness from exports and the population gradually reverts to the interior.”

However, the deregulation, being more like a shock therapy, is also resulting in the hardships and problems its critics have long predicted. 

The excitement among resources companies, however, is mirrored by rising pessimism among the domestic-facing industries that employ millions of Argentines. Manufacturing, construction and retail have all contracted or stalled under Milei even though economists surveyed by the central bank predict the economy will grow 2.1 per cent in 2026. According to government figures, about 3,400 manufacturing businesses have closed since late 2023 — more than 10 per cent of the total. In the formal labour market, over 240,000 jobs have been lost, a fall of nearly 4 per cent, although this drop has partly been offset by growth in the informal labour market where employees have minimal protections. 

Textiles have been one of the hardest-hit industries, as Milei’s tariff cuts open Argentina to a flood of cheaper foreign clothing, including via Chinese e-commerce sites such as Shein and Temu... manufacturers... claim the currency is overvalued in order to curb inflation; others say Chinese producers are using Argentina as a dumping ground for their surplus output... The owner of a large textiles business in Buenos Aires says the government has set companies like his up to fail by opening them to competition from imports without dismantling the high taxes and cost structures put in place under the protectionist Peronist model... Martín Rappallini, head of the Argentina Industrial Union, says that Argentine companies face an annual tax take equivalent to 56 per cent of the formal economy, the highest burden in Latin America... Real wages have failed to fully recover from a sharp drop in 2023, when inflation surged into the triple digits. Disposable incomes have fared even worse as Milei has scrapped subsidies for energy, water and transport, falling 17 per cent in real terms since early 2023.

Clearly, Milei has bitten the bullet with deregulation. There are none of the standard hesitations of bureaucracy restraining the political choice that has been made. Frederico Sturzenegger, an economist-politician with considerable government experience, is carrying out the Milei mandate. 

There will be costs, with its suffering and losers. Milei may not even survive to fight the next battle. But it can be legitimately argued that when a system is entrapped in a very bad equilibrium, restrained by powerful entrenched interests, it is unlikely to do any more damage than business as usual to break free and deregulate extensively. 

India is not Argentina. But there are enough pockets of well-settled bad equilibria that survive only due to a systemic preference for the status quo arising from lack of political appetite and bureaucratic restraint, itself perpetuated by a lack of stakeholder demand and accountability and poor quality of public debates and actions on the associated issues. While bureaucracy gets the blame for all the ills, there are others equally or more culpable. Chalta hai at worst, tinkering at the margins at best, has been the norm. 

I can think of a few areas where taking the chainsaw (as against the tinkering using a wood-splitting maul) is the need of the hour. These are just randomly picked top-of-head-recall examples, and there will be many others, even more relevant or important. 

A first-order deregulation measure would be to prepare a negative list of activities from which the government should stay away. It was a leap of faith two decades back when state governments in India decided to stop purchasing their own vehicles, recruiting drivers and Class IV employees, and generally outsourcing services. They were brave decisions then. The same appetite, to a much higher degree, must now be summoned to exit other areas. What good can be achieved for government agencies to be entrusted with the development of land and real estate, or develop solar and thermal power generation, or use public funds to compete with private investors, or generally make anything that is widely available in the market? Pure public goods, demonstrated market failures, and strategic considerations must be the only reasons for governments being directly involved in activities. 

One of the highest-impact areas for reform would be a wholesale deregulation of urban planning norms. This would involve significantly easing (or increasing) development control limits, allowing much greater flexibility to landowners and developers, generally avoiding micromanagement with tight prescriptions, and proportionality in regulation depending on the nature of the property and use. This would entail radical upending of the prevailing paradigm of urban planning, a task that goes far beyond the imagination of even the most progressive of domestic planners and policy makers.

On the ease of doing business, the real disruption can happen only when we make the process of starting, expanding, diversifying and closing a business, exporting goods, etc., essentially automatic unless a genuine public-risk threshold is crossed. This would entail essentially culling several gatekeeping rules, or at least confining the rigorous gatekeeping only to a small set of prioritised categories. Deregulate extensively for all but the subset of higher-stakes categories, thereby making life simple for the vast majority. 

Another deregulation would be to dramatically reverse the inverted duty structure on inputs and outputs that inflicts serious costs on manufacturing and trade. This structure makes manufacturing and exports uncompetitive, entraps industries in bad equilibria, creates numerous perverse incentives, and also ends up creating distortions in areas like the utilisation of GST tax credits.

More specific areas of doing business in a globalised world deserve radical overhauls. In gatekeeping areas like food safety, product standards, communications security, etc., where our own regulatory regimes have struggled to keep pace, it may be more appropriate to embrace global standards through the likes of mutual recognition agreements. The only caution should be to ensure that they do not discriminate against domestic stakeholders. 

Human resource management within the government is another area which requires radical deregulation. The tightly prescribed one-size-fits-all recruitment rules are a relic of a bygone age, and must be revised wholesale to be made fit-for-purpose in the age of AI and disruptive changes. Even with all its risks, the recruiting entities must be given significant flexibility to formulate these rules as per their requirements. In general, the procurement rules are aimed at the median circumstances and stymie the growing long-tail scenarios. It is precisely the opportunities lurking in these long-tail scenarios that have the highest transformative potential, which are now blocked out by these procurement rules. 

Two specific industries where deregulation can have potentially transformational impacts are in the areas of clinical trials and other processes for drug development, and in oil and gas exploration. In both cases, the outcomes of all policy engagement to date have generally been disappointing. It therefore stands to reason that it cannot get any worse with deregulation. 

Arguably the most disruptive deregulation would be to delegate functions, funds, and functionaries to local governments. Decentralisation across levels of government can be transformational. This will certainly create abuses and excesses, but will lay the foundations for positive long-term change. 

More generally, as an agenda for those interested in taking forward effective and sustainable deregulation, here is a project.

I can think of six fundamental principles that are the heart of regulation, and the shift required in them. They involve moving from the process of permissions to one involving registration, ex-ante approval to ex-post accountability, one-size-fits-all rules to risk-based regulation, government inspections to self/third-party certifications and audits, protecting incumbents to protecting competition, and regulating inputs and processes to regulating outcomes. 

Instead of expending energy articulating principles, holding workshops, and writing opeds, it may be useful for those interested in getting governments to deregulate to prepare drafts of specific regulations that incorporate these new paradigm principles and make them available in a transparent manner (indicating the changes as proposed) as the agenda for engagement with policymakers and for public debates. Thanks to the likes of Claude, the task becomes easier, though getting the details reasonably credible is still a painstaking process of discussion and iteration. In a large country like India, all it takes is for one among several governments to make the leap of faith on deregulation. 

I’ll blog on this at a later occasion.

In all these cases, there will be an avalanche of protests and stiff opposition. There will be scaremongering of all kinds that would restrain even the boldest of bureaucrats. Hell might break loose in some cases. In electoral economies, the political economy of such costs can be daunting, as Milei is finding out. 

For sure, the costs will be real when looked at from narrow and limited time perspectives. But it is the medium- and longer-term that should be of interest. There will be capture by vested interests, exploitation, corruption, wastage of public resources, and abusive practices. But they are unlikely in the aggregate to be worse than the slow-moving dysfunctional train that we have now. 

In a famous essay, The Principle of the Hiding Hand, Albert Hirschman articulated the hiding hand principle as a form of beneficial ignorance that helps planners start projects they would otherwise have avoided due to uncertainties and risks. He points to the power of unseen creativity that would emerge to solve these unexpected challenges. Likewise, it is required to trust the hiding hand to make the leap on deregulation and be prepared to address the egregiously bad outcomes that invariably emerge. 

While at it, it is pertinent that there are also areas where taking the hammer on enforcement is equally required. Tukaram Munde’s strident ongoing enforcement of food safety law is a case in point. Excesses and apparent disproportionality of enforcement are par for the course with such endeavours in ultra-permissive systems. Here too, the wood-splitting maul is inadequate, and the chainsaw is necessary for any meaningful dent in the problem, even with its collateral costs.