Substack

Showing posts with label US Economy. Show all posts

Saturday, September 12, 2026

Weekend reading links

1. A bond market story of the last two weeks has been the rise of the 10-year Japanese government bond yield above 3% for the first time since September 1996, following a weakening yen and an unprecedented bilateral market intervention with the US Treasury to shore up the currency.

The market expects a rate hike by BoJ from its current 1% to prop up the yen and also quell rising inflation. However, this would clash with the commitments of Prime Minister Sanae Takaichi for fiscal spending to boost the economy. 

The pressure on yen and rising bond yields are also a matter of concern for the US, since it could trigger repatriation of the massive Japanese investments in dollar assets, including the holding of US Treasury bonds.

Japan is the top foreign holder of US government debt, with more than $1tn, much of it held by financial institutions... market concern that Japan’s enormous pension funds and life insurers, nursing tens of billions in paper losses on their bond holdings, could shift their investment strategies as yields at home become more attractive... Citi’s Takashima said life insurers had been waiting for yields on 20-year JGBs to hit 2.5 to 3 per cent but were still not buying at scale as they feared that prices could drop further.

2. This is an excellent article on baby diaper manufacturing in India. The two costliest items are not manufactured in India and are imported.

Further, there's an inverted tax structure.
At the 56th GST Council meeting on 3 September 2025, diapers were moved from 12% to 5%, effective 22 September 2025... But SAP sits under HSN 3906, taxed at 18%... Output at 5%, inputs at 12% to 18%... input tax credit piles up faster than it can ever be set off against output tax. The credit is not lost. It is refundable under Section 54(3), and from 1 October 2025 the government began granting 90% of such refunds provisionally. But refundable is not the same as available.

Diapers are covered under PLI, and it is ending up supporting contract manufacturers who import SAP. 

Until an Indian chemical major commits to commercial SAP capacity, every rupee of PLI is subsidising the assembly of imported chemistry. We are building the world's fastest converting industry on someone else's molecules.

In this case, the PLI should target the SAP manufacturing in India. Supporting contract manufacturers to make what they are already doing does not require PLI. It underlines the point that PLI needs to focus on domestic value addition and not merely investment and sales. This requires more detail-based policy making. 

3. Tata Capital Healthcare Fund appears to be doing what public innovation funds ought to be doing, de-risking new market segments in healthcare. 

TCHF is not really in the business of spotting the next unicorn and riding it to a listing. It is in the business of manufacturing acquisition targets. It finds a chronic, non-negotiable demand, dialysis, cancer, joint replacement, wraps a proven clinical model in Tata credibility, scales it into Bharat where nobody else will do the asset-heavy work, de-risks the operations, and hands a finished, cash-generating, regulation-cleared asset to a global consolidator or a domestic roll-up desperate to enter that exact niche...

TCHF works because of a stack of things that have nothing to do with money: extreme sector focus, operational depth, brand-as-regulatory-passport, a structure that insulates it from its own parent, and the patience to build assets strategic buyers are forced to buy. Take any one away and the model wobbles... The winners in corporate venture will look... more like TCHF: narrow, patient, operationally heavy, and quietly building things the giants of their industry will one day have to acquire.
Jayant Mundhra's Substack is excellent.

Also on AI, the latest PISA student learning outcomes survey findings show uniform declines in reading and math. 
The new report shows that reading scores across the OECD have fallen by 25 points and maths by 22 points since 2018. “Given that 20 score points is roughly equivalent to a year of learning, this implies that a majority of 15-year-old students across the OECD in 2025, on average, were performing at a level typically expected of 14-year-olds,” according to Pisa. Schleicher linked the decline in the latest scores to the dominance of distracting short-form videos on platforms such as Instagram and TikTok, as the report suggested that “digital distraction” is harming education across the world. “We cannot say for sure, but skimming social media feeds and rapidly processing information may be contributing to worsening ability and motivation to engage with complex texts and data,” the report said.

5. US labour-capital share of output - rising corporate profits amidst falling wage share. 

Pre-tax earnings hit an annualised $4.8tn in the second quarter, or 18 per cent of national income, according to Bureau of Economic Analysis data, the highest share since the aftermath of the second world war. Employees’ share from wages and benefits fell to 60 per cent, the lowest level since the 1950s... Bumper returns largely benefit richer Americans, who receive much of their income from investments, while middle- and lower-income households rely more heavily on pay cheques. Inflation has also outpaced wage growth, causing real hourly earnings to fall by 0.2 per cent in July versus a year earlier.
6. A global whisky glut, or whisky loch, amidst rising consumption in India.
The amount of whisky maturing in casks has soared from less than 400mn litres a decade ago to around 1.4bn litres this year, or 389mn cases — enough to meet current consumption levels for three years, according to Martin Purvis and Duncan McFadzean’s Commercial Spirits Intelligence newsletter. That has caused many of Scotland’s distilleries to curtail output by more than a third, insiders say... Today’s glut is the result of increasing production during the 2010s, which led to an excess of casks maturing during times of global economic uncertainty.

7. California, the bastion of liberalism, struggles to build. 

A high-speed rail line that voters approved in 2008 but that has yet to lay a track. A large housing project outside Los Angeles and the redevelopment of a Navy yard, both in planning stages for decades. The state has arguably the nation’s worst housing crisis, with rent and home prices that far exceed the national average. The high cost of living, combined with strict environmental and land-use regulations, has led to a steady migration of companies and residents to less expensive states. The main problem, Mr. Metcalf continued, is that California’s overlapping regulatory processes, scattered among state and local agencies, make it nearly impossible to approve — or even outright deny — a project. Even when the governor or state legislators get behind an idea, local governments often have effective veto power. Delay becomes the normal course of nonaction.

8. London's experience in reducing knife crimes.

Knife crime rose dramatically in Britain from 2017, especially among teenagers... Hospitalisations for “assault by sharp object” have fallen by a third in London since their peak. Knife-related homicides have shrunk by a half. Last year teenage homicides in the capital fell to their joint lowest level (similar to 2012) in almost 30 years... As English politicians scrambled for answers during the 2017-19 “epidemic”, Lord Sadiq Khan looked to Scotland. In the previous decade Glasgow, once labelled Europe’s murder capital, had achieved impressive reductions in violent crime. One reason was the roll-out of the Scottish Violence Reduction Unit (VRU), which aims to prevent violent crime by bringing the police, schools, hospitals and sports clubs together to identify at-risk children and direct them away from crime. Between 2008 and 2018 Scotland’s VRUs were credited with bringing about a 38% fall in homicides and a 43% drop in attempted murders and serious assaults—many of them knife-related. 

Lord Khan announced England’s first VRU in London in 2018. Today there are 20 such units across England and Wales, covering areas that account for 80% of all knife crime. A recent Home Office review found that England’s VRUs caused a 12% fall, since 2019, in hospital admissions for violent assault among the under-25s. That is modest compared with Glasgow, but the Home Office looked only at the national average. Violent crime has fallen most in cities like London—dense urban areas where the model is easiest to implement.

9. The state of gender empowerment.

In India violence against women is so normalised that nearly 40% even of women think a husband is sometimes justified in beating his wife. In Mali the figure is nearly 70%... In South Asia only a third of women are in the labour force; in the Middle East and north Africa, only a fifth are. Since 1990 the share of labour income that accrues to women has risen from 35% to 44% in liberal France; in patriarchal Pakistan, from 1.5% to a still-woeful 9%. Removing the barriers to women working would raise income per person by a fifth in many countries, estimates the World Bank—a bigger economic benefit than avoiding a typical civil war...

Yet even the most sexist laws can be scrapped, as Saudi Arabia has shown. Before a series of reforms that started in 2011, women there were barred from all but a handful of jobs and not even allowed to drive. Now they are free to work, drive and shun the hijab if they choose. The share of women in the labour force has nearly doubled since 2010, from 18% to 34%. That is startling progress for a kingdom many thought hopelessly stuck in the past—even if there is still a long way to go.

See also this. 

10. Nvidia is the central bank of AI?

Over the past three years it has pledged over $70bn in investment in startups and offered $300bn in financial support to its customers... It has promised around $25bn in future equity investments. It owes around $33bn in debt. Its potential liabilities to customers amount to about $300bn, but only come into play in a downturn and so do not appear on its balance-sheet. These include the $105bn guarantee behind Open­AI’s data centre; as much as $125bn through the Wall Street partnership; and around $67bn in other backstops.

Also this

Nvidia’s financial engineering is partly a response to its biggest customers’ transformation into rivals. “Hyperscalers”, tech giants such as Amazon, Google, Meta and Microsoft, account for roughly half of Nvidia’s revenue. This year they are projected to invest around $800bn, largely on AI infrastructure. But most of them have begun designing their own chips, which puts their future purchases from Nvidia in doubt. For the hyperscalers, these custom chips are much cheaper, costing between a fifth and a third as much as Nvidia’s...
Hyperscalers have investment-grade credit ratings, which keep their borrowing costs low. Upstart neoclouds have similar spending needs, but little revenue. Their loans are naturally much more expensive. Alphabet, Google’s parent company, sold $2.75bn of 50-year bonds in November, at an annual interest rate of 5.7%. The rate at which CoreWeave, the biggest neocloud, borrowed $2.6bn in July was almost double. It is this gap, between hyperscalers’ borrowing costs and everyone else’s, that the bank of Nvidia would like to narrow. One way it does that is by taking equity stakes in startups that will be customers themselves or that will help fuel demand for Nvidia’s chips indirectly. Last year Nvidia made about 90 such investments, nearly twice as many as two years earlier. This year it has already agreed another 60-odd. 

Some of these cheques aim to propagate open-weight AI models, which users can download free of charge and adapt, unlike proprietary offerings from firms like Anthropic, OpenAI and Google, which users tend to access via subscriptions and whose inner workings are hidden. In August Nvidia agreed to pay Poolside, a startup building AI coding models, $6bn to license its software and a further $1bn for a stake. It has also agreed to buy Hugging Face, a platform hosting open-weight models, for $12.9bn. The intention behind such investments is to fuel demand for Nvidia’s chips by creating a proliferation of AI products and companies that are independent of the hyperscalers... In early July it announced a new stratagem in which it promises to top up neoclouds’ income from new data centres to an agreed floor. These undertakings, the exact terms of which vary from deal to deal, often last for six years. Throughout that period, Nvidia promises to pay a set price for “compute”, as the jargon has it. If the neocloud manages to sell the capacity in question at a higher price, Nvidia receives a share of the difference. This safety-net makes neoclouds’ future revenues much more predictable and so lowers the cost of the debt they take on to build new data centres. That, in turn, spurs demand for Nvidia’s processors.

In the graphic below, red are neoclouds, yellow are AI labs, and blue are financial firms. Also, the dashed circles are equity stakes, and the black boxes indicate guarantees and purchase commitments. 

But things may still be under control.
Morgan Stanley, an investment bank, reckons Nvidia’s “all-in” debt will rise from $53bn early next year to $200bn by the beginning of 2029 as guarantees come into effect. But that is offset by a stash of cash and liquid securities currently worth $99bn, and a business that will generate about $200bn in cash this year. Only a cataclysmic downturn that caused all Nvidia’s guarantees to come due and its profits to evaporate almost entirely would imperil the company—as things stand. The picture may change, however, if Nvidia’s commitments keep growing.

See also this. 

11. Friendships across classes matter for life outcomes. 

Recent research suggests... having pals across class boundaries appears to be one of the strongest predictors of upward mobility for people in low socio-economic groups... What’s more, children who grow up in areas with more cross-class mixing go on to earn more on average, controlling for parents’ income. To isolate the effect of the county itself, the researchers tracked families who moved. Assuming those moves were not related to their children’s future prospects — a reasonable assumption — the analysis found that people who spent a larger portion of their childhood in a better-connected county went on to earn more.
12. The graduate premium is reversing in US and UK.
13. The Indian space ecosystem is a reform success.
India’s space ecosystem has expanded significantly, with more than 450 space industries and over 440 startups now engaged in the sector. Isro is facilitating greater private-sector participation through the government-owned, company-operated (GOCO) model, under which private industry can manufacture, test and supply components and subsystems using its own facilities and infrastructure. Isro has facilitated nearly 440 technology transfers so far, enabling wider adoption of space technologies.

14. The victory of the far-right Alternative for Germany (AfD) in the Saxony-Anhalt province in the east of Germany was expected. Though it has fallen short of a majority by just three seats, an FT editorial calls for allowing it to form the government.

The firewall, a well-intentioned policy of non-cooperation with the far right, which is considered a threat to democracy, has turned into a trap for the mainstream parties, particularly the Christian Democratic Union of Chancellor Friedrich Merz. As support for the CDU shrinks, it is forced to share power invariably with its leftwing opponents in dysfunctional coalitions, whose quarrelling and meagre results drive votes to the AfD, further reducing the scope for compromise between the centrist parties. The firewall has failed to stem the AfD’s advance and is probably furthering it. The alternatives, though, are all bad given the far right’s current strength... 

The least bad outcome there would be for the party to take power with the backing of the Bündnis Sahra Wagenknecht (BSW), a small leftwing nationalist movement that rejects the firewall approach. An AfD regional government would lack the powers to enact some of its more outlandish policies, such as abolishing the right to asylum or renewing energy imports from Russia. To be sure, it could be an extremely uncomfortable time for Germans of immigrant backgrounds and other minorities living in the state. But extra vigilance from the courts and civil society could help to keep a far-right regional government in check. The far right would pose less danger in power regionally than nationally and executive responsibility could deflate its support. In any case, its opponents lack the seats to form an alternative majority. To try to do so would look undemocratic, given AfD’s vote share, and could backfire electorally.

15. Despite all its ubiquity, India's media and entertainment industry is a small revenue earner in proportion to its size.

Last year, IT accounted for 7.3 per cent of India’s GDP, against 0.8 per cent from M&E. The figure is 7 per cent for the US and 4.6 per cent for China... At $32 billion in revenues, the Indian M&E business is abysmally small. It is about a third the size of the Walt Disney Company or roughly equal to that of Tata Consultancy Services. Given the numbers, almost 700 million smartphone users, 650 million television viewers, and 421 million newspaper readers — the size of the firms in any of these segments doesn’t even scale up to Indian standards, let alone global ones... There are only two large media firms with any scale — JioStar and Google India — both at roughly $4 billion in top line. For a country that loves to chat and debate, there is no news brand that has found traction elsewhere. Ninety per cent of all that is watched in theatres, on TV or streaming is Indian stories. Yet there is no global entertainment firm of any heft from India... there is talk about Indian cinema’s soft power globally. But our presence in the global market is a blip compared with, say, Hollywood or Korea. The Indian movie business has been stuck at $1.5-$2 billion in domestic revenues for years. Indian studios simply do not have the money or distribution heft to attempt full-fledged global releases. It is only when the domestic market hits $10 billion or more will you have Indian studios that can have the strength and appetite to go global.

16. This contradicts the oft-repeated claim that a generous social safety net has made Europe a region of shirkers.

17. Huw van Steenis channels Charles Goodhart on the importance of practical wisdom in monetary policy.

Goodhart once put it to me, “every Monetary Policy Committee should have members who have a real-world understanding of the plumbing of financial intermediaries”. In my shorthand: the PhDs need the plumbers.

18. The latest PISA school test scores, where Swedish student scores declined, draws attention to the debate on the country's decision to encourage private schools. Contrary to public perception, Sweden has gone the farthest among continental European countries in privatisation of schools, healthcare, and elderly care, through a series of reforms in the 1990s and 2000s. 

About one in five Swedish children now goes to an independent school... This week’s scores in the international Pisa survey revealed the country’s worst-ever rankings of levels of reading, maths and science of 15-year-olds... The Swedish system is as distinct as it is extreme. Unlike most countries with private schools, Sweden’s system is meant to be egalitarian — so the schools are open to all, through the same free system as state-funded institutions. The private schools receive funding from the state in a voucher system that means they get the same amount of money per pupil as state schools, but can make profits from it if they run things efficiently.

19. Chinese exports have been growing faster than world imports since the turn of this decade. 

20. Finally, an excellent long read on how Javier Milei is taking deregulation to boost Argentina's oil and gas and mining sectors. 

Friday, June 19, 2026

The quartet of global imbalances

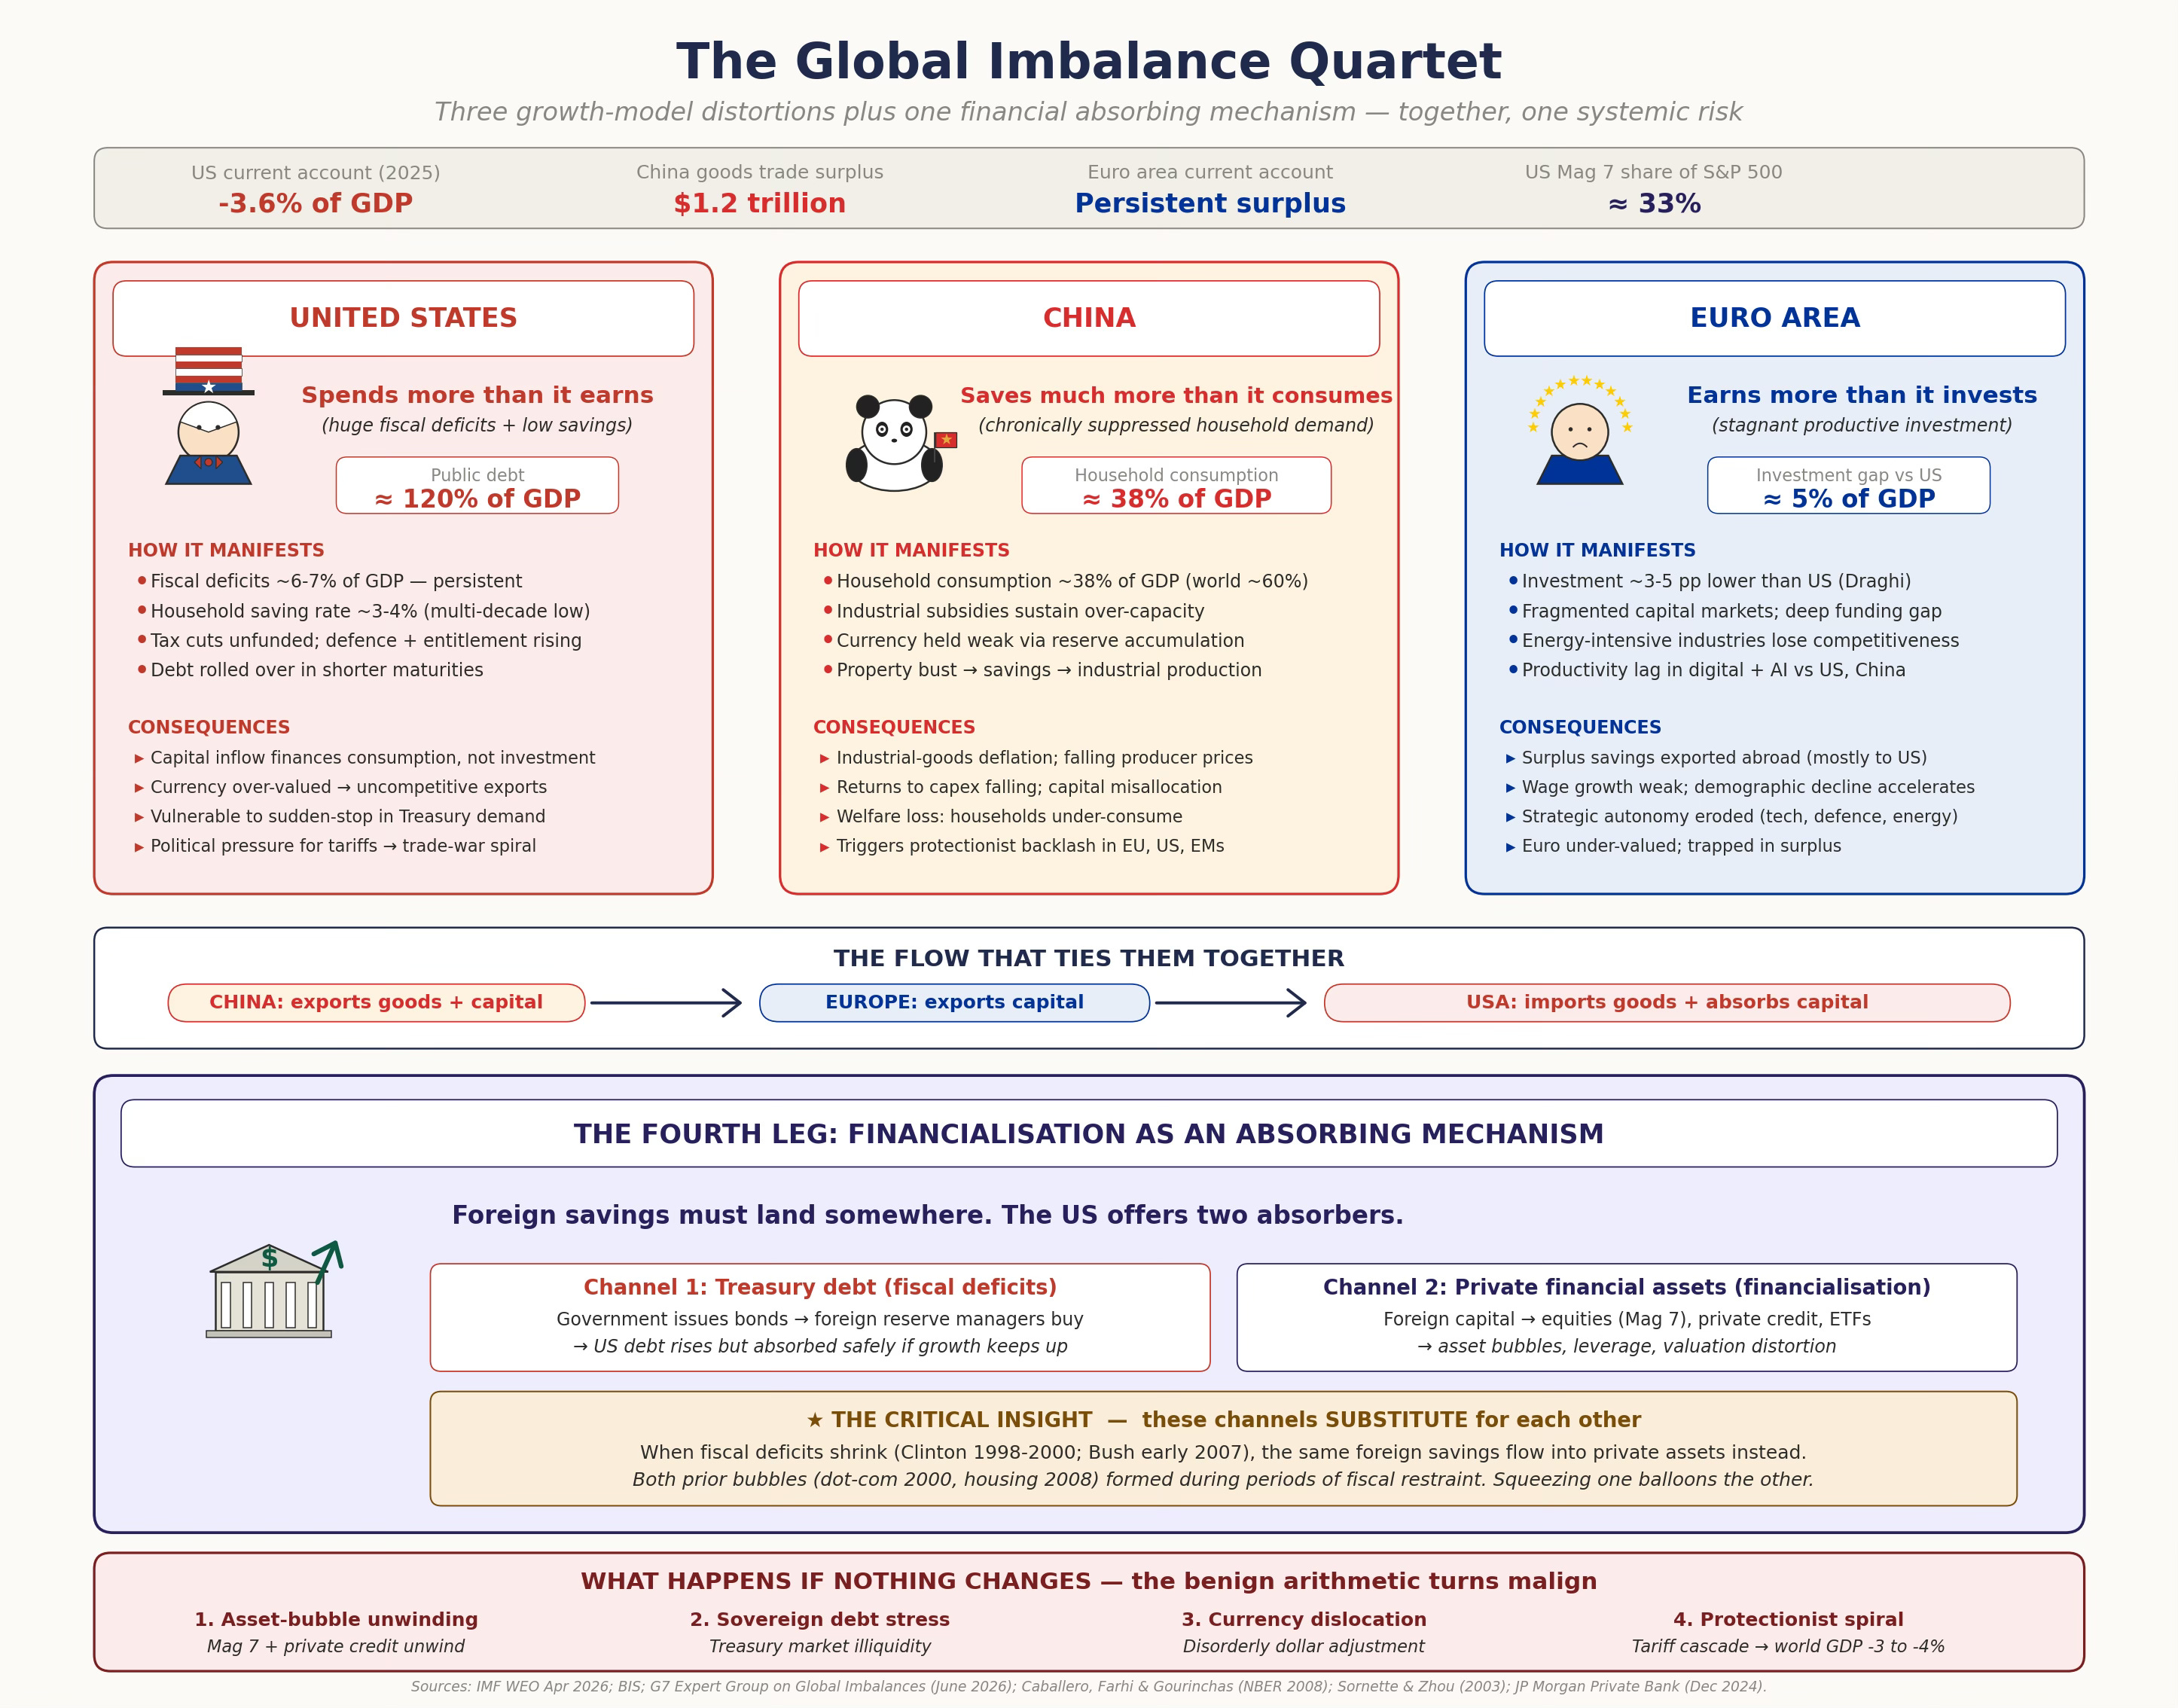
President Donald Trump’s single-minded pursuit of rebalancing the US economy using tariffs is unlikely to yield much without addressing fundamental distortions that have crept into the US economy and financial markets. Trade surpluses are a mere symptom of deeper malaises. I had blogged about the global twin structural imbalances, arguing that an American economy skewed towards consumption and a Chinese one skewed away from consumption are two sides of the same coin. 

Helene Rey (see also this report to G7) has a very nice summary of global imbalances, where she locates it within the dynamics of saving and investment, and questions the focus on tariffs.

A country that saves more than it invests lends abroad and runs a current account surplus; one that invests more than it saves borrows and runs a current account deficit. It is the collective saving and investment decisions of a country’s households, companies and government that drive imbalances. There is now some agreement — crystallising in the G7 discussions — that the sources of imbalances are linked to unbalanced growth models and mostly made at home: chronically weak consumption in China, feeble productive investment in Europe and outsized fiscal deficits in the US. Tariffs are not an effective mechanism to change any of those and issuing an international currency is no justification to run current account deficits. 

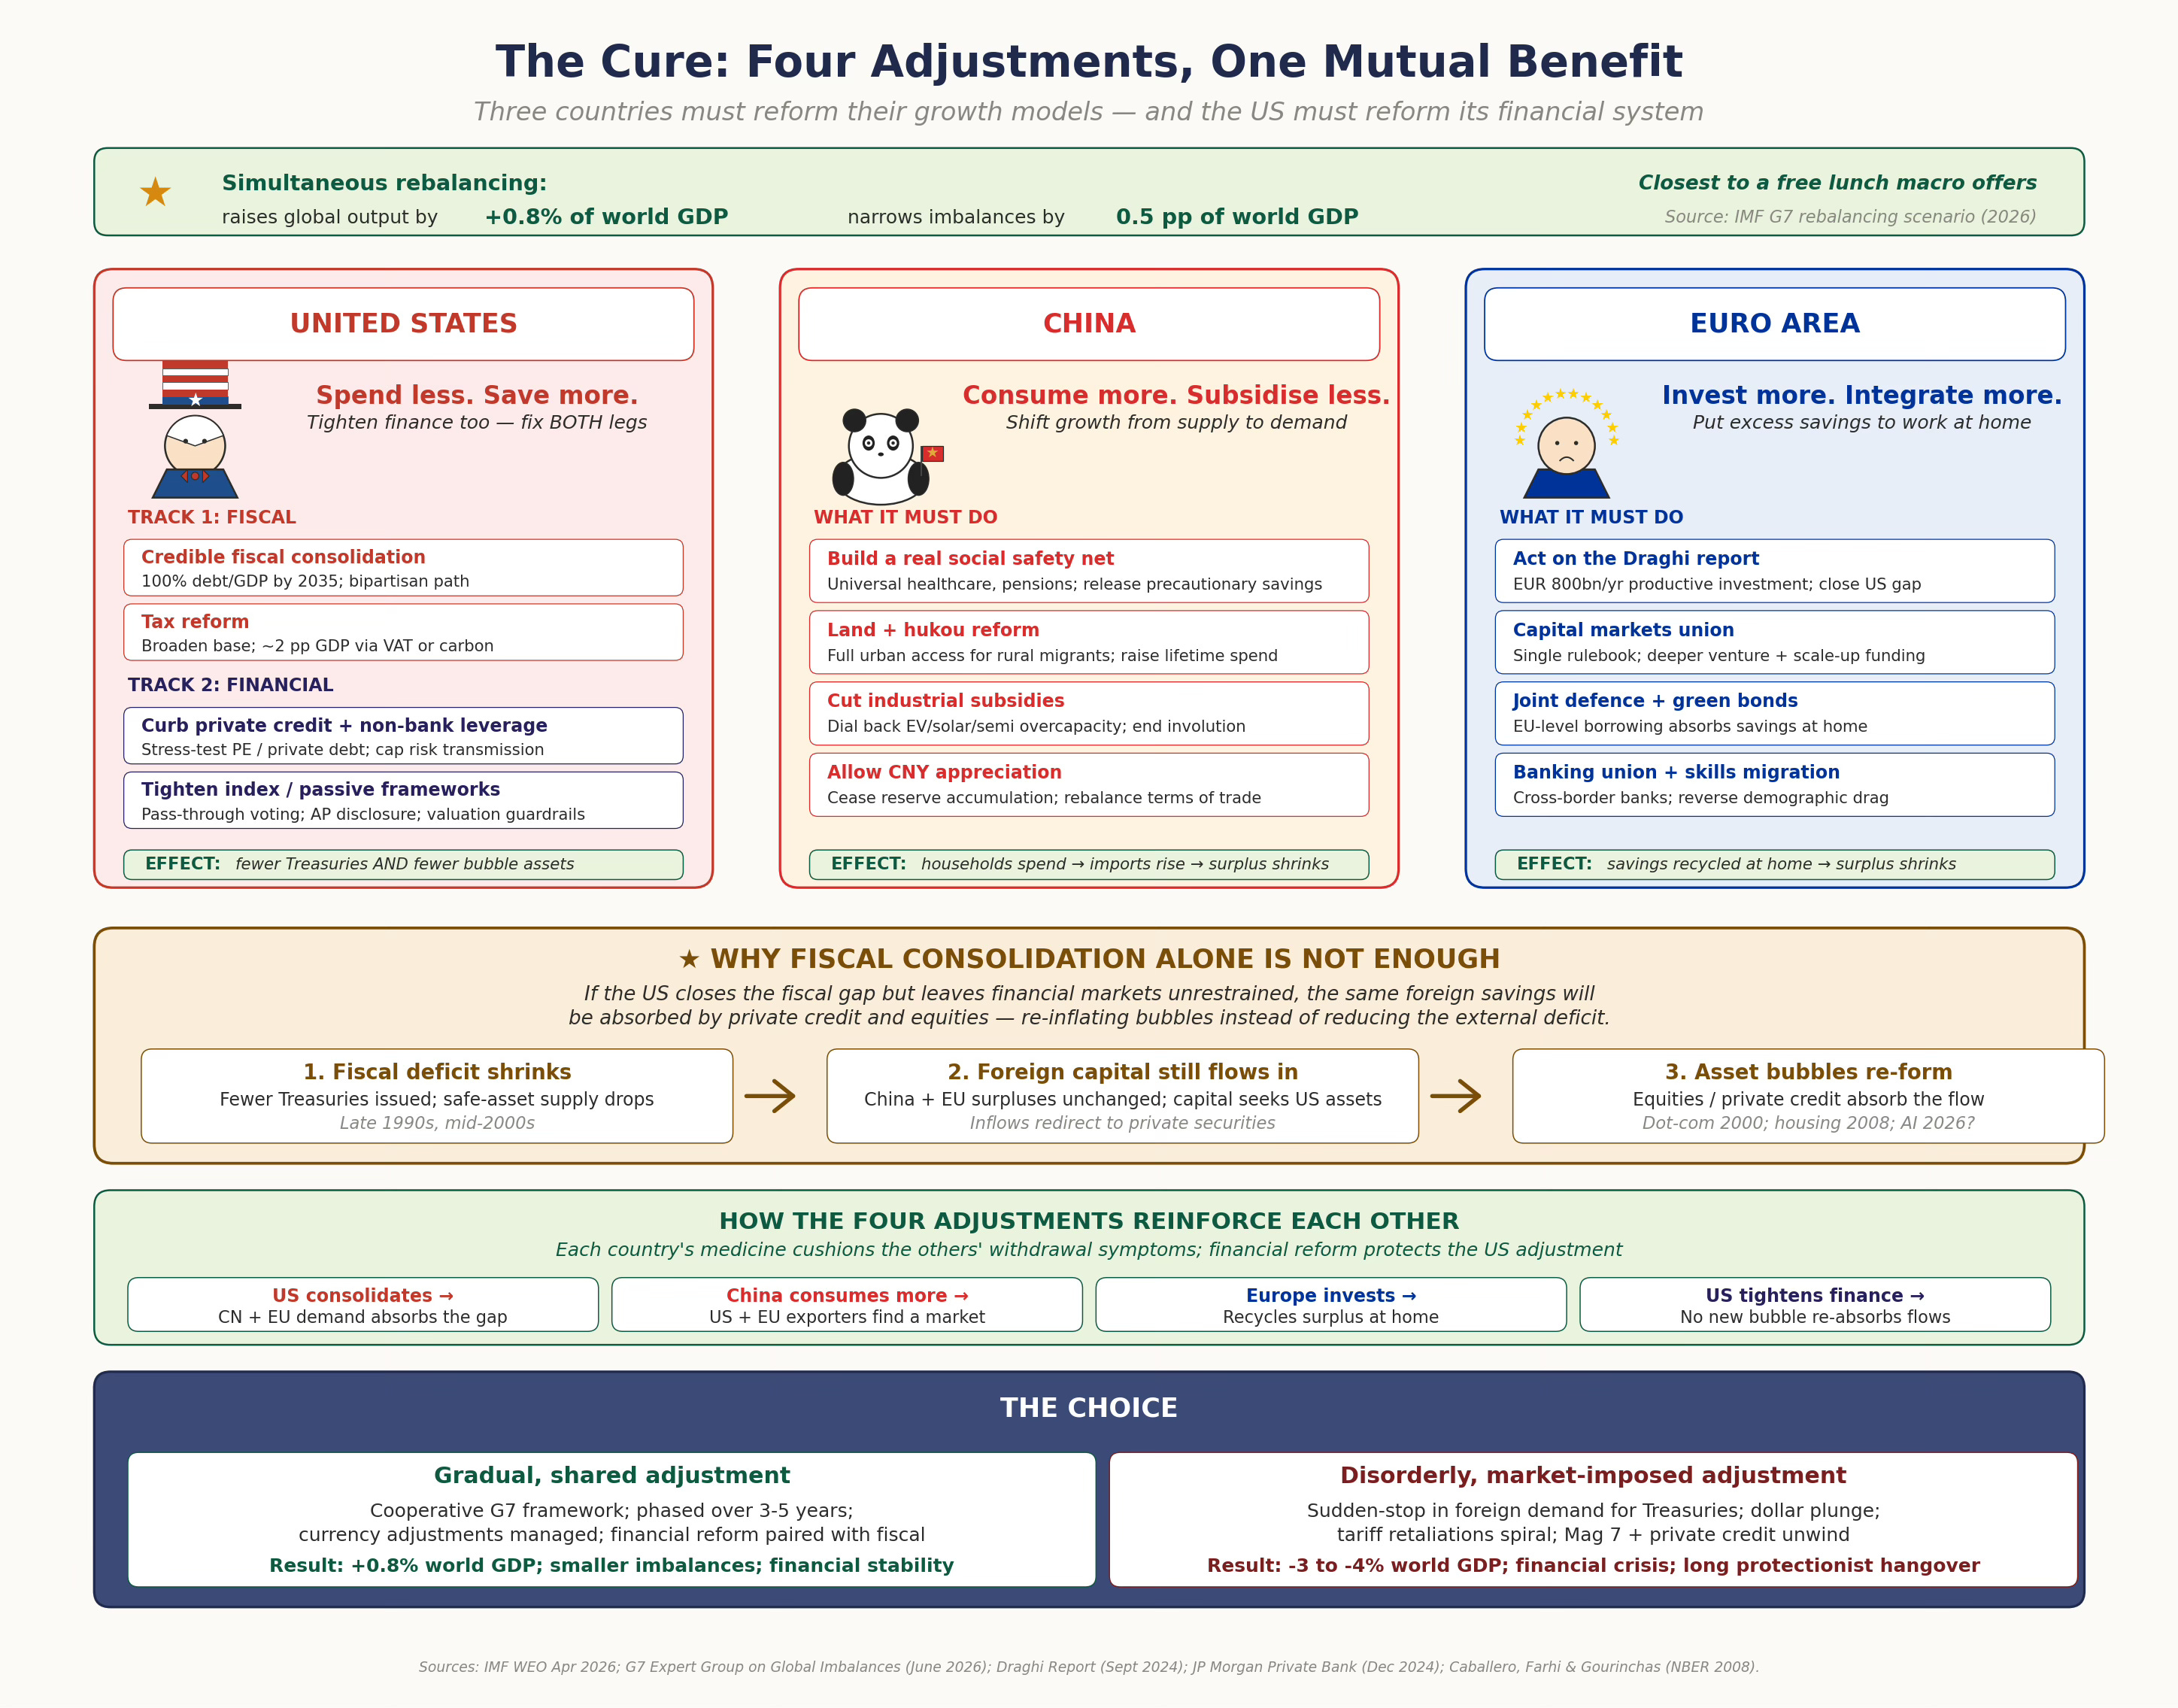
She also proposes the solutions in terms of complementary actions. 

China rebalancing towards consumption, Europe lifting productive investment and America repairing its public finances are not three grudging favours. They are parts of a single, mutually reinforcing policy. One country’s exports are another’s imports; one country’s capital outflow is another’s inflow. When all three move at once, each adjustment cushions the others: the deficit country that consolidates finds external demand waiting as surplus countries spend more at home, and the surplus country that stimulates demand finds a market at home rather than a protectionist wall… The IMF’s scenario of simultaneous rebalancing raises global output by around 0.8 per cent and narrows medium-term imbalances by half a percentage point of world GDP.

I think this analysis misses a critical fourth leg of the imbalance, financialisation. It cannot be seen as merely a symptom of US borrowing. As evidence, there are two natural experiments. The last two episodes of US fiscal deficit reduction (in the late nineties and mid-2000s) were accompanied by financial market bubbles (the dot-com bubble and housing and mortgage market bubble). 

Underlining this, Ricardo Caballero, Emmanuel Farhi, and Pierre Olivier Gourinchas have shown that if the financial markets do not work well, the economy might accommodate investments that deliver a rate of return that is below the growth rate of the economy. In this situation, both stock market bubbles and government debt can play the useful role of displacing inefficient investments. 

Foreign savings flowing into the US must find a US asset to absorb them - either Treasury debt (the fiscal deficit channel) or private financial assets (the financialisation channel). These two are substitutes, not complements. Squeezing fiscal deficits without restraining private credit pushes the same global savings glut into asset bubbles. So US fiscal consolidation alone is not sufficient, and must be paired with financial-sector reform that prevents the likes of private credit from filling the void.

I asked Claude to generate a graphic that describes the global imbalances quartet. 

So, how to address these imbalances?

The rebalancing would require global diplomacy and coordination to mobilise support from all key stakeholders. This looks onerous in a deeply polarised world, of rising tensions between the West and China and the unpredictable and whimsical nature of the Trump Presidency. 

In fact, among the four adjustments required, interventions pertaining to the much-derided Euro area appear to be the most promising and likely to materialise. In fact, on investments, the train has already started. 

It is possible that a deep crisis on the economic front, a very likely near to medium-term possibility in either case, may force both China and the US to rebalance towards consumption and consolidation, respectively. However, there are daunting political economy challenges to be overcome in both countries, especially the US. 

It is the fourth leg that might prove the most challenging. The financial markets are where the power of entrenched interests is so strong that it might require a counter-revolution to upend the order and regulate financial markets more tightly. This will also require global coordination and collective action, and not mere reforms at the US front. 

Saturday, June 13, 2026

Weekend reading links

1. Ruchir Sharma goes behind the record corporate profits share of GDP in the US (11% of GDP, up from 7% in the 1990s) and finds two problems. One, the share is boosted by the lower corporate tax rates which translate into higher fiscal deficits.

Lately the US deficit has risen to more than 6 per cent of GDP and a deficit that high reflects a large transfer of income to households and corporations. Under a well-established accounting formula, the Kalecki-Levy Equation, corporate profits are in part a mirror image of the government’s deficit. Based on this framework, deficits were the single largest contributor to the increase in earnings as a share of GDP since the late 1990s. And in this decade, deficits have accounted for more than half of corporate profits, twice the level of the dotcom era. Strip away government support, and US profits look less extraordinary.

Second, the share falls sharply when we include the universe of private companies.

Since the dotcom bust in 2000, the number of publicly listed businesses has fallen by half, with many new companies remaining private for longer, funded by private equity and venture capital. This is the new home of excess and weak earnings. As a result, the profit growth of the average business listed in standard indices provides a misleading picture of the overall economy. Profit growth has been less impressive once the private companies are included in the data. Further, private firms planning to go public are much larger and less profitable today than in the 1990s. The biggest names in the IPO pipeline, including SpaceX, Anthropic and OpenAI, have little to no profits.

2. Britain's much-delayed HS2 railway project's cost has increased by another £20bn to £102.7bn (a range of estimates ( £87.7bn to £102.7bn in 2025 prices) and will be completed only by the 2040s, with the first trains not expected till 2036. 

3. Why has oil not hit $150 or $200 despite about 12-15 mbpd being taken out?
One of the biggest surprises for the oil market has been China, the world’s largest importer. It slashed inbound shipments by almost 40 per cent in May compared to last year’s average, according to Vortexa Ltd. The reduction is enough to offset anywhere between a third and a fifth of the barrels lost to the war, depending on the estimates used. At the same time, the US has emerged as the world’s most important swing supplier since launching strikes on Iran in late February. American crude and fuel exports in May were more than 2 million barrels a day higher than the average for all of last year. Other emergency measures have also eased the strain. Governments around the globe coordinated a historic release of strategic reserves, while Gulf producers rerouted shipments through alternative export routes. Some tankers continued moving cargoes via the strait despite the risks, using increasingly opaque methods to avoid military threats... Saudi Arabia’s East-West pipeline shipped millions of barrels a day to the Red Sea, while the United Arab Emirates has been piping barrels to the port of Fujairah outside the gulf.

And this is important. 

Another factor keeping a lid on prices has been Trump’s relentless jawboning, making it hard for even the most bullish traders to hold long positions for prolonged periods of time. Open interest in Brent crude futures is the lowest since August as elevated market volatility forces traders to roll back risk exposure. Steep price drops on the prospect of peace have pushed many oil bulls to the sidelines, leaving them to hold small positions for very limited periods of time, several traders said. The lack of risk-taking has helped keep a lid on financial flows, while supply levers have averted the worst hit to the market. The question now, is whether that can last without a peace deal.

4. The evidence to date points to widespread AI use not translating into anything proportionate in terms of business value creation. Sample this from the software industry pointed out by John Burn-Murdoch. 

5. EU energy subsidies during the Ukraine invasion and spike in gas prices. 

Between late 2021 and mid 2023, EU countries spent about €540bn on subsidising energy prices to protect consumers from price shocks in the aftermath of Russia’s full-scale invasion of Ukraine and to cushion energy-intensive industries from soaring costs. Of that total, €158bn was accounted for by Germany, whose industry heavily depended on Russian gas supplies. In the wake of the Ukraine energy shock, Brussels also relaxed state aid rules for the rest of the decade to allow governments to subsidise clean technologies and industrial decarbonisation.

6. Emerging AI-related roles in the software industry.

Agent engineers who build and fine-tune agents; architects who determine how humans and agents divide tasks; AI governance specialists who keep agents compliant and accountable; AI transformation advisors who help enterprises navigate workflow reimagination; solution designers who translate business problems into agentic solution architectures; and AI assurance partners who help clients govern their own AI deployments.

7. Rana Faroohar makes the point that we may be at the cusp of a new investment super-cycle driven by the combination of AI, clean energy, defence, and manufacturing.

In a recent issue of his TPW Advisory Monthly report, investor Jay Pelosky did just that, collating data on AI, clean energy and defence spending around the world from sources including Gartner, BloombergNEF (on energy), the Stockholm International Peace Research Institute and the International Institute for Strategic Studies (on defence) and others. So far, $6.9tn was spent globally in 2025 in the three areas, and the number will probably reach $10tn by the end of this year and $16tn by 2030. 

What’s more, says Pelosky, these three areas reinforce one another, amplifying potential investment. AI requires more energy. The move towards tech sovereignty in the US, China and even Europe (in a nascent way) adds to the need for investment in AI and energy, while the move towards a more 19th-century “spheres of influence” geopolitics calls for greater defence spending globally. Add to this the desire of policymakers in all three regions to increase resilience in critical sectors affected by concentration or globally dispersed supply chains: products such as advanced semiconductors, active pharmaceuticals and lithium batteries, for example.

8. Rupee trajectory over the last two years

The rupee depreciating by nearly 6 per cent against the dollar in the first five months of 2026 alone, exceeding the combined full-year declines recorded in 2025 (5 per cent) and 2024 (2.8 per cent). The rupee touched a record intraday low of 96.57 per dollar on May 19 and has lost roughly 14 per cent of its value against the greenback over the past two years. Against the euro, the erosion has been equally stark, with the Indian currency declining by more than 7 per cent over the past 12 months and nearly 16 per cent in the past two years, he added.

The problem with a depreciating rupee is that foreign investors now must earn an extra 14% over the last two years to offset the depreciation.

9. India's FTAs may be creating a perverse incentive for even domestic manufacturers due to the inversion of duty structures.

Many finished goods now enter India at low or zero duty from partners such as ASEAN, Japan, South Korea, the UAE and Australia. As a result, Indian manufacturers often pay high duties on imported inputs, especially those sourced from non-FTA countries, while competing against finished products imported duty-free under FTAs. For example, steel and aluminium attract MFN duties of 7.5-10 per cent, but machinery, industrial equipment and engineering products made from these materials can enter India duty-free under several FTAs. Indian manufacturers, therefore, face higher input costs when competing with tariff-free imported machinery produced with globally priced inputs.

Similar distortions exist in chemicals, plastics, rubber and textiles. Duties on inputs such as caustic soda, soda ash, polypropylene, PVC and SBR raise production costs. At the same time, many finished products in these sectors can be imported at low or zero duty... the growing incentive for firms to manufacture outside India rather than within it. When raw materials and components attract duties in India, but finished products can be imported duty-free from FTA partners, companies may find it more profitable to locate production abroad and export back to the Indian market. In such cases, FTAs effectively encourage offshore manufacturing at the expense of domestic value addition. ASEAN countries are increasingly becoming manufacturing hubs for supplying the Indian market.

10. The Gulf War has resulted in a surge in Chinese exports of solar panels, especially to South East Asian and African countries. This came at a time when many Chinese firms laden with excess capacity, low margins, and large indebtedness were facing an existential crisis. 

11. The revival of manufacturing in the US hits the wall of labour scarcity.

Perhaps the largest problem for would-be reshorers is a lack of labour. Despite widespread nostalgia for manufacturing jobs, new US factories often struggle to find reliable workers. When Japanese group Panasonic started producing electric vehicle batteries near Reno, Nevada in 2017, the company suffered more than 100 per cent annual turnover in its early years. Not only were employees reluctant to take jobs in an access-controlled, sterile environment, but every November, the group would lose workers to seasonal logistics jobs at nearby Amazon facilities that paid a similar wage... Despite political enthusiasm for reviving manufacturing, jobs posted on LinkedIn receive fewer applications than other sectors it competes with, such as technology.

12. More on the SpaceX bubble.

Goldman Sachs, the investment bank leading the IPO, projects that SpaceX’s AI revenues need to increase 100-fold by 2030, reaching $322bn from $3.2bn today. But its AI lab remains far behind Anthropic, Google and OpenAI at the frontier, and shows little sign of catching up. Morgan Stanley also estimates that overall revenue needs to increase 180-fold to $3.4tn by 2040, up from $18.7bn last year. Earnings must flip from a $4.9bn loss in 2025 to $2.7tn.

SpaceX ends the first day of trading at 20% premium on its $135 listing price, which raised $75 bn and left it with a valuation of $2.1 trillion. The listing prospectus claimed at $28.5 trillion addressable market.

SpaceX plans to use the IPO proceeds for a range of ambitious projects, from its skyscraper-sized reusable Starship rocket, founding a 1mn-strong colony on Mars, starting a lunar economy to building a network of orbital AI data centres capable of delivering vast amounts of computing capacity... A portion must also go towards repaying a $20bn bridge loan the group took out in March to back its merger with Musk’s lossmaking AI start-up, xAI, and social media platform X.

This is staggering. 

It also hands Musk a vast financial windfall, with his 42 per cent stake in SpaceX valued at more than $800bn. Combined with his $280bn holding in electric vehicle maker Tesla, his wealth has now surpassed $1tn, equivalent to about a third of the market value of the UK’s FTSE 100 index.

Richard Waters explains the rationale driving the astronomical valuation.

It is hard to find changes in SpaceX’s business prospects that account for a fourfold valuation jump within the space of a year. Rather, it is testament to Musk’s unrivalled grip on the public imagination, transmuted into Wall Street gold. When the history of SpaceX’s record-breaking IPO is written, it will go down as a textbook case of Musk’s ability to conjure a compelling vision of the tech future for both Silicon Valley and Wall Street, ably backed by an army of promoters in the financial world. (With fees estimated at about $500mn, it’s probably not surprising that there were few warnings from the Wall Street establishment that the shares might be overvalued.)... 

Musk has been busy in recent months spinning up new visions capable of embellishing his company’s prospects... What starts out sounding like science fiction fantasy doesn’t take long to seem not only plausible but even downright likely. Wall Street has been more than willing to translate Musk’s tech dreams into financial projections capable of supporting the sky-high valuation, implausible as those numbers may seem. Goldman Sachs, the lead bank on the IPO, predicted that revenue would soar to $474bn by 2030, most of it from AI...
The IPO involved only about 4 per cent of SpaceX’s shares, but a high level of demand was built in, partly because some index investors will soon be required to add the company to their portfolios. Even without the index funds, SpaceX’s sheer size — at about 2.5 per cent of US stock market capitalisation — has made it too big for many investment managers to avoid.

13. South Korean capitalism is spreading wealth around

Samsung Electronics... agreed last month for employees to share the chipmaker’s blockbuster profits from an AI-led boom... SK Hynix... handed employees a similar profit-sharing deal last year... Samsung is also going to give Won500mn loans at low rates to employees... Samsung and SK Hynix together control much of the market for the advanced memory chips used in AI servers. Employees at both companies are in line for average annual bonus payouts of Won600mn, which compares with a national average salary of about Won50mn... district of Hwaseong... expected to gain corporate income tax receipts of Won1tn to Won1.3tn from Samsung alone this year, an extraordinary sum for a city authority whose annual budget is about Won3.5tn.

14. Germany amps up spending on its ailing railways sector, where on-time arrivals of long-distance trains have fallen from 84% two decades back to 60%. 

By the end of 2026, Deutsche Bahn will have rebuilt 900 kilometres of train lines since 2024, close to a quarter of its 2036 target. That is equivalent to half of the roughly 1,900 kilometres of new lines built after 1945. Flix, which started as a coach operator but also runs long-distance trains, has earmarked €2.4bn for up to 65 new high-speed trains that it plans to roll out from 2028. Italian high-speed train operator Italo also has ambitions for Germany, promising up to €3.6bn of investment in new trains if it gets multiyear access to the network.
 

Saturday, June 6, 2026

Weekend reading links

1. Potato glut hits Europe, and in particular Belgium.
Europe faces a surplus of five million metric tons of the type of potato used for fries. For months, the price of a metric ton of potatoes on the spot market in Belgium, the world’s biggest exporter of frozen fries, has languished at precisely zero. It was nearly 600 euros ($690) three years ago.

2. The Murugappa Group (through Axiro Semiconductors and CG Semi), the Tata Group (through Tata Electronics), and Crystal Matrix are leading India's semiconductor chip design and manufacturing push. 

3. Very good assessment of a decade of the IBC law.

The idea was to enable timely exit of non-viable firms, preserve viable businesses, restore credit discipline, and unclog credit channels... Till March 2026, 1,419 companies had emerged from insolvency with approved resolution plans, with the proportion of companies achieving such outcomes improving steadily... Creditors have realised ₹4.32 trillion through resolution plans. The oft-cited haircut of around two-thirds, measured against admitted claims, can be misleading because claims are frequently inflated while asset values are deeply eroded by the time firms enter insolvency. A more meaningful benchmark is liquidation value: Resolution plans have, on average, yielded 167 per cent of the liquidation value. Importantly, firms resolved under the IBC demonstrated operational revival post-resolution. Within five years, sales and capital expenditure nearly doubled, asset utilisation improved sharply, and the aggregate market capitalisation of resolved firms rose from about ₹2.8 trillion to ₹9 trillion... 

In all, 3,003 companies have entered liquidation under the IBC, but most had little realistic prospect of revival. Their assets averaged barely 5 per cent of admitted claims, and four-fifths were already sick or defunct before entering insolvency. The IBC merely provided an orderly exit for firms that had failed long before the process began. Yet, the incidence of liquidations in India is comparable to that in the United States and significantly lower than in the United Kingdom and Australia... Resolution plans rescued 78 per cent of distressed assets, while liquidations accounted for 22 per cent. When all pathways to revival are considered — resolution plans, withdrawals, settlements, appeals, and rescues during liquidation — the number of revived companies substantially exceeds those liquidated.

4. John Burn-Murdoch points to evidence that remote working and NOT AI is responsible for the ongoing declines in entry-level hirings. 

Peter John Lambert and Yannick Schindler have a fascinating counter-proposal: the take-off of remote work. Early-career workers require more supervision than experienced hires, and build important skills, knowledge and social capital by observing and working alongside senior colleagues. Working from home adds friction to these processes, making entry-level workers more costly to bring on board in terms of time and resources and slowing their prospects for promotion. As such, the rise of remote work has worsened the trade-off for hiring entry-level workers, while leaving the calculus for senior hires unchanged. The evidence fits the theory. Lambert and Schindler analysed hundreds of millions of new hires and job postings and found that although both occupational exposure to AI and remote working rates line up with the outsized pullback in junior hiring, the link with AI evaporates once you account for whether a role is remote. In other words, it only looks like AI is behind the hiring crunch for junior software developers because coding jobs are also disproportionately done remotely. Jobs less exposed to AI but amenable to remote work (eg lawyers) have also seen weak junior hiring; roles with high AI exposure but an emphasis on in-person work (eg receptionists) have held up better.
5. Is Steve Jobs leaving the greatest corporate legacy ever?
Apple now rakes in sales of over $1bn a day. Its services business alone, driven by the App Store and Apple Pay, generates more revenue than Netflix, Spotify and Adobe combined, with a margin of around 75 per cent. Under Cook, the company has returned around $1tn to shareholders through dividends and buybacks… Nearly two decades since the product launched, Apple shipped well over 200mn iPhones in 2025 and the device still accounts for about half of Apple’s $400bn of annual sales, with high product margins underpinned by the highly efficient, Asia-based supply chain also created by Cook. Apple’s astonishing profitability is sustained by an annual cadence of new iPhones, each iteration featuring largely incremental improvements on the one before. Research and development spending as a proportion of revenue went from 8 per cent at its height in 2001 to a 2 per cent low in 2012 as the iPhone boom began, meaning that for a while Apple was spending proportionally far less than its Big Tech peers.
6. Good primer on why oil prices have remained less elevated than expected - decline in Chinese oil imports (almost 4 m bpd) and rise in US exports (almost 4.5 mbpd).

7. The US economy is increasingly resembling a one-trick pony of AI.
The US corporate profit share has climbed to a record 13.8 per cent of GDP, while net income margins across the broad US equity market have recovered to about 9.7 per cent, close to earlier highs. At the same time, market leadership has become unusually concentrated: a handful of AI‑linked stocks now account for roughly 40 per cent of the S&P 500’s market capitalisation, according to Bank of America data. Headline profitability is being flattered by a small slice of the economy earning extraordinary returns from the scramble to build AI capacity...
Spending strength is increasingly coming from upper-income households where wealth and income are more tied to equities than wages. The stock market has, in effect, become part of the growth model: rising AI profits lift share prices; higher share prices support the spending power of wealthier households; and that spending helps keep demand alive. Lower-income households, by contrast, are more exposed to squeezed real incomes and softer labour-market momentum... Large technology groups have produced surging revenues and margins with only limited growth in headcount... So long as investors believe AI will earn very high long-term returns, the loop can remain self-sustaining: capital expenditure stays firm, equities stay buoyant and affluent consumers keep spending.

8. The spectacular surge in Google's capex.

Five years ago, its capital expenditure on servers, network equipment and such was $25bn, which it funded out of operating cash flows of $92bn. In 2027, analysts expect $250bn of capital expenditure, versus cash flows of $260bn — a tighter fit. In its second quarter next year, Visible Alpha estimates suggest Google will spend more than it makes, for the first time in its listed history.

9. A good illustration of deficient national security discipline comes from how the US is allowing the exports of tungsten scrap to China even as it spends money abroad buying tungsten mines. 

Since early 2025, Chinese scrap traders have been seeking tungsten throughout the US, prompted by a shortage outside China caused by declining supply and intense demand from the aerospace, weapons and tools industries. The effort has set off a bidding war with American buyers and calls to ban sales of a critical national security resource to overseas buyers... Sellers said they were fielding calls from Chinese buyers looking for the material, while American buyers said they were being outbid by Chinese rivals willing to pay as much as five times the usual price... 

Tungsten scrap commonly comes from worn-out industrial tools such as drill bits and mining equipment. It can be crushed and chemically processed back into tungsten powder or carbide for use in new machinery and tools. The shortage has been triggered by Beijing imposing export restrictions on it and an array of other critical minerals in early 2025 and the country cutting mining quotas. China accounts for more than half of global mined and refined tungsten supply and about half of demand... 

Tungsten is broadly used in military applications, including in bullets and missiles. Traders said stocks were already low before the Iran war and that companies do not typically hold large stores of the metal. There was “no availability” outside China of the so-called “intermediate” products that manufacturers need — mined ore that has been processed... The price of tungsten has risen by more than 200 per cent since May 2025, while tungsten scrap has risen 350 per cent, according to Argus Media.

10. The AI wave is lifting all stocks, including those legacy IT firms like HP and Dell. 

11. India's non-tax revenue fact of week.

In the last three years, the share of RBI surplus in the government’s non-tax revenue has stayed between 42 and 52 per cent.

12. SpaceX IPO in a graphic.

13. Real Madrid at the top of European football club valuations.

14. The universe of PSUs in India has been rising.
15. Rama Bijapurkar's categorisation of India's consumption class.
The important thing is that 93% of households have annual consumption less than $5700.

Last month, Anthropic crossed $47bn in run-rate revenue, a metric used by start-ups which estimates annual revenues based on short-term performance. This is a more than fivefold increase since the start of the year... Anthropic’s valuation has soared from $350bn to $900bn in 12 weeks. It is now one of the fastest-growing companies in history.
17. The biggest threat to the US superpower status now appears to be its surging public debt, which is now $36 trillion held by the public and federal agencies 
The exorbitant privilege has ensured the dollar's status as the world's pre-eminent reserve currency and the Treasury market's role as the world's safest haven asset, thereby allowing the US access to unlimited global capital at a low cost. While there are no competitors to the dollar on the horizon, the Treasury's safe haven status is facing competition. 

18. The most important difference between the dotcom bubble and the AI bubble.
19. Japan is losing people. 
Japan’s population peaked in 2008 at 128 million, and it is projected to fall to 87 million by 2070. The country is now roughly the same size it was in 1989... All but two of the country’s 47 prefectures reported population decreases in 2025, and the rate of decline is accelerating.

20. Finally, this says as much about the Indian stock markets as about the Korean and Taiwanese markets.

India’s stock market capitalisation was overtaken in the past week first by Taiwan and then by South Korea, as the value of Indian equities held by foreign investors slumped to a 10-year low of 7.3tn rupees ($76bn) on June 1. The value of Indian stocks was more than double that of Taiwanese stocks and roughly 3.5 times that of South Korean stocks 18 months ago, analysts at Bernstein said this week. “Fast forward just five months into 2026, and that lead has evaporated,” they added. 

Saturday, May 30, 2026

Weekend reading links

1. This captures the big problems with Chinese exports to Europe.
In the early 1970s workers at Dongfeng, or “East Wind”, imported American trucks to inform their early attempts at making off-road vehicles destined for the People’s Liberation Army. Nearly 60 years later Stellantis, the European owner of the Jeep brand, is partnering with Dongfeng to produce a new battery-powered version of the iconic American light utility vehicle for consumers in China, the Middle East and south-east Asia... International carmakers, struggling for survival amid an expensive transition to electric vehicles, are turning to China’s technologically advanced and cost-efficient factories as manufacturing bases for their global businesses. Foreign companies already account for around two-fifths of China’s car exports to Europe, when joint ventures with local groups are included, according to the Rhodium Group, a US consultancy... Indeed, Volkswagen, BMW, Nissan, Hyundai and others are increasing exports from Chinese factories with spare capacity to markets other than Europe and the US.

2. A new approach to making clean hydrogen. 

Most of the hydrogen the world uses today — mainly for fertilizer and refining — is produced using natural gas in a process that creates lots of emissions. In recent years, the United States and other countries have invested billions of dollars trying to make “green” hydrogen with wind and solar power, but it has proved difficult and expensive. Now a growing number of companies think a better answer could lie underground. Dozens of start-ups are trying to find large reservoirs of natural hydrogen thought to exist below the surface. Others, like Vema, are trying to stimulate the processes that generate that hydrogen, without any emissions. It’s a field often referred to as “geologic hydrogen.”...
Hydrogen is the most abundant element in the universe, and it gets made naturally in the Earth’s crust when certain iron-rich minerals react with water and rust. This process, known as serpentinization, often leaves behind rocks with a mottled green color. For a long time, many geologists believed that any natural hydrogen produced this way was unlikely to accumulate in large underground deposits because the tiny molecules would slip away through cracks in rocks. Lately, that conventional wisdom has been upended... By the 2020s, scientists were publishing papers estimating that natural hydrogen deposits underground could supply the world’s needs for hundreds of years. One promising location was North America’s Midcontinent Rift, an enormous formation of iron-rich basalt that stretches 1,200 miles from Kansas to Michigan... The Energy Department has estimated that geologic hydrogen could be produced for less than $1 per kilogram. That would be cheaper than hydrogen made from fossil fuels and one-sixth the current cost of making hydrogen from wind and solar power.

It has started attracting private capital.

Companies are racing to find the fuel. One of the best-funded start-ups, Koloma, has raised $400 million from investors including Amazon and United Airlines and has drilled exploratory wells in Iowa. HyTerra, an Australian firm, is searching for hydrogen and helium in Kansas and Nebraska. Not everyone thinks the best strategy is to search for natural deposits underground. A better idea, some say, is to create them. In Quebec, a startup called Vema Hydrogen plans to spend the rest of the year injecting water into its underground test wells to see if it can speed up the process of serpentinization that creates natural hydrogen underground... Vema has already raised $15 million and is working to raise more. There are ophiolites all over the Earth, including a ridge stretching from Costa Rica to Alaska, and the company is looking at sites in Oregon and California as well. Other start-ups, including one out of M.I.T. called GeoRedox, are developing their own approaches.

3.  Semiconductor chips are one area where China lags badly.

Chinese companies will most likely make just 2 percent as many A.I. chips as foreign firms do this year, said Tim Fist, a director at the Institute for Progress, a think tank in Washington. The production gap between Chinese and foreign manufacturers is especially big for memory chips, which are essential for the large calculations done by A.I. Companies outside China will make 70 times as much memory storage capacity this year as Chinese chip makers will, Mr. Fist said...The inability to get essential tools from ASML has been a major chokehold for Chinese chip makers. Since U.S. officials led an effort to lobby the Dutch government to block shipments to China, no Chinese company has been able to buy ASML’s most advanced tools. Instead, Chinese chip makers have recruited engineers with experience using those machines at TSMC, the world’s top chip maker. And now, Chinese start-ups are trying to make their own chip manufacturing equipment... China’s A.I. companies are trying to get the computing power they need by strapping together numerous less powerful chips. Huawei has taken such an approach... The chips Huawei does produce are prone to defects and use more electricity than cutting-edge foreign ones.

4. This is one of the greatest messages from a student to a teacher, Albert Camus to his elementary school teacher Louis Germain after he won the Nobel Prize.  

5. Japanification in demographics.
And this impact of smartphones is striking.
6. Soumaya Keynes has a good read on the history of export restrictions and their impact, and why trade wars will endure. 

7. Southeast Asian economies struggle on the face of rising inflation from the War.
Their currencies have weakened.
The Philippines and Indonesia have already raised interest rates. 

This is a good illustration of the extent of damage from the Strait of Hormuz closure.
In a sign of Bab el-Mandeb strait’s strategic importance, Djibouti – whose coastline runs along the waterway – is home to military bases of several major countries, including the US, Italy, France, Japan, and the sole People’s Liberation Army base outside China. The Bab el-Mandeb strait is among several trade chokepoints that, when blocked, require vessels to travel more than 8,000 miles. These also include the Strait of Gibraltar and the Suez and Panama Canals...
The knock-on effects of a blockage can be much more significant where there is no alternative route to fall back on, as with the Strait of Hormuz, the Øresund between Denmark and Sweden, and the Turkish straits, comprising the Dardanelles and the Bosphorus, which act as the gateway between the Black Sea and Mediterranean. With the Hormuz strait, says Jasper Verschuur, co-author of a study into the risks of the world’s 24 narrow straits, “there is no alternative for 80 per cent of the trade”.

This is India's exposure to various maritime routes

9. Sajjid Chinoy writes that India's economic problem is less of a current account and more a capital account problem, arising from the sharp decline in FDI and FPI inflows. In the circumstances, he argues that demand compression can be counterproductive by slowing growth. He suggests a combination of depreciation and augmentation measures for foreign capital inflows.
The objective must be to attract a large-enough quantum of near-term capital inflows across multiple avenues — even if it involves a subsidised swap — to change exporter, importer and investor behaviour, and prevent a destabilising overshooting of the Rupee.

I am not sure how this is at all possible precisely when capital is flowing the other direction.  

10. For all talk of private participations and efficiencies, the long-distance railway networks in continental Europe is largely state-owned - Deutsche Bahn (Germany), Ferrovie dello Stato (Italy), Renfe (Spain), SNCF (France), and SBB (Switzerland). The Economist writes about how Italo, the private high-speed rail operator co-founded by Luca Cordero di Montezemolo, is trying to disrupt the German network. 

11. Securitisation and deepening of financial intermediation in Europe. 

The securitisation market in Europe remains moribund, comprising around 0.3 per cent of GDP compared with 4 per cent in the US.

12. SpaceX's IPO prospectus takes the widest liberties with US securities law. 

13. K-shape in US economy.

And now in wage decline
14. Ukraine's drones are inflicting massive damage and casualties on Russia as the country forces its way into its most favourable situation since the war began.
Some intelligence reports indicate that a staggering 1.2mn Russian soldiers have been killed or wounded since February 2022, a casualty figure no major power has suffered in a single conflict since the second world war... Backed by some €90bn in EU loans, Kyiv is pouring resources into domestic arms production in a bid to reduce dependence on western weapons and the political constraints that often accompany them. It has moved at breakneck speed to scale up the manufacture of land, sea and air drones, artillery systems, electronic warfare equipment, and even ballistic and cruise missiles.

15. The consulting industry is threatened by AI.  

Few industries are debating AI’s implications more intensely than consulting, whose core work of research, summarising data and producing neatly designed PowerPoint presentations is highly automatable. Richard Susskind, co-author of The Future of the Professions, says consultants are more vulnerable than other mainstream professions in part because the work of junior staff “can now be taken on, with mild supervision, by increasingly capable AI systems”. The sector now has two new competitors, he adds: “the AI-empowered client and disruptive start-ups. Both challenge the conventional model.”... AI also threatens one of professional services’ foundational economic models: billing by time. When a bot can review thousands of contracts in minutes and draft complex documents in seconds, the relationship between hours worked and value delivered begins to break down. Increasingly, clients are demanding pricing linked to outcomes rather than labour inputs.

16.