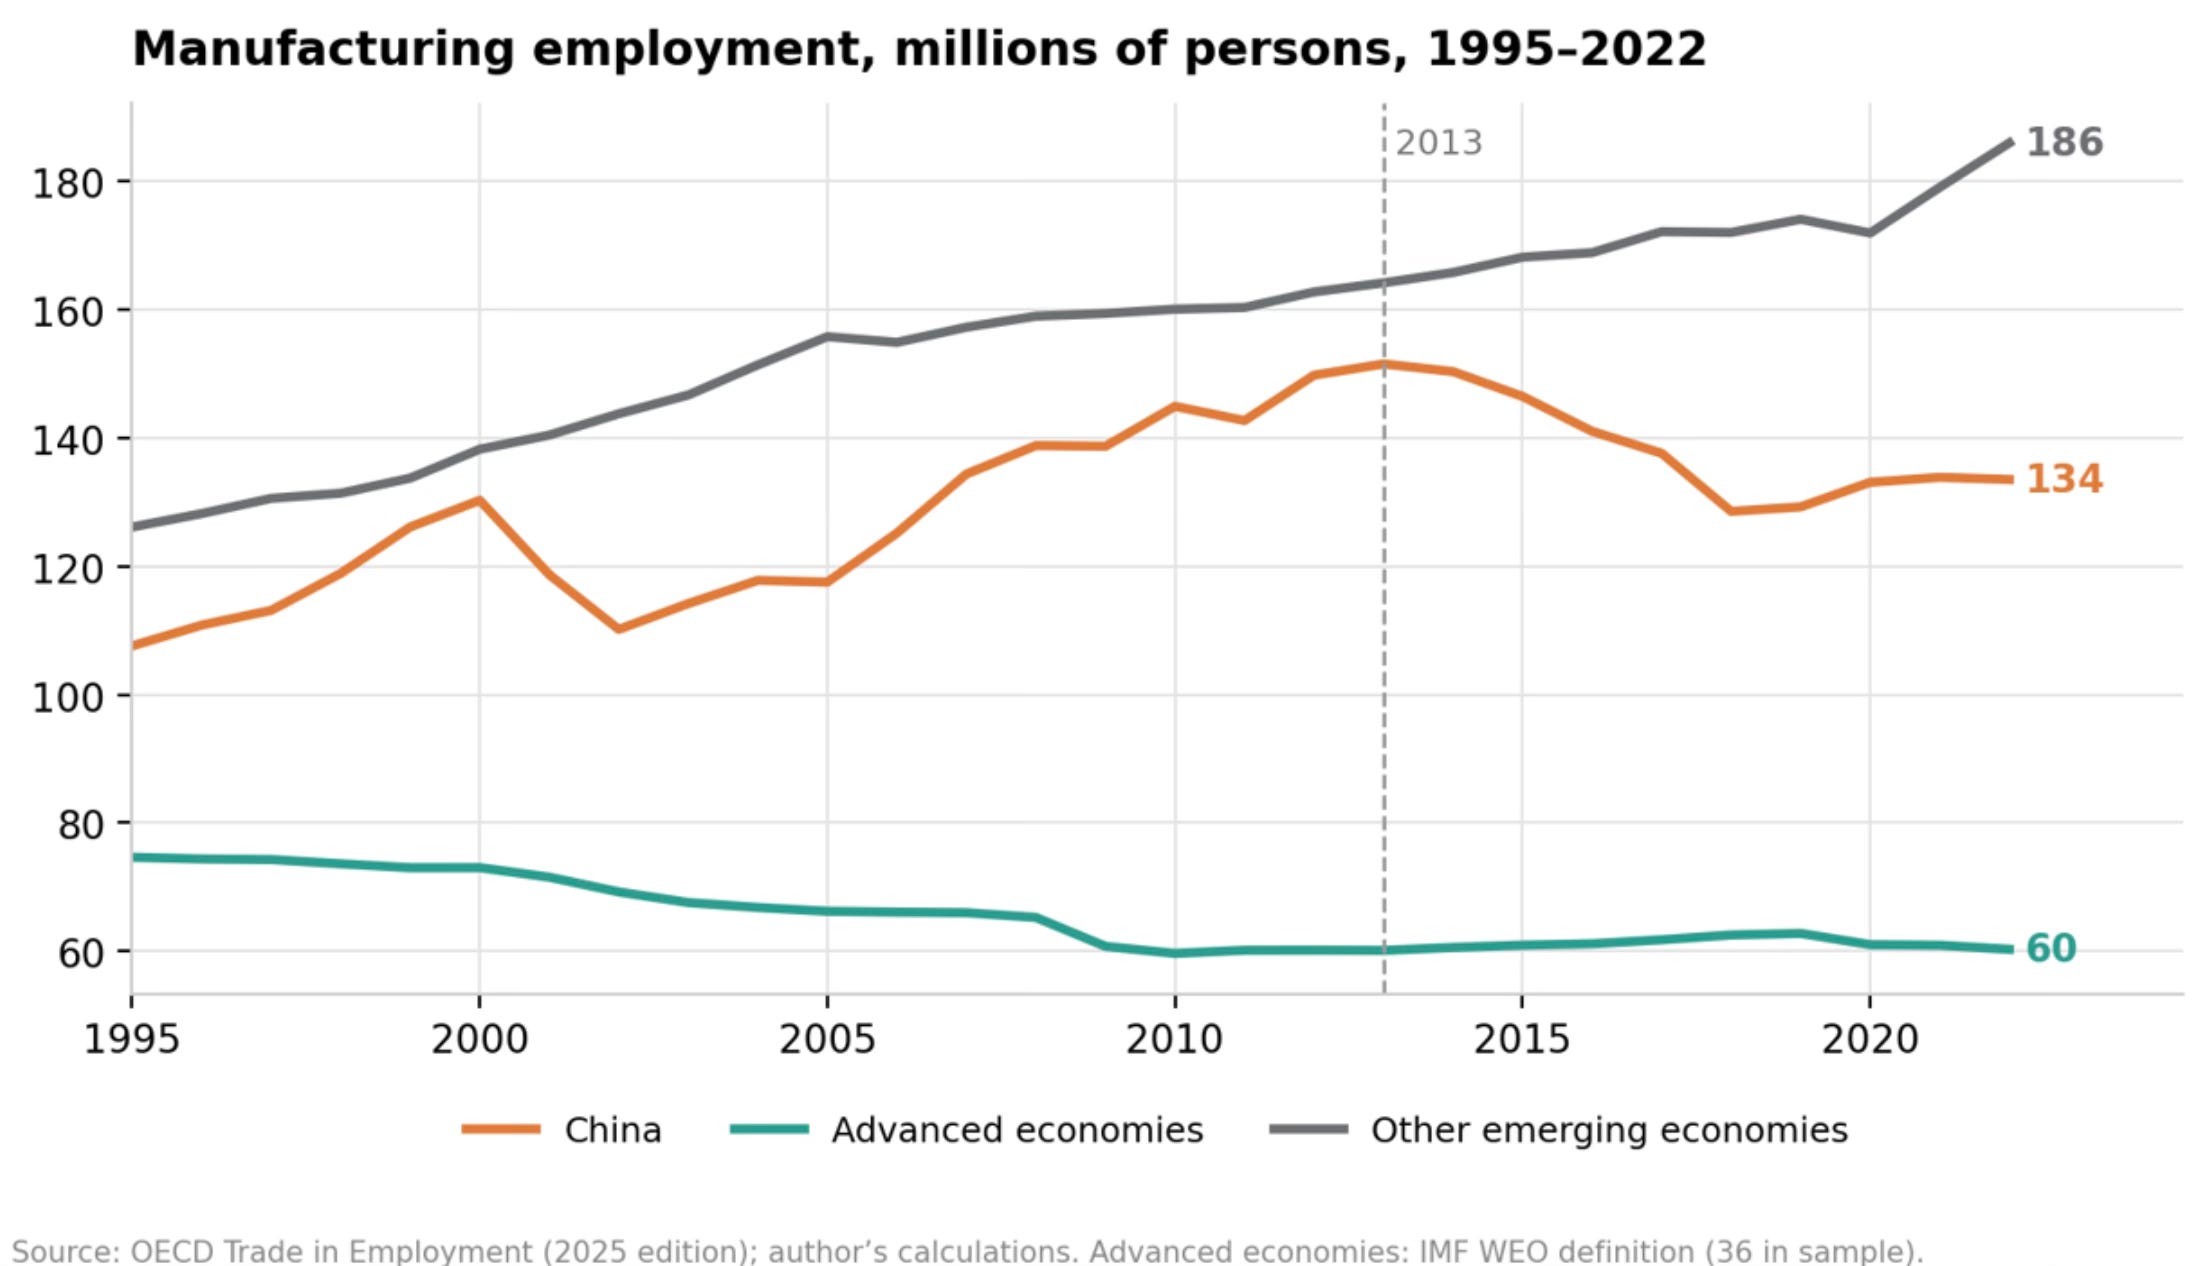
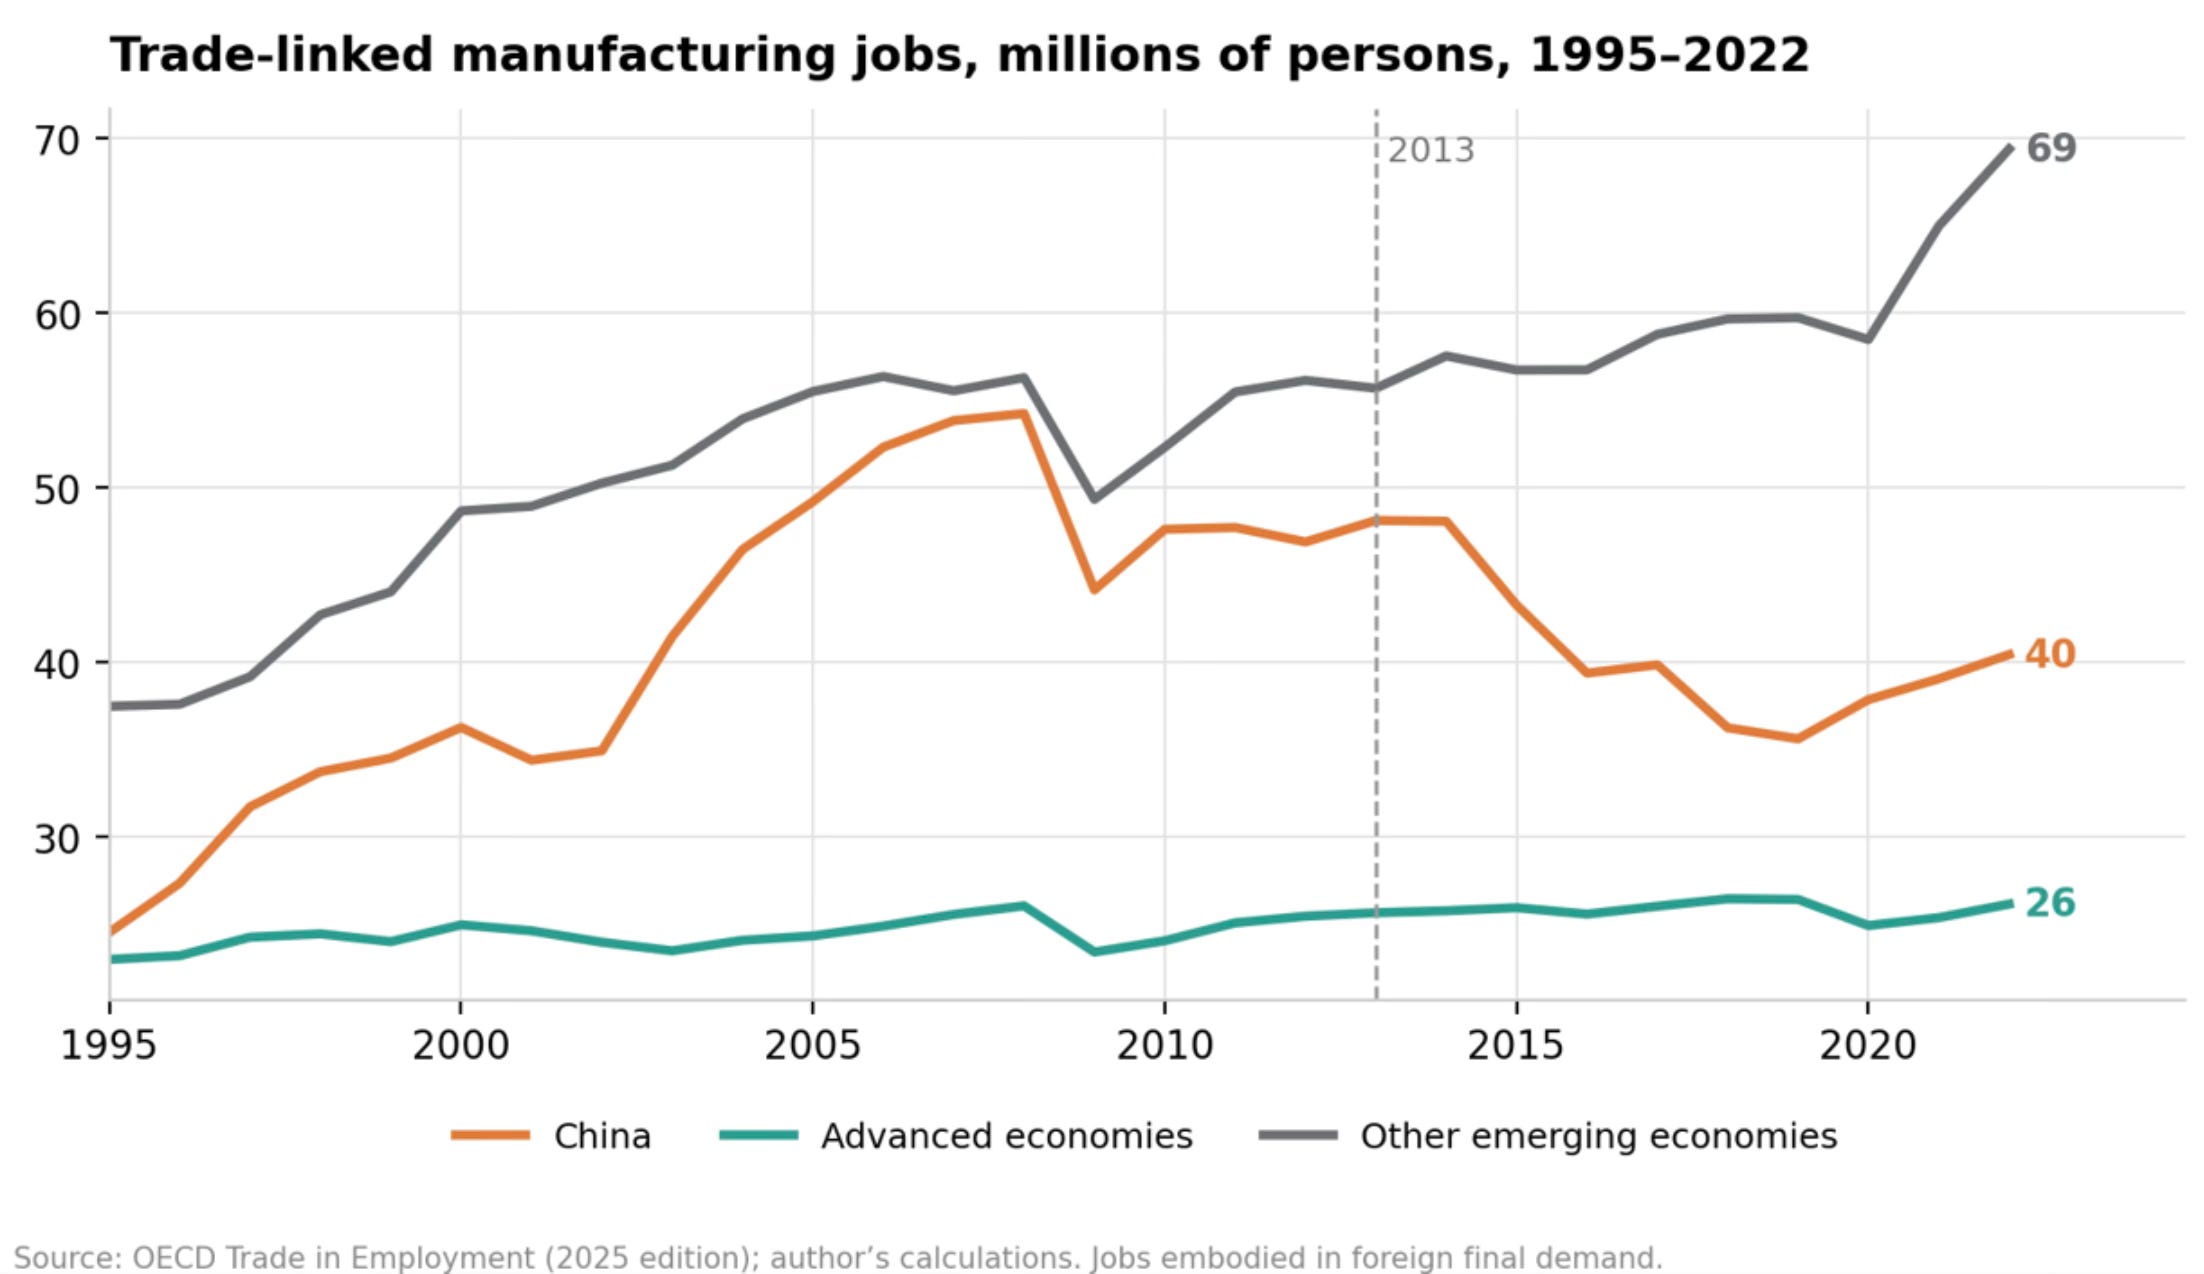
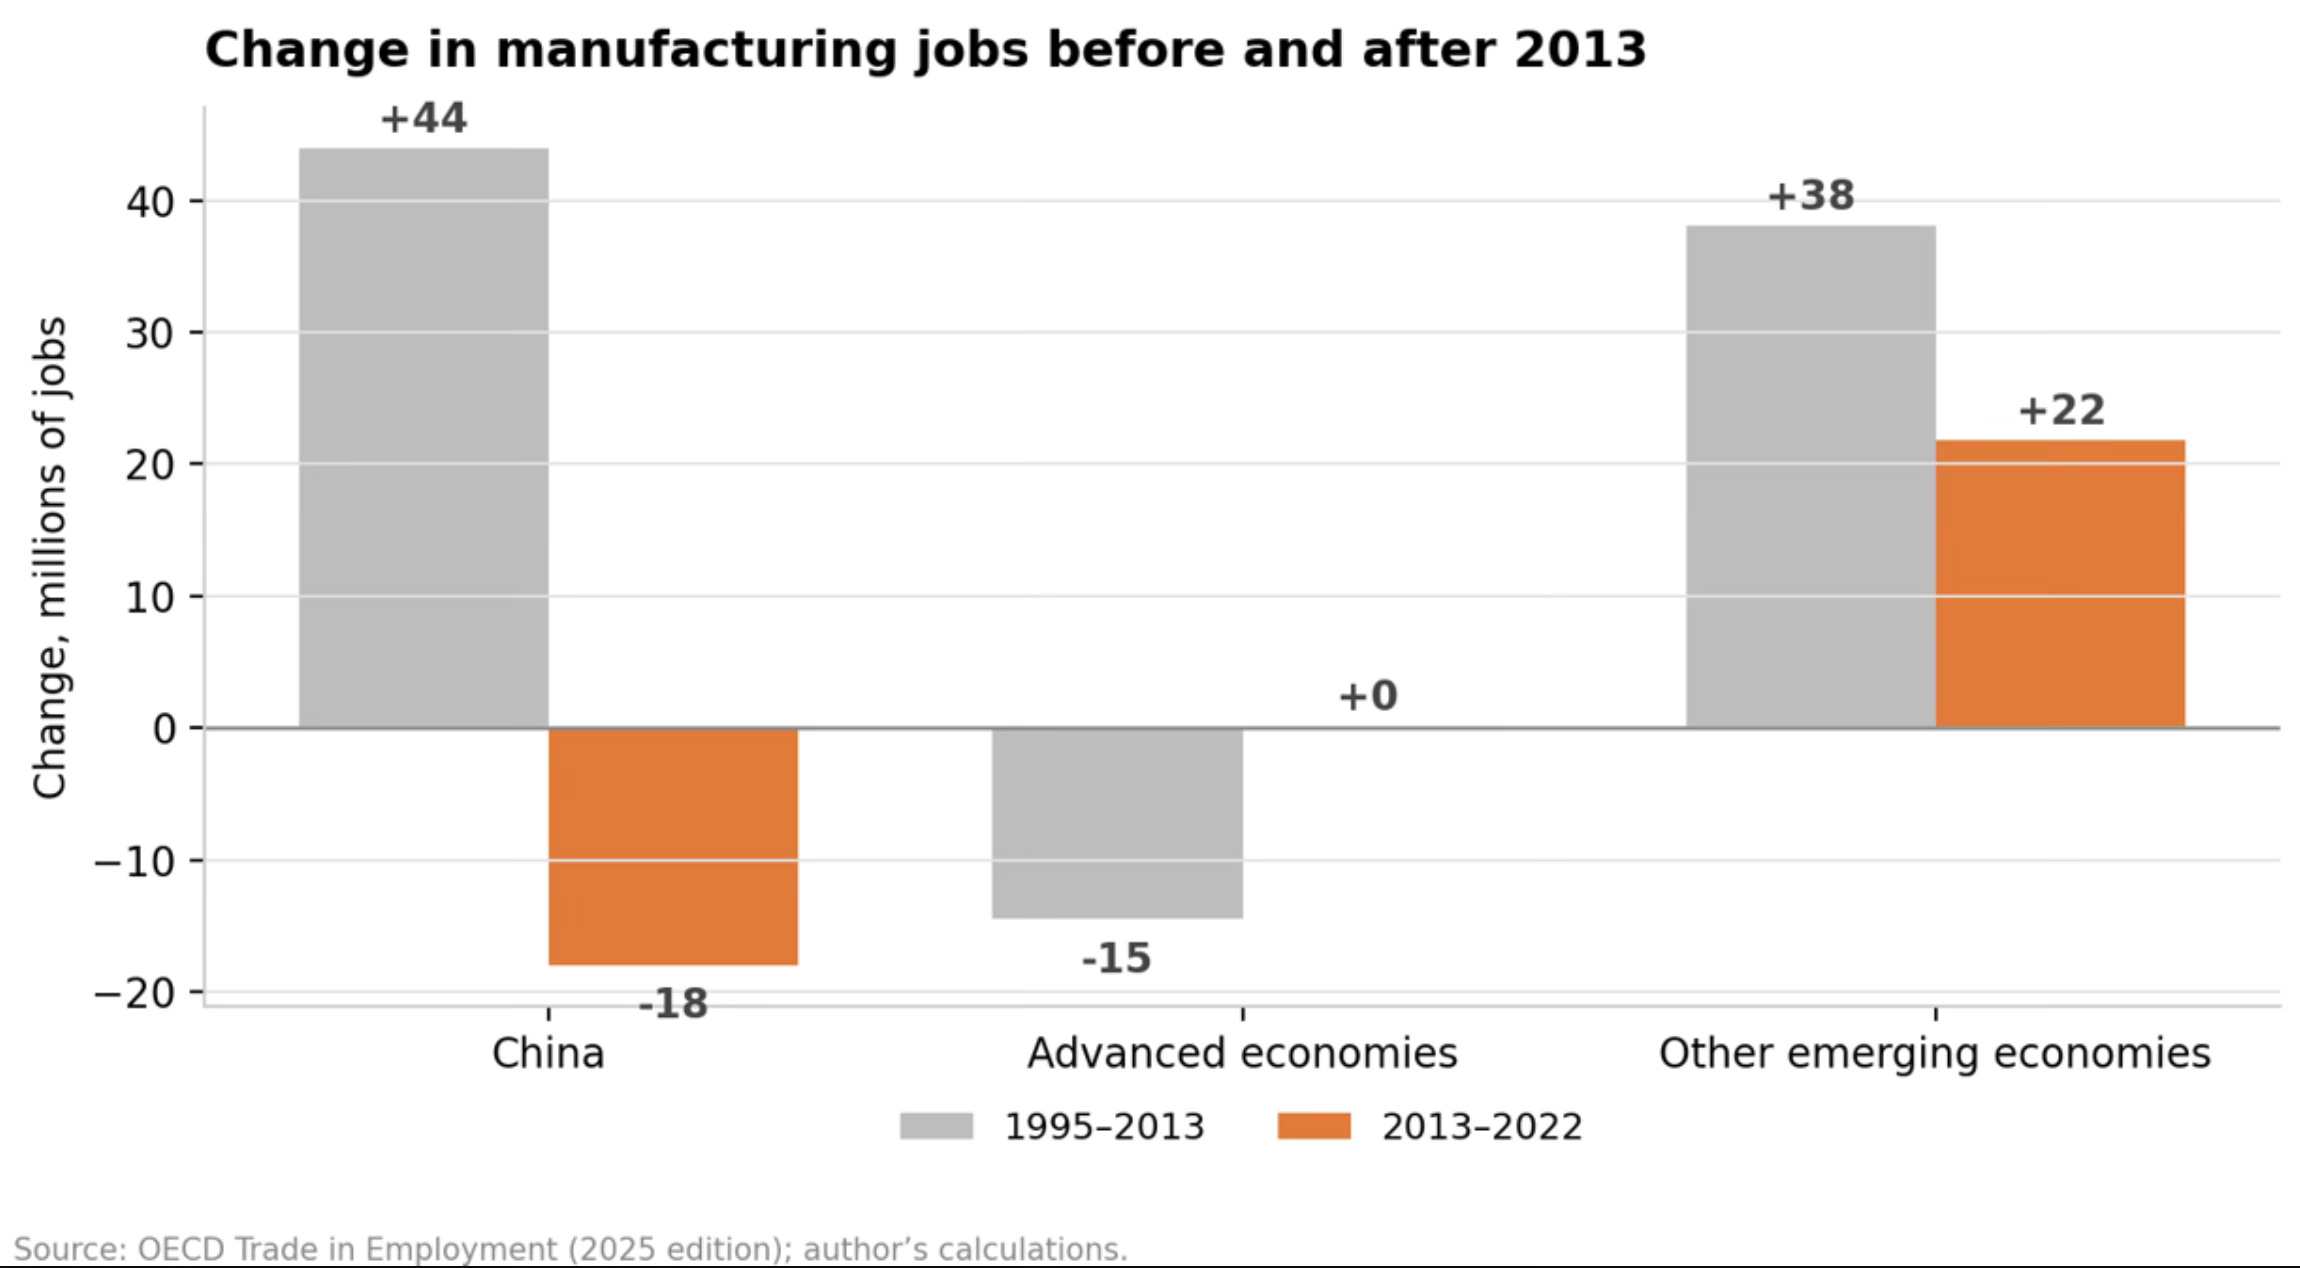
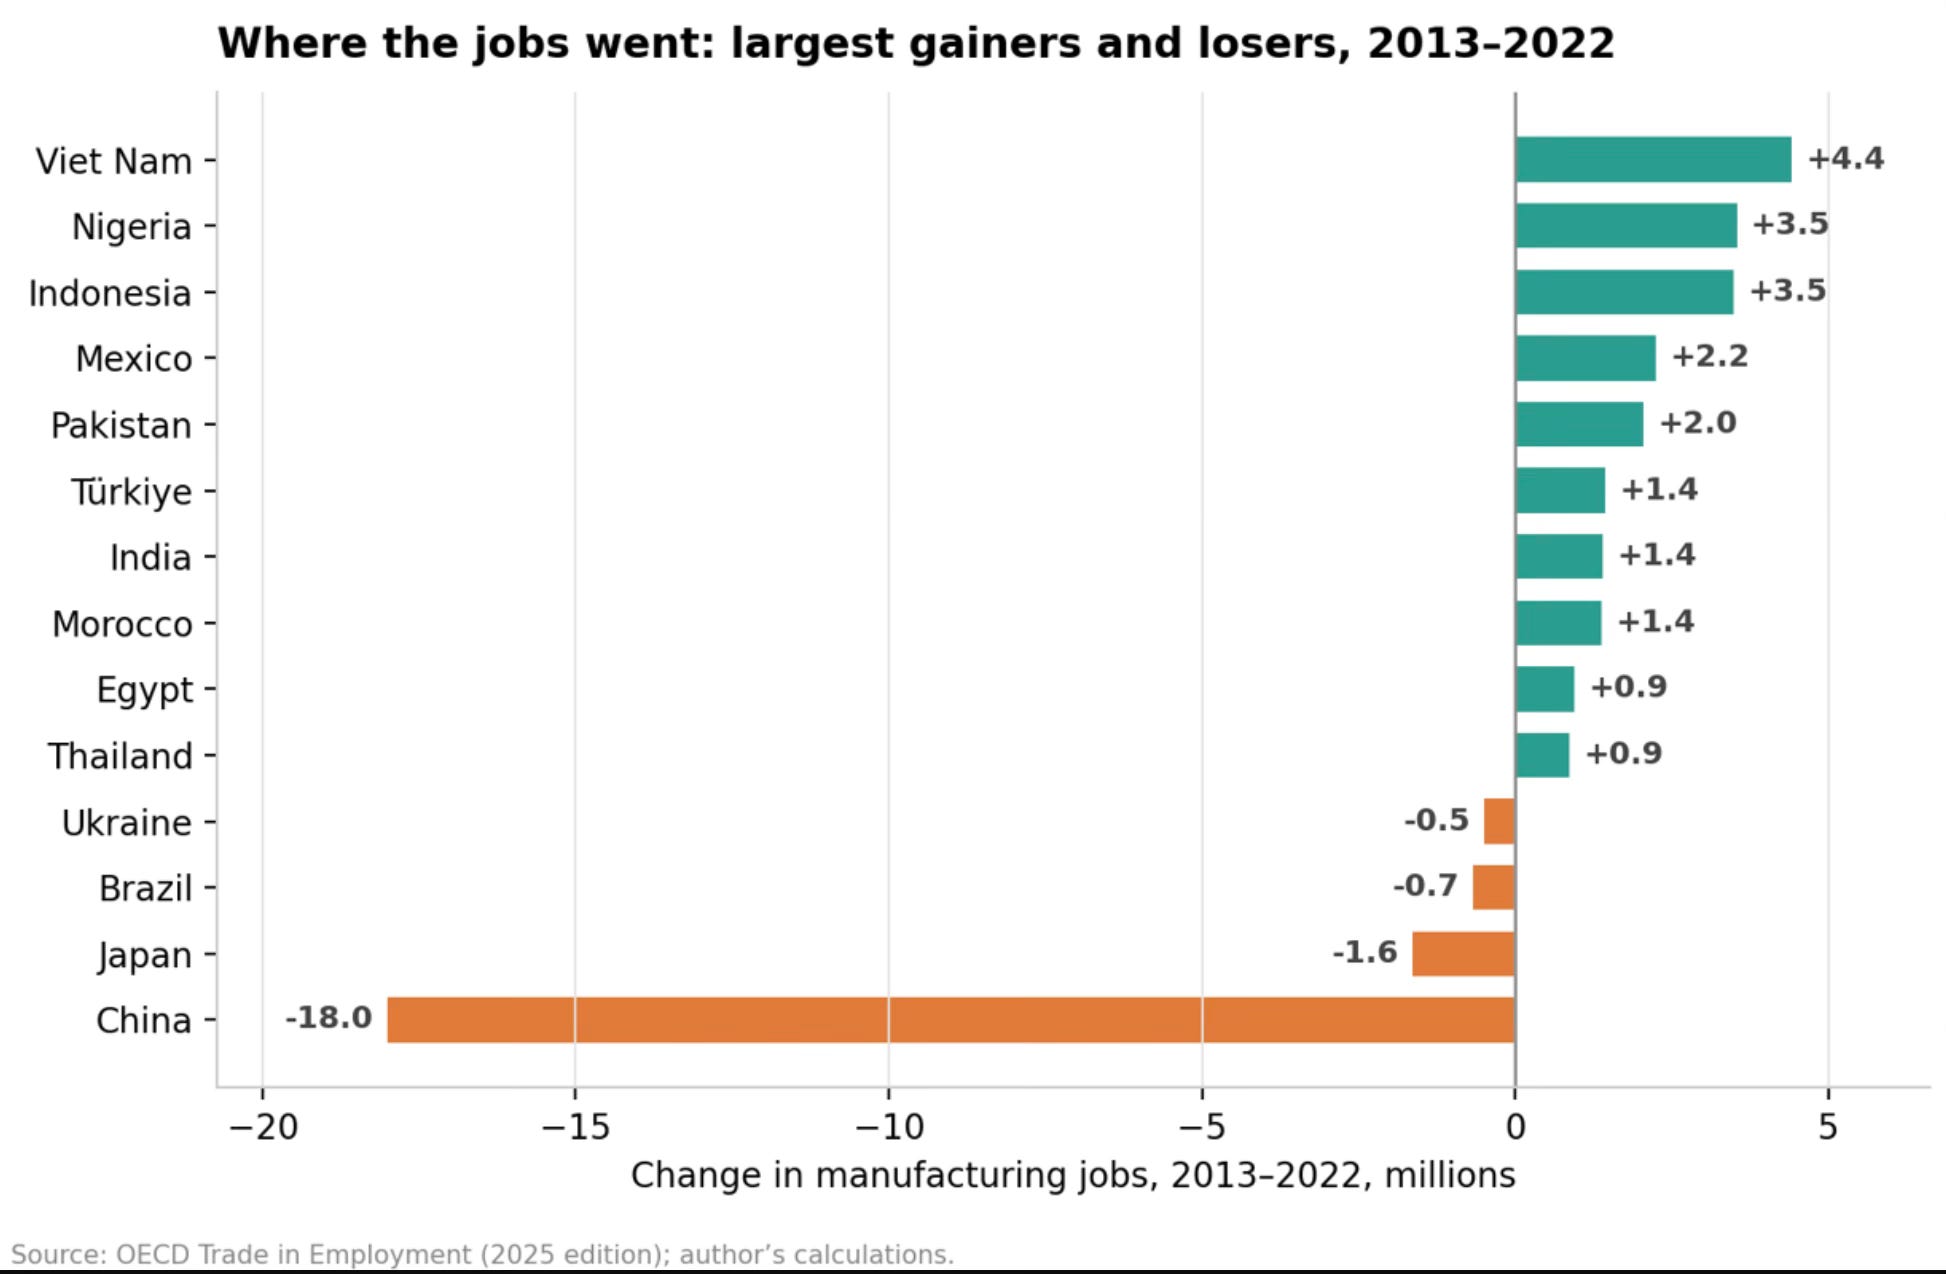
1. A bond market story of the last two weeks has been the rise of the 10-year Japanese government bond yield above 3% for the first time since September 1996, following a weakening yen and an unprecedented bilateral market intervention with the US Treasury to shore up the currency.

The market expects a rate hike by BoJ from its current 1% to prop up the yen and also quell rising inflation. However, this would clash with the commitments of Prime Minister Sanae Takaichi for fiscal spending to boost the economy.
The pressure on yen and rising bond yields are also a matter of concern for the US, since it could trigger repatriation of the massive Japanese investments in dollar assets, including the holding of US Treasury bonds.

Japan is the top foreign holder of US government debt, with more than $1tn, much of it held by financial institutions... market concern that Japan’s enormous pension funds and life insurers, nursing tens of billions in paper losses on their bond holdings, could shift their investment strategies as yields at home become more attractive... Citi’s Takashima said life insurers had been waiting for yields on 20-year JGBs to hit 2.5 to 3 per cent but were still not buying at scale as they feared that prices could drop further.
2. This is an excellent article on baby diaper manufacturing in India. The two costliest items are not manufactured in India and are imported.

At the 56th GST Council meeting on 3 September 2025, diapers were moved from 12% to 5%, effective 22 September 2025... But SAP sits under HSN 3906, taxed at 18%... Output at 5%, inputs at 12% to 18%... input tax credit piles up faster than it can ever be set off against output tax. The credit is not lost. It is refundable under Section 54(3), and from 1 October 2025 the government began granting 90% of such refunds provisionally. But refundable is not the same as available.
Diapers are covered under PLI, and it is ending up supporting contract manufacturers who import SAP.
Until an Indian chemical major commits to commercial SAP capacity, every rupee of PLI is subsidising the assembly of imported chemistry. We are building the world's fastest converting industry on someone else's molecules.
In this case, the PLI should target the SAP manufacturing in India. Supporting contract manufacturers to make what they are already doing does not require PLI. It underlines the point that PLI needs to focus on domestic value addition and not merely investment and sales. This requires more detail-based policy making.
3. Tata Capital Healthcare Fund appears to be doing what public innovation funds ought to be doing, de-risking new market segments in healthcare.
TCHF is not really in the business of spotting the next unicorn and riding it to a listing. It is in the business of manufacturing acquisition targets. It finds a chronic, non-negotiable demand, dialysis, cancer, joint replacement, wraps a proven clinical model in Tata credibility, scales it into Bharat where nobody else will do the asset-heavy work, de-risks the operations, and hands a finished, cash-generating, regulation-cleared asset to a global consolidator or a domestic roll-up desperate to enter that exact niche...TCHF works because of a stack of things that have nothing to do with money: extreme sector focus, operational depth, brand-as-regulatory-passport, a structure that insulates it from its own parent, and the patience to build assets strategic buyers are forced to buy. Take any one away and the model wobbles... The winners in corporate venture will look... more like TCHF: narrow, patient, operationally heavy, and quietly building things the giants of their industry will one day have to acquire.


The new report shows that reading scores across the OECD have fallen by 25 points and maths by 22 points since 2018. “Given that 20 score points is roughly equivalent to a year of learning, this implies that a majority of 15-year-old students across the OECD in 2025, on average, were performing at a level typically expected of 14-year-olds,” according to Pisa. Schleicher linked the decline in the latest scores to the dominance of distracting short-form videos on platforms such as Instagram and TikTok, as the report suggested that “digital distraction” is harming education across the world. “We cannot say for sure, but skimming social media feeds and rapidly processing information may be contributing to worsening ability and motivation to engage with complex texts and data,” the report said.

5. US labour-capital share of output - rising corporate profits amidst falling wage share.
Pre-tax earnings hit an annualised $4.8tn in the second quarter, or 18 per cent of national income, according to Bureau of Economic Analysis data, the highest share since the aftermath of the second world war. Employees’ share from wages and benefits fell to 60 per cent, the lowest level since the 1950s... Bumper returns largely benefit richer Americans, who receive much of their income from investments, while middle- and lower-income households rely more heavily on pay cheques. Inflation has also outpaced wage growth, causing real hourly earnings to fall by 0.2 per cent in July versus a year earlier.

The amount of whisky maturing in casks has soared from less than 400mn litres a decade ago to around 1.4bn litres this year, or 389mn cases — enough to meet current consumption levels for three years, according to Martin Purvis and Duncan McFadzean’s Commercial Spirits Intelligence newsletter. That has caused many of Scotland’s distilleries to curtail output by more than a third, insiders say... Today’s glut is the result of increasing production during the 2010s, which led to an excess of casks maturing during times of global economic uncertainty.

7. California, the bastion of liberalism, struggles to build.
A high-speed rail line that voters approved in 2008 but that has yet to lay a track. A large housing project outside Los Angeles and the redevelopment of a Navy yard, both in planning stages for decades. The state has arguably the nation’s worst housing crisis, with rent and home prices that far exceed the national average. The high cost of living, combined with strict environmental and land-use regulations, has led to a steady migration of companies and residents to less expensive states. The main problem, Mr. Metcalf continued, is that California’s overlapping regulatory processes, scattered among state and local agencies, make it nearly impossible to approve — or even outright deny — a project. Even when the governor or state legislators get behind an idea, local governments often have effective veto power. Delay becomes the normal course of nonaction.
8. London's experience in reducing knife crimes.
Knife crime rose dramatically in Britain from 2017, especially among teenagers... Hospitalisations for “assault by sharp object” have fallen by a third in London since their peak. Knife-related homicides have shrunk by a half. Last year teenage homicides in the capital fell to their joint lowest level (similar to 2012) in almost 30 years... As English politicians scrambled for answers during the 2017-19 “epidemic”, Lord Sadiq Khan looked to Scotland. In the previous decade Glasgow, once labelled Europe’s murder capital, had achieved impressive reductions in violent crime. One reason was the roll-out of the Scottish Violence Reduction Unit (VRU), which aims to prevent violent crime by bringing the police, schools, hospitals and sports clubs together to identify at-risk children and direct them away from crime. Between 2008 and 2018 Scotland’s VRUs were credited with bringing about a 38% fall in homicides and a 43% drop in attempted murders and serious assaults—many of them knife-related.Lord Khan announced England’s first VRU in London in 2018. Today there are 20 such units across England and Wales, covering areas that account for 80% of all knife crime. A recent Home Office review found that England’s VRUs caused a 12% fall, since 2019, in hospital admissions for violent assault among the under-25s. That is modest compared with Glasgow, but the Home Office looked only at the national average. Violent crime has fallen most in cities like London—dense urban areas where the model is easiest to implement.
9. The state of gender empowerment.
In India violence against women is so normalised that nearly 40% even of women think a husband is sometimes justified in beating his wife. In Mali the figure is nearly 70%... In South Asia only a third of women are in the labour force; in the Middle East and north Africa, only a fifth are. Since 1990 the share of labour income that accrues to women has risen from 35% to 44% in liberal France; in patriarchal Pakistan, from 1.5% to a still-woeful 9%. Removing the barriers to women working would raise income per person by a fifth in many countries, estimates the World Bank—a bigger economic benefit than avoiding a typical civil war...Yet even the most sexist laws can be scrapped, as Saudi Arabia has shown. Before a series of reforms that started in 2011, women there were barred from all but a handful of jobs and not even allowed to drive. Now they are free to work, drive and shun the hijab if they choose. The share of women in the labour force has nearly doubled since 2010, from 18% to 34%. That is startling progress for a kingdom many thought hopelessly stuck in the past—even if there is still a long way to go.
See also this.
10. Nvidia is the central bank of AI?
Over the past three years it has pledged over $70bn in investment in startups and offered $300bn in financial support to its customers... It has promised around $25bn in future equity investments. It owes around $33bn in debt. Its potential liabilities to customers amount to about $300bn, but only come into play in a downturn and so do not appear on its balance-sheet. These include the $105bn guarantee behind OpenAI’s data centre; as much as $125bn through the Wall Street partnership; and around $67bn in other backstops.
Also this
Nvidia’s financial engineering is partly a response to its biggest customers’ transformation into rivals. “Hyperscalers”, tech giants such as Amazon, Google, Meta and Microsoft, account for roughly half of Nvidia’s revenue. This year they are projected to invest around $800bn, largely on AI infrastructure. But most of them have begun designing their own chips, which puts their future purchases from Nvidia in doubt. For the hyperscalers, these custom chips are much cheaper, costing between a fifth and a third as much as Nvidia’s...

Hyperscalers have investment-grade credit ratings, which keep their borrowing costs low. Upstart neoclouds have similar spending needs, but little revenue. Their loans are naturally much more expensive. Alphabet, Google’s parent company, sold $2.75bn of 50-year bonds in November, at an annual interest rate of 5.7%. The rate at which CoreWeave, the biggest neocloud, borrowed $2.6bn in July was almost double. It is this gap, between hyperscalers’ borrowing costs and everyone else’s, that the bank of Nvidia would like to narrow. One way it does that is by taking equity stakes in startups that will be customers themselves or that will help fuel demand for Nvidia’s chips indirectly. Last year Nvidia made about 90 such investments, nearly twice as many as two years earlier. This year it has already agreed another 60-odd.Some of these cheques aim to propagate open-weight AI models, which users can download free of charge and adapt, unlike proprietary offerings from firms like Anthropic, OpenAI and Google, which users tend to access via subscriptions and whose inner workings are hidden. In August Nvidia agreed to pay Poolside, a startup building AI coding models, $6bn to license its software and a further $1bn for a stake. It has also agreed to buy Hugging Face, a platform hosting open-weight models, for $12.9bn. The intention behind such investments is to fuel demand for Nvidia’s chips by creating a proliferation of AI products and companies that are independent of the hyperscalers... In early July it announced a new stratagem in which it promises to top up neoclouds’ income from new data centres to an agreed floor. These undertakings, the exact terms of which vary from deal to deal, often last for six years. Throughout that period, Nvidia promises to pay a set price for “compute”, as the jargon has it. If the neocloud manages to sell the capacity in question at a higher price, Nvidia receives a share of the difference. This safety-net makes neoclouds’ future revenues much more predictable and so lowers the cost of the debt they take on to build new data centres. That, in turn, spurs demand for Nvidia’s processors.
In the graphic below, red are neoclouds, yellow are AI labs, and blue are financial firms. Also, the dashed circles are equity stakes, and the black boxes indicate guarantees and purchase commitments.

Morgan Stanley, an investment bank, reckons Nvidia’s “all-in” debt will rise from $53bn early next year to $200bn by the beginning of 2029 as guarantees come into effect. But that is offset by a stash of cash and liquid securities currently worth $99bn, and a business that will generate about $200bn in cash this year. Only a cataclysmic downturn that caused all Nvidia’s guarantees to come due and its profits to evaporate almost entirely would imperil the company—as things stand. The picture may change, however, if Nvidia’s commitments keep growing.
See also this.
11. Friendships across classes matter for life outcomes.
Recent research suggests... having pals across class boundaries appears to be one of the strongest predictors of upward mobility for people in low socio-economic groups... What’s more, children who grow up in areas with more cross-class mixing go on to earn more on average, controlling for parents’ income. To isolate the effect of the county itself, the researchers tracked families who moved. Assuming those moves were not related to their children’s future prospects — a reasonable assumption — the analysis found that people who spent a larger portion of their childhood in a better-connected county went on to earn more.


India’s space ecosystem has expanded significantly, with more than 450 space industries and over 440 startups now engaged in the sector. Isro is facilitating greater private-sector participation through the government-owned, company-operated (GOCO) model, under which private industry can manufacture, test and supply components and subsystems using its own facilities and infrastructure. Isro has facilitated nearly 440 technology transfers so far, enabling wider adoption of space technologies.
14. The victory of the far-right Alternative for Germany (AfD) in the Saxony-Anhalt province in the east of Germany was expected. Though it has fallen short of a majority by just three seats, an FT editorial calls for allowing it to form the government.
The firewall, a well-intentioned policy of non-cooperation with the far right, which is considered a threat to democracy, has turned into a trap for the mainstream parties, particularly the Christian Democratic Union of Chancellor Friedrich Merz. As support for the CDU shrinks, it is forced to share power invariably with its leftwing opponents in dysfunctional coalitions, whose quarrelling and meagre results drive votes to the AfD, further reducing the scope for compromise between the centrist parties. The firewall has failed to stem the AfD’s advance and is probably furthering it. The alternatives, though, are all bad given the far right’s current strength...The least bad outcome there would be for the party to take power with the backing of the Bündnis Sahra Wagenknecht (BSW), a small leftwing nationalist movement that rejects the firewall approach. An AfD regional government would lack the powers to enact some of its more outlandish policies, such as abolishing the right to asylum or renewing energy imports from Russia. To be sure, it could be an extremely uncomfortable time for Germans of immigrant backgrounds and other minorities living in the state. But extra vigilance from the courts and civil society could help to keep a far-right regional government in check. The far right would pose less danger in power regionally than nationally and executive responsibility could deflate its support. In any case, its opponents lack the seats to form an alternative majority. To try to do so would look undemocratic, given AfD’s vote share, and could backfire electorally.
15. Despite all its ubiquity, India's media and entertainment industry is a small revenue earner in proportion to its size.
Last year, IT accounted for 7.3 per cent of India’s GDP, against 0.8 per cent from M&E. The figure is 7 per cent for the US and 4.6 per cent for China... At $32 billion in revenues, the Indian M&E business is abysmally small. It is about a third the size of the Walt Disney Company or roughly equal to that of Tata Consultancy Services. Given the numbers, almost 700 million smartphone users, 650 million television viewers, and 421 million newspaper readers — the size of the firms in any of these segments doesn’t even scale up to Indian standards, let alone global ones... There are only two large media firms with any scale — JioStar and Google India — both at roughly $4 billion in top line. For a country that loves to chat and debate, there is no news brand that has found traction elsewhere. Ninety per cent of all that is watched in theatres, on TV or streaming is Indian stories. Yet there is no global entertainment firm of any heft from India... there is talk about Indian cinema’s soft power globally. But our presence in the global market is a blip compared with, say, Hollywood or Korea. The Indian movie business has been stuck at $1.5-$2 billion in domestic revenues for years. Indian studios simply do not have the money or distribution heft to attempt full-fledged global releases. It is only when the domestic market hits $10 billion or more will you have Indian studios that can have the strength and appetite to go global.
16. This contradicts the oft-repeated claim that a generous social safety net has made Europe a region of shirkers.

17. Huw van Steenis channels Charles Goodhart on the importance of practical wisdom in monetary policy.
Goodhart once put it to me, “every Monetary Policy Committee should have members who have a real-world understanding of the plumbing of financial intermediaries”. In my shorthand: the PhDs need the plumbers.
18. The latest PISA school test scores, where Swedish student scores declined, draws attention to the debate on the country's decision to encourage private schools. Contrary to public perception, Sweden has gone the farthest among continental European countries in privatisation of schools, healthcare, and elderly care, through a series of reforms in the 1990s and 2000s.
About one in five Swedish children now goes to an independent school... This week’s scores in the international Pisa survey revealed the country’s worst-ever rankings of levels of reading, maths and science of 15-year-olds... The Swedish system is as distinct as it is extreme. Unlike most countries with private schools, Sweden’s system is meant to be egalitarian — so the schools are open to all, through the same free system as state-funded institutions. The private schools receive funding from the state in a voucher system that means they get the same amount of money per pupil as state schools, but can make profits from it if they run things efficiently.
19. Chinese exports have been growing faster than world imports since the turn of this decade.
20. Finally, an excellent long read on how Javier Milei is taking deregulation to boost Argentina's oil and gas and mining sectors.